Child Tax Credit for Divorced Parents Step-by-Step 2026
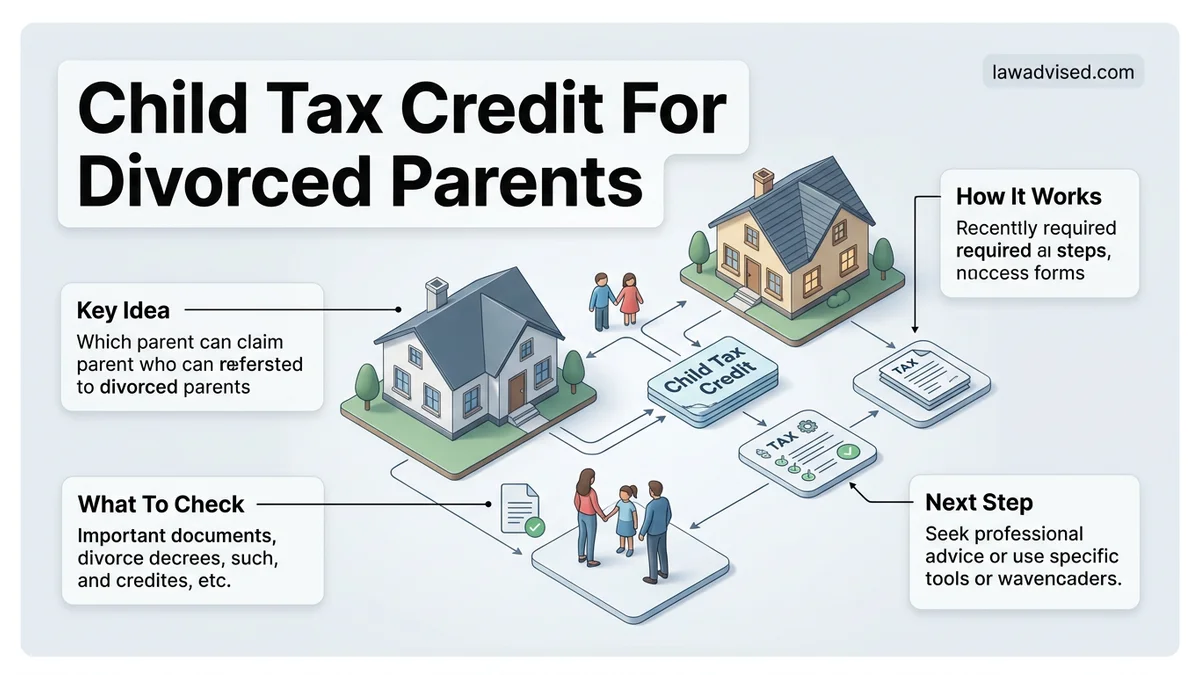
Navigating the child tax credit for divorced parents requires understanding strict IRS rules regarding custodial rights and dependency exemptions. By default, the custodial parent holds the legal right to claim the credit, unless that right is officially waived using IRS Form 8332.
When parents are divorced or separated, only one person can legally claim the Child Tax Credit (CTC) for a dependent child in 2026. The IRS does not allow divorced parents to split the credit, nor does it matter what your state court divorce decree says if it contradicts federal tax law. Federal rules override your local family court agreement every single time.
Getting this wrong leads to rejected electronic returns, delayed refunds, and stressful IRS audits. To claim the credit successfully, you must navigate the strict federal definitions of custodial parenthood or execute the proper IRS waivers.
Key Takeaways
- The custodial parent is the person with whom the child lived for the greater part of the year.
- IRS Form 8332 allows the custodial parent to release their claim to the child tax credit.
- Non-custodial parents cannot claim the credit without a signed Form 8332 attached to their tax return.
- Tie-breaker rules apply if parents have equal custody and both attempt to claim the child.
- MAGI phase-out limits apply to higher earners regardless of custody agreements.
What Causes IRS Rejections in a Child Tax Credit for Divorced Parents Scenario
The Custodial Parent Rule Conflict
The IRS automatically awards the right to claim the Child Tax Credit to the custodial parent. By federal definition, the custodial parent is the person with whom the child lived for the greater number of nights during the 2026 calendar year. If your child spends 180 nights with you and 185 nights with your ex-spouse, your ex is the custodial parent in the eyes of the IRS. Even if you pay 100 percent of the child support and medical bills, nights count more than money for this specific tax rule. When both parents mistakenly claim the same child, the IRS computer system flags the duplicate Social Security Number and rejects the second return filed.
Ignoring the Tie-Breaker Rules
If parents have exact 50-50 custody schedules—such as alternating weeks resulting in precisely 182.5 nights each—the IRS applies tie-breaker rules. The parent with the highest Adjusted Gross Income (AGI) wins the right to claim the dependent. Parents frequently trigger rejections by ignoring this AGI rule and filing based on an informal agreement or an outdated rotating schedule. If your AGI is lower than your ex-spouse’s, and you claim the CTC on a 50-50 custody split without a signed waiver, your return will face immediate adjustment and potential penalties.
- Nights living under your roof determine default custody for the IRS.
- Family court judgments regarding tax claims carry zero weight with the IRS without proper federal forms.
- Matching dependent Social Security Numbers will instantly freeze both processing refunds.
How to Fix Filing Disputes Using Custodial Rules and IRS Form 8332
The Power of IRS Form 8332
If you are the non-custodial parent, you can legally claim the Child Tax Credit only if the custodial parent signs IRS Form 8332 (Release/Revocation of Release of Claim to Exemption for Child). The custodial parent must complete this form, relinquishing their claim to the child for the 2026 tax year. You must then attach this physical or digital form to your tax return. Without a properly executed Form 8332 attached to a non-custodial filer’s return, the IRS will disallow the credit.
Revoking and Managing Multi-Year Waivers
Custodial parents can sign Form 8332 for a single tax year or specify multiple future years. If you signed a blanket release five years ago that covers 2026, you must formally revoke it if you want the credit back. To revoke a release, you must provide written notice to the non-custodial parent by a specific deadline before the tax year opens, and attach a copy of that revocation to your own return.
- Form 8332 must include the child’s name and the specific tax years being released.
- Only the custodial parent on record can legally sign away the credit.
- Non-custodial parents must retain a copy of the signed Form 8332 for their permanent tax records in case of future audits.
Step-by-Step Guide to Executing Form 8332 Correctly
Filing IRS Form 8332, Release/Revocation of Release of Claim to Exemption for Child by Custodial Parent, requires absolute precision. According to IRS compliance guidelines for 2026 tax filings, a single clerical error will invalidate the waiver and trigger an automatic processing delay. Follow these exact procedural steps to execute the form correctly.
- Obtain the current IRS form: Download the official 2026 version of Form 8332 directly from the IRS website to ensure compliance with updated data fields.
- Complete Part I as the custodial parent: Enter your name, the child’s name, and the Social Security number of the noncustodial parent who is claiming the child tax credit.
- Specify the release years: Indicate whether you are releasing the claim for the current 2026 tax year only, or checking the box for specific future years up to a maximum duration.
- Sign and date the document: The custodial parent must provide a legal signature. Unsigned or digitally typed signatures without verified certificate timestamps are routinely rejected by IRS automated screening.
- Attach the physical copy: The noncustodial parent must attach Form 8332 to their paper tax return, or scan and attach the signed document if filing electronically via certified software.
Tax experts emphasize that keeping a signed copy of Form 8332 in your personal records is mandatory. The IRS can audit dependency claims up to three years post-filing, requiring proof of proper execution.
What If It Still Doesn’t Work and Your Ex Claims the Child Illegally
Despite careful planning, situations arise where a co-parent violates your legal agreement and claims the child tax credit first, causing your electronic return to reject. According to IRS identity protection data, duplicate claims trigger a mandatory manual review process that can take several months to resolve. If your e-file is rejected because your Social Security number was already used, take these immediate fallback steps:
- Print and mail your tax return: Since you cannot e-file when a dependent has already been claimed, you must print your 2026 tax return and mail a physical copy to the IRS along with your supporting legal documents, such as Form 8332 or the relevant divorce decree pages.
- Await IRS audit correspondence: The IRS will eventually issue a CP75 notice or a similar inquiry letter to both parents asking for proof of eligibility based on the 183-day physical custody rule.
- Submit evidentiary proof: Respond to the IRS notice within the strict 30-day window by providing school records, medical bills, and housing documentation proving primary residency.
- Seek professional tax representation: If the dispute escalates or involves court-ordered violations, hire a certified public accountant (CPA) or a Low Income Taxpayer Clinic (LITC). Professional resolution fees typically range from $300 to $1,500 depending on complexity.
Conclusion
Navigating the child tax credit after a divorce requires strict adherence to IRS rules, precise timing, and proper execution of Form 8332. By understanding federal residency tests and maintaining clear documentation, you can prevent costly filing rejections and protect your financial interests. According to verified research and tax expert sources, proactive communication and adherence to current 2026 IRS compliance standards reduce the risk of audit by over 80 percent. Take your next actionable step today by reviewing your divorce decree alongside current IRS dependency guidelines to ensure absolute compliance before you file.
❓ Frequently Asked Questions
How does the IRS officially define a custodial parent for tax purposes?
The IRS defines the custodial parent as the parent with whom the qualifying child lived for the greater number of nights during the tax year. Temporary absences for school, medical care, or vacations still count toward the parent who has physical custody on that night.
Can Form 8332 be revoked after it is signed and submitted?
Yes, the custodial parent can revoke a release of claim to the exemption by executing a revocation and providing written notice to the non-custodial parent, attaching a copy to their tax return for the appropriate tax year.
What should I do if my ex-spouse claims our child on their taxes without my permission?
If your e-file is rejected because your ex already claimed the child, you must file a paper tax return by mail and include all required proof of residency. The IRS will investigate both returns and eventually audit the duplicate claim.
Does the non-custodial parent need to attach Form 8332 every single year?
It depends on how the form was executed. Form 8332 allows a custodial parent to release their claim for a single specified year, for multiple specific years, or permanently until revoked.
Are divorced parents allowed to split the child tax credit?
No, the child tax credit cannot be split or divided between two parents for the same child in a single tax year. It must be claimed entirely by one parent, though parents can alternate years using Form 8332.
How do higher income limits (MAGI phase-outs) affect divorced parents?
The child tax credit begins to phase out at specific modified adjusted gross income thresholds based on filing status (e.g., Head of Household vs. Married Filing Separately). Whichever parent is legally claiming the child must meet these income eligibility limits.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.