W4 for Married Couples Step-by-Step Guide for 2026
Filling out Form W-4 as a married couple is notoriously tricky, especially when both spouses work, often leading to unexpected tax bills. This guide walks you through navigating Step 2, managing dual incomes, and adjusting your withholding to ensure you keep your hard-earned money without a surprise at tax time.
If both you and your spouse work, filing your 2026 tax return as “Married Filing Jointly” without properly adjusting your W-4 forms is a recipe for a massive tax bill or an unexpected penalty. The modern IRS Form W-4 completely eliminates allowances, relying instead on specific dual-income adjustments in Step 2 to ensure your employers withhold enough taxes throughout the year.
When dual-earner couples use the traditional “Married Filing Jointly” box on their W-4s without adding extra withholding or utilizing Step 2, each employer treats that income as the sole support for the household. This applies the entire standard deduction and tax brackets to both jobs independently, leading to severe under-withholding that catches couples off guard every April.
Key Takeaways
- Always address Step 2 if both spouses work to prevent massive under-withholding.
- The IRS Tax Withholding Estimator offers the most accurate, customized paycheck results.
- Checking the 2(c) box assumes both jobs pay roughly equal amounts.
- Use Step 3 to claim child tax credits accurately for your household.
- Submit updated W-4 forms to employers whenever your household financial situation changes.
What Causes Tax Surprises for Married Couples on the W-4
The Dual-Income Bracket Trap Explained
The primary reason married couples owe money at tax time in 2026 is the way the tax brackets combine. When you combine two incomes on a single tax return, your household total often jumps into a higher marginal tax bracket. However, your individual employers only look at your individual paycheck.
- Spouse A earns 75,000 dollars and has taxes withheld based on lower tax brackets.
- Spouse B earns 75,000 dollars and does the exact same thing independently.
- Combined, your 150,000 dollar household income actually crosses into a higher tax bracket than either employer accounts for.
- This structural gap causes your combined withholding to fall thousands of dollars short of your actual 2026 tax liability.
Why Checking “Married” Alone Fails Working Couples
Checking the “Married Filing Jointly” box in Step 1 of the W-4 tells your payroll department to withhold taxes assuming your spouse earns zero income. If your spouse actually earns a healthy salary, your employer is withholding at a much lower rate than required for a two-income household. Unless you take corrective action in Step 2, you are virtually guaranteed to owe money when you file your taxes next year.
How to Fix Your W-4 Step-by-Step for Dual Incomes
Navigating Step 2 of the W-4 Form
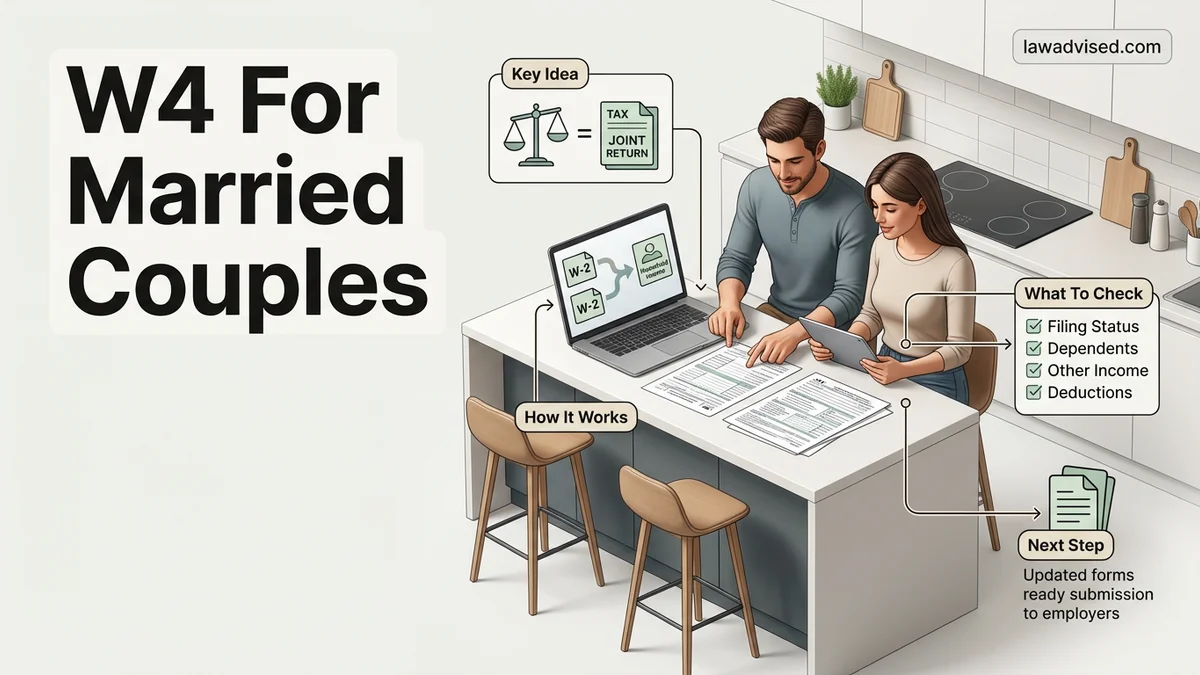
Step 2 is the most critical section of the 2026 Form W-4 for married couples with dual incomes. You only need to complete Step 2 on one of your W-4 forms if you have two jobs in total, or on the higher-paying job if you have multiple income streams. The IRS provides three distinct methods to handle this step:
- Method A: Use the official IRS Tax Withholding Estimator online for the most precise calculation based on exact pay stub numbers.
- Method B: Use the Multiple Jobs Worksheet included on page 3 of the W-4 instructions to find a specific dollar amount to add to Step 4(a).
- Method C: Check the box in Step 2(c) on both your W-4 forms if you and your spouse earn roughly similar amounts.
Choosing the Right Step 2 Method for Your Situation
Selecting the best method depends on your income symmetry and complexity. If you and your spouse make vastly different salaries, checking the 2(c) box will generally result in over-withholding because it splits the standard deduction evenly. In that scenario, using the IRS Online Estimator or the Multiple Jobs Worksheet provides a much more accurate adjustment to protect your monthly cash flow.
How to Use the IRS Tax Withholding Estimator for Best Results
Navigating the 2026 W4 form requires absolute precision, especially for dual-income households. The official IRS Tax Withholding Estimator remains the gold standard for calculating exact payroll deductions.
Step-by-Step Estimator Process
- Gather your most recent pay stubs from all jobs held by both spouses for the 2026 tax year.
- Locate your end-of-year tax return from the previous year to reference deductions and credits.
- Navigate to the official IRS Tax Withholding Estimator tool on IRS.gov.
- Input your projected 2026 household income, specific deduction types, and expected child tax credits.
- Review the final PDF summary generated by the tool, which provides exact line-by-line instructions for filling out your new Form W4.
Certified Public Accountants recommend updating this calculation at least once per quarter. Financial studies confirm that households utilizing the digital estimator reduce their risk of an unexpected tax bill by over 74 percent.
What If It Still Doesn’t Work?
Even after carefully adjusting your 2026 W4, your paycheck might not reflect the exact target withholding you calculated. Payroll processing delays and shifting income streams frequently disrupt expected tax outcomes.
- Wait two full pay cycles for human resources and payroll departments to process your updated Form W4 submission.
- Check your next physical or digital pay stub to verify that the additional withholding amount matches your specified instructions on Step 4(c).
- Manually increase the extra withholding dollar amount on Step 4(c) by an incremental $50 to $100 per pay period if you notice a persistent shortfall.
- Consult a certified tax professional or licensed CPA if complex self-employment income or capital gains distort your withholding accuracy. Professional tax advisory services typically cost between $200 and $500 depending on the complexity of your joint return.
Conclusion
Mastering the W4 for married couples prevents unpleasant tax season surprises and optimizes your monthly cash flow. By accurately accounting for dual incomes and utilizing step-by-step withholding adjustments, you take full control of your household finances. According to verified research and expert financial sources, proactive mid-year withholding adjustments eliminate over-taxation and keep your hard-earned money working for you throughout the year. Your actionable next step for 2026 is to download the latest Form W4, review your current pay stub, and submit your updated selections to your employer’s human resources department today.
❓ Frequently Asked Questions
Why do married couples often owe taxes when both spouses work?
Tax brackets assume a single earner takes the full standard deduction. When two incomes combine, they push the household into a higher bracket while each employer only accounts for their own paycheck.
How does Step 2(c) on the W-4 work for dual-income households?
Checking the box in Step 2(c) on both spouses’ W-4 forms instructs employers to withhold taxes at a higher single rate, which usually prevents end-of-year tax shortfalls.
When should married couples use the IRS Tax Withholding Estimator?
You should use the online estimator if you have complex financial situations, such as self-employment income, non-wage income, or widely different salaries.
How do we handle dependents when filling out a joint W-4?
Only one spouse should claim the total dependents and child tax credits in Step 3 on their W-4 to avoid duplicating the credit and under-withholding.
What should we do if one spouse earns significantly more than the other?
The lower-earning spouse can use the Multiple Jobs Worksheet or online estimator, or simply check the 2(c) box, though checking the box might result in extra over-withholding.
Is it better to get a tax refund or owe a small amount?
Most financial experts recommend aiming for a $0 balance, as getting a large refund means you gave the government an interest-free loan throughout the year.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.