
Mortgage Interest Deduction for Rental Property 2026
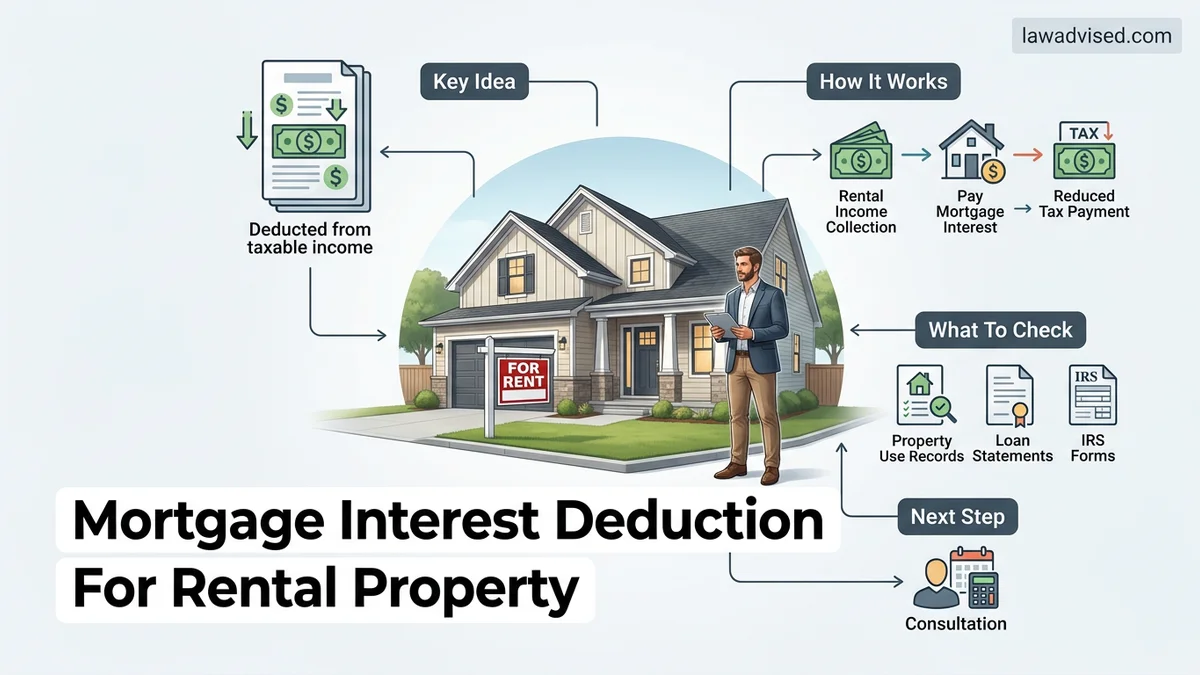
Property owners can deduct mortgage interest as a standard business operating expense to directly lower their taxable rental income. Understanding IRS rules and correct Schedule E reporting is essential to maximize these tax savings legally.
Yes, you can fully deduct mortgage interest on a rental property as an ordinary and necessary business expense. Unlike primary residences where interest is claimed as an itemized deduction on Schedule A, rental property mortgage interest is reported directly on Schedule E (Form 1040) to offset your gross rental income dollar-for-dollar.
As you navigate your taxes in 2026, leveraging this deduction remains one of the single most effective strategies for lowering your taxable rental income. This deduction directly targets your cash flow, meaning every dollar of interest paid reduces the net income upon which your federal income tax is calculated.
Key Takeaways
- Mortgage interest on rental properties is fully deductible as an operating expense.
- Report your deductible interest annually using IRS Form 1040 Schedule E.
- Points and loan origination fees must be amortized over the loan life.
- Personal-use days can trigger strict IRS limitations on interest deductions.
- Keep thorough mortgage statements and lender Form 1098 records for auditing.
What Causes Rental Property Mortgage Interest to Be Deductible
The Business Expense Classification
The IRS views rental real estate activities as a business or for-profit venture. Consequently, the interest you pay on a loan secured by your rental property is treated as an operating expense. To qualify for this deduction in 2026, you must meet three strict IRS criteria:
- You must be legally liable for the debt under the mortgage agreement.
- You must actually make the mortgage payments from your own funds or business accounts.
- The property must be actively held out for rent to generate income.
Interest Versus Principal Payments
Only the actual interest portion of your monthly mortgage payment is deductible. The principal portion—the amount that builds your equity—is never deductible as an expense. Your annual Form 1098, sent by your mortgage lender, will break down the exact interest paid during the year, ensuring you separate these two components accurately.
How to Calculate and Claim the Rental Mortgage Interest Deduction
Calculating Your Deductible Amount
Calculating your total deduction requires tracking the interest accrued across all 12 months of the tax year. If you refinanced your rental property in 2026 or purchased it mid-year, you must prorate the interest based on the exact billing statements provided by your lender. Points paid to secure a loan on a rental property cannot be deducted in a lump sum; instead, they must be amortized over the life of the loan.
Reporting on Schedule E
When tax season arrives, you will report your total deductible mortgage interest on Line 13 of Schedule E (Form 1040). For example, if your rental generated 24,000 dollars in gross rent and you paid 10,000 dollars in mortgage interest alongside 4,000 dollars in maintenance and property taxes, your net taxable rental income drops to 10,000 dollars before depreciation. This direct reduction keeps your adjusted gross income lower and preserves your capital for future investments.
What If Your Deduction Is Limited by IRS Passive Activity Rules
Navigating the mortgage interest deduction for rental property in 2026 requires understanding how IRS passive activity loss rules impact your write-offs. Generally, rental real estate activities are considered passive by definition. If your modified adjusted gross income exceeds certain thresholds, the IRS may limit your ability to deduct rental losses against your active income, such as W-2 wages or business profits.
Understanding the 25,000 Special Allowance
Real estate investors with a modified adjusted gross income of $100,000 or less may deduct up to $25,000 of passive rental losses against non-passive income, provided they actively participate in the property management. This special allowance phases out completely for taxpayers with incomes between $100,000 and $150,000. When mortgage interest creates a loss that pushes you past these limits, the disallowed interest deduction is not lost forever. Instead, it is suspended and carried forward to future tax years until you generate passive income or sell the property.
Strategies for High-Income Earners
High-income earners often find their rental mortgage interest deductions trapped by passive activity limitations. To bypass these restrictions, qualifying taxpayers can aim for Real Estate Professional Status with the IRS. Achieving this status requires meeting strict hourly thresholds: performing more than 500 hours of service in real property trades or businesses, and proving that this real estate work constitutes more than half of your total personal services performed during the 2026 tax year. Successfully qualifying transforms your rental activity from passive to non-passive, unlocking full deductions against ordinary income.
What If It Still Doesn’t Work?
If your standard mortgage interest deductions remain restricted or complex after reviewing the basic rules, specialized intervention is necessary. Implement these structured steps to resolve lingering compliance issues:
- Reconcile your 2026 Form 1098 statements directly against your monthly bank statements to ensure lenders have not misallocated escrow payments or points.
- Audit your time logs and participation records if you are attempting to qualify for real estate professional status or the active participation exception.
- Separate personal use days from rental use days meticulously using property management software to recalculate allowable interest ratios.
- Consult a certified public accountant or a licensed tax attorney specializing in real estate taxation for a comprehensive portfolio review. Expect to pay professional fees ranging from $350 to $1,500 depending on the complexity of your multi-property portfolio.
Conclusion
Maximizing the mortgage interest deduction for rental property in 2026 demands strict adherence to IRS classification rules, precise income tracking, and careful navigation of passive activity limitations. When deductions face restrictions, utilizing carryforward rules or pursuing active participation exceptions secures your financial return. According to verified research and expert sources from the National Association of Realtors, proactive tax planning remains the single most effective way for landlords to optimize net operating income. Your immediate next step is to gather all 2026 Form 1098 documents and cross-reference your adjusted gross income against current IRS phase-out thresholds before filing.
❓ Frequently Asked Questions
How does the rental property mortgage interest deduction reduce my taxes?
Mortgage interest acts as a business expense that directly offsets your gross rental income. By lowering your net taxable rental income, you reduce the total income tax you owe for the year.
What is the difference between primary residence interest and rental property interest?
Primary residence mortgage interest is claimed as an itemized deduction on Schedule A, subject to loan amount caps. Rental property interest is treated as an ordinary business expense on Schedule E without those personal caps.
Can I deduct interest for months when the rental property sat vacant?
Yes, you can continue to deduct mortgage interest during vacancy periods as long as the property is actively being marketed and held out for rent.
How do I handle mortgage interest if I use the rental property personally?
If you use the property for personal purposes exceeding 14 days or 10% of the total days rented, you must allocate the mortgage interest between rental use and personal use.
Are late payment penalties on a rental mortgage deductible?
Generally, IRS rules state that late payment charges and penalties are considered non-deductible personal or penalty expenses, unlike the core mortgage interest.
What records should I keep to support my mortgage interest deduction?
You should retain your year-end Form 1098 provided by your mortgage lender, bank statements proving interest payments, and your loan amortization schedule.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.