Married Filing Jointly vs Separately Expert 2026 Guide
Choosing between married filing jointly vs separately directly impacts your tax brackets, deductions, and eligibility for valuable credits. Filing jointly saves most couples money, but specific financial situations like heavy medical debt or income-driven student loans make separate filing advantageous. Run the numbers both ways before submitting to guarantee maximum savings.
For the vast majority of married couples, filing your taxes as Married Filing Jointly (MFJ) will save you the most money and grant access to the most lucrative tax credits. However, choosing Married Filing Separately (MFS) can protect you from a spouse’s tax liability or significantly lower your monthly student loan payments under income-driven repayment plans.
Deciding between these two filing statuses in 2026 comes down to a strict mathematical comparison of your combined versus individual income, deductions, and specific credit eligibility. Let us look at the financial mechanics that dictate which status will keep more cash in your bank account.
Key Takeaways
- Filing jointly qualifies couples for significantly higher standard deductions and tax brackets.
- Married Filing Separately disqualifies you from major credits like the EITC and Child and Dependent Care Credit.
- Separate filing can lower income-driven student loan payments by isolating your individual adjusted gross income.
- High out-of-pocket medical expenses are easier to deduct when filing separately due to the adjusted gross income percentage floor.
- Joint filers share strict legal liability for any tax errors, omissions, or unpaid balances on the return.
What Causes Tax Bracket and Deduction Differences Between Filing Statuses
The Math Behind Tax Brackets and Standard Deductions
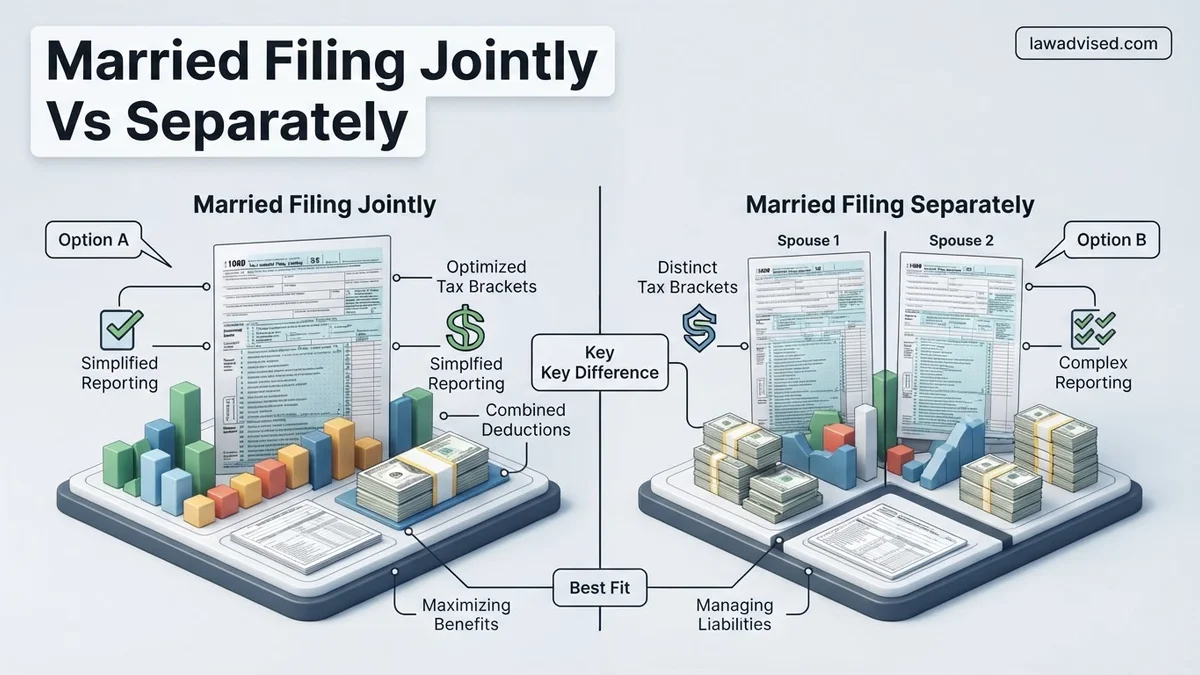
The IRS structures tax brackets and standard deductions to prevent what is known as the marriage penalty, though it still impacts certain high-earning dual-income households. When you file jointly, the income thresholds for each marginal tax bracket are generally double—or close to double—the single filer thresholds, but they are often less than double the MFS thresholds.
For the 2026 tax year, understanding how your combined income stretches across these brackets determines your baseline tax liability. If one spouse earns a high salary and the other earns very little, combining incomes under MFJ usually pulls the higher earner’s income down into lower brackets than they would face if filing separately.
- Standard Deduction: The MFJ standard deduction is exactly double the Single deduction, whereas the MFS deduction is equal to the Single deduction. This means you do not lose total deduction volume by choosing to file jointly.
- Bracket Compression: MFS brackets compress the income thresholds. Two people filing separately often hit top marginal rates much faster than they would combined on a joint return.
The Impact on Major Tax Credits
Your filing status acts as a gatekeeper for vital tax credits that can swing your final tax liability by thousands of dollars. The rules are strict and heavily favor joint filers.
- Child Tax Credit (CTC): MFJ status allows full access to phase-out thresholds that accommodate higher combined family incomes. MFS status cuts these phase-out thresholds in half, potentially disqualifying middle-income families.
- Earned Income Tax Credit (EITC): If you file as Married Filing Separately, you are automatically disqualified from claiming the EITC in almost all circumstances.
- Education and Care Credits: The Child and Dependent Care Credit and the American Opportunity Tax Credit either phase out rapidly or become entirely unavailable if you choose MFS.
How to Calculate and Compare Your Tax Liability Step-by-Step
Running Dual Scenarios Before Submitting
You cannot rely on guesswork when choosing your 2026 filing status. To find your true savings, you must calculate your tax liability both ways before finalizing your return.
Start by calculating your joint tax liability. Add your adjusted gross incomes (AGI), subtract the generous MFJ standard deduction, and apply the joint tax brackets. Then, factor in all child and educational credits you qualify for as a couple.
- Calculate total combined tax liability using the Married Filing Jointly rules and thresholds.
- Calculate individual tax liabilities for Spouses A and B separately using the Married Filing Separately rules, ensuring you allocate itemized deductions or credits correctly.
- Compare the net bottom lines, making sure to account for any lost credits in the MFS scenario.
Accounting for State-Specific Tax Rules
Federal calculations are only half the battle. Your state-level tax obligations might completely flip the script on which filing status makes financial sense.
If you live in a community property state like California, Texas, or Arizona, state laws often require you to split your earned income equally between both spouses even when filing separate federal returns. This can neutralize the intended protective benefits of MFS status on your state return, creating complex administrative burdens and unexpected tax bills. Always run your state tax software simulation alongside your federal comparison.
How to Fix Student Loan and Medical Debt Strategies Using Separate Filing
Filing separately offers a proven tactical mechanism for lowering income-driven student loan payments. Many federal repayment plans calculate monthly obligations using individual adjusted gross income rather than combined spousal earnings. Leveraging Married Filing Separately isolates your income, which often produces a significantly lower monthly bill under plans like SAVE or PAYE.
Isolating Income for Loan Optimization
According to Department of Education guidelines, choosing separate status excludes your spouse’s salary from the calculation. This strategy requires balancing the reduction in student loan payments against the loss of valuable tax credits. Financial analysts recommend running dual tax simulations before filing to confirm the net savings outweigh the higher tax liability.
Managing Medical Expense Deductions
Medical debt creates another financial hurdle that separate filing can occasionally mitigate. The IRS permits individuals to deduct unreimbursed medical expenses that exceed 7.5 percent of their adjusted gross income. When one spouse incurs massive medical bills alongside a lower individual income, separate filing makes reaching that 7.5 percent threshold much more achievable.
- Calculate individual adjusted gross income for both spouses separately.
- Compare the prospective student loan savings against lost tax credits like the Earned Income Tax Credit.
- Evaluate total out-of-pocket medical expenses against the individual 7.5 percent AGI floor.
- Execute the filing status that yields the highest net financial benefit for 2026.
What If State Laws and Legal Liabilities Complicate Your Choice
State property laws frequently override federal tax assumptions regarding income allocation. In community property states such as California, Texas, and Arizona, spouses generally must split earned income equally on separate returns. This legal requirement effectively neutralizes many income-isolating strategies that taxpayers living in common-law states rely upon.
Navigating Community Property Nuances
Taxpayers residing in community property jurisdictions must report half of their combined community income on each separate return. This rule complicates recordkeeping and frequently requires specialized tax software or professional intervention. Furthermore, separate filing does not shield either spouse from joint liability associated with previously filed joint returns or shared state tax debts.
Protecting Assets from Shared Liabilities
Legal liabilities extend beyond standard tax debts into areas like injured spouse allocations and past-due federal obligations. If the government seizes a tax refund for past-due child support or default loans, filing separately protects the innocent spouse’s portion of the refund in non-community property states. Consulting state-specific tax codes remains essential before finalizing your 2026 return.
- Verify whether your primary state of residence operates under community property laws.
- Calculate income splitting requirements if community property rules apply to your household.
- Assess potential offsets for federal debts, student loans, or child support obligations.
- Implement state-specific allocation forms to ensure accurate reporting to tax authorities.
What If It Still Doesn’t Work?
If optimizing your tax status fails to yield the anticipated savings or administrative relief, targeted intervention is required. Taxpayers encountering persistent complications should execute the following fallback steps:
- Run a comprehensive multi-year tax projection using professional software to identify hidden structural penalties.
- Consult a Certified Public Accountant or Enrolled Agent specializing in complex marital tax scenarios. Expect professional consultation fees to range between $300 and $800 depending on regional market rates.
- File an amended return (Form 1040-X) if you discover that switching statuses retroactively provides a better financial outcome within the three-year statutory window.
- Contact the IRS Taxpayer Advocate Service if administrative processing errors prevent the correct execution of your chosen filing status.
Conclusion
Choosing between filing jointly and separately requires a careful mathematical assessment of your household income, debt obligations, and state residency rules. While separate filing unlocks distinct advantages for student loan repayment and medical deductions, it simultaneously triggers higher tax brackets and the loss of major credits. According to verified research and expert sources from the IRS and financial planning institutes, running dual simulations before submitting your return prevents costly financial oversights. Take the next step today by calculating your projected tax liability under both methods to secure your optimal financial outcome for 2026.
❓ Frequently Asked Questions
What are the main financial penalties of filing taxes separately?
Couples filing separately lose eligibility for critical tax breaks, including the Earned Income Tax Credit, education credits, and the child and dependent care credit. Additionally, phase-out thresholds for deductions are severely restricted.
When does Married Filing Separately actually make financial sense?
Separate filing makes sense when one spouse has massive out-of-pocket medical expenses that exceed the adjusted gross income threshold, or when managing income-driven student loan repayment plans where joint income would cause monthly payments to skyrocket.
How does community property state law affect separate tax returns?
In community property states like California and Texas, earned income and investment income must generally be split equally between both spouses on separate returns. This rule can eliminate the income-separation benefits you might expect from filing separately.
Can I file separately if my spouse refuses to sign a joint tax return?
Yes, filing separately is the only way to submit your return if your spouse refuses to sign a joint return or if you are separated and do not qualify for head of household status.
How do standard deductions differ between joint and separate filing statuses?
The standard deduction for married filing separately is exactly half of the standard deduction allowed for married filing jointly. Furthermore, if one spouse itemizes deductions, the other spouse is forced to itemize as well and cannot take the standard deduction.
Does filing separately protect me from my spouse’s tax fraud or unpaid debts?
Filing separately prevents your individual refund from being seized to pay your spouse’s past-due child support, federal student loans, or state tax debts. However, it does not erase liability for past joint returns.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.