Tax Rates For Married Couples 2026 Expert Guide
Navigating tax rates for married couples requires understanding the exact federal income tax brackets and standard deductions for your filing status. Choosing between filing jointly or separately impacts your overall tax liability and eligibility for specific credits. Expert guidance ensures you optimize your deductions and minimize your tax burden.
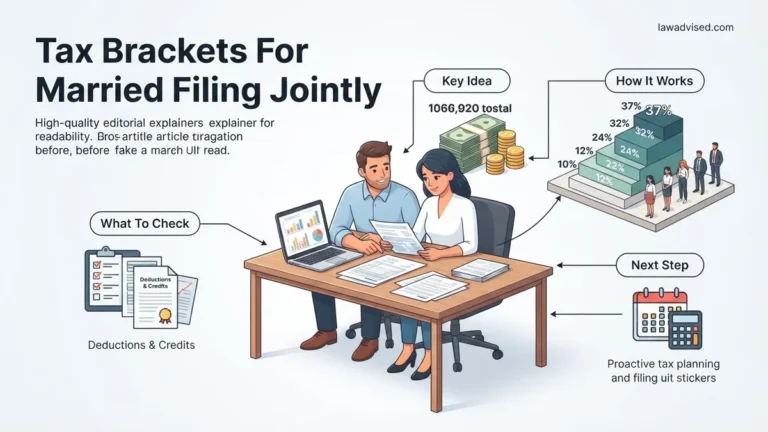
For the 2026 tax year, married couples filing jointly face federal income tax brackets ranging from 10% to 37%, applied across seven distinct marginal rates. The standard deduction for married couples filing jointly (MFJ) is projected at $30,000, while those filing separately (MFS) receive half that amount at $15,000.
Choosing the right filing status directly impacts your take-home pay, eligibility for credits, and overall tax liability. Knowing how these thresholds apply to your combined or individual income prevents unexpected bills when you file your return.
Key Takeaways
- Married Filing Jointly offers lower tax rates and wider brackets for most couples.
- The standard deduction for married couples filing jointly is significantly higher than for singles.
- Married Filing Separately often results in higher overall taxes and lost credits.
- Review your combined income against marginal tax brackets before choosing a filing status.
- Consult a tax professional to evaluate unique state and federal tax implications.
What Causes Tax Bracket Surprises for Married Couples
Navigating the federal tax code as a couple often brings unexpected financial friction. The structure of the tax brackets and standard deductions can create unintended consequences for dual-income households.
The Marriage Penalty and Bonus Effects
The term marriage penalty describes a situation where two wage earners pay more in combined federal income tax as a married couple than they would if they remained single. This happens when the combined income pushes the couple into a higher marginal tax bracket sooner than if they filed individual returns.
- Joint Bracket Compression: Certain tax brackets for married filing jointly are not exact doubles of single filer brackets.
- Phase-outs: Income-based deductions and tax credits begin to phase out at combined thresholds that may catch you off guard.
- The Bonus Side: Conversely, single-earner households often receive a marriage bonus because the lower tax brackets stretch to accommodate dual-income potential without immediate penalty.
Filing Separately Pitfalls
Choosing married filing separately seems like a safe way to keep finances distinct, but the IRS applies strict limitations to this status. Many valuable tax breaks disappear entirely when you choose MFS.
- Lost Credits: You generally cannot claim the Earned Income Tax Credit (EITC) or the Child and Dependent Care Credit.
- Higher Thresholds: The income thresholds for the 35% and 37% tax brackets are halved for MFS, stripping away the cushioning found in joint returns.
- Deduction Matching: If one spouse itemizes deductions, the other is forced to itemize as well, even if their individual deductions are minimal.
How to Fix Your Filing Status Strategy Step-by-Step
Optimizing your tax strategy requires looking beyond your combined gross income to evaluate how the 2026 tax brackets treat your specific financial situation. A proactive approach saves thousands of dollars in avoidable taxes.
Run Dual Scenarios Before Year-End
Never assume that filing jointly is automatically the best financial choice. You must calculate your tax liability under both joint and separate statuses before the tax year closes.
- Gather Documents: Compile projected income, investment gains, and potential deductions for both spouses for 2026.
- Calculate Joint Liability: Apply the 2026 MFJ standard deduction of $30,000 and run your combined income through the 10% to 37% federal brackets.
- Calculate Separate Liability: Run individual calculations using the MFS standard deduction of $15,000, factoring in any disallowed credits.
- Compare Bottom Lines: Weigh the net tax difference against the administrative burden and potential loss of specific deductions.
Adjust Withholding and Leverage Deductions
Once you select your optimal filing status for 2026, align your paycheck withholdings to match your projected liability.
- W-4 Adjustments: Use the IRS Tax Withholding Estimator to update your Form W-4, especially if both of you work.
- Senior Additions: Factor in the additional standard deduction for taxpayers aged 65 or older, which increases the basic deduction by $1,550 per person for married filers in 2026.
- Retirement Contributions: Maximize pre-tax contributions to traditional 401(k) or IRA accounts to lower your adjusted gross income and stay below restrictive threshold phase-outs.
Step-by-Step Guide to Calculating Joint Versus Separate Tax Liability
Determining whether to file jointly or separately requires a side-by-side comparison of your total tax liabilities. According to certified public accountant data, running parallel calculations prevents costly errors. Follow this numerical workflow to evaluate your 2026 tax position accurately.
Step 1: Gather Individual Financial Records
- Collect separate W-2s, 1099s, and investment income statements for both spouses.
- Identify which deductions and credits belong to individual expenses versus shared household costs.
- Document any separate property rules if you reside in a community property state.
Step 2: Simulate the Married Filing Separately Return
- Calculate each spouse’s Adjusted Gross Income (AGI) independently.
- Apply the 2026 Married Filing Separately tax brackets to each respective income stream.
- Subtract individual deductions, noting that if one spouse itemizes, the other must also itemize.
Step 3: Simulate the Married Filing Jointly Return
- Combine both incomes to determine your aggregate AGI for 2026.
- Apply the unified Married Filing Jointly tax brackets and the higher standard deduction.
- Calculate combined eligibility for major credits like the Child Tax Credit and educational incentives.
Step 4: Compare Net Totals
- Subtract total estimated withholdings and credits from the final liability for both filing statuses.
- Select the status that yields the lowest net tax due or the highest combined refund.
What If Your Income Changes or Joint Filing Fails to Save Money
Sometimes, running the numbers reveals that Married Filing Separately is actually the more advantageous path. Major life events mid-year can disrupt your initial filing strategy. If joint filing fails to deliver expected savings or creates unexpected liability, specialized intervention is necessary.
Alternative Fallback Strategies
- Evaluate significant medical expense disparities where one spouse has high out-of-pocket costs that clear the AGI threshold only on a separate return.
- Assess income-driven student loan repayment plans, which often calculate monthly payments based exclusively on individual income when filing separately.
- Review innocent spouse relief options if you fear joint liability resulting from your partner’s unreported income or tax fraud.
What If It Still Doesn’t Work?
If manual calculations yield ambiguous results or complex investments complicate your 2026 return, standard software may fall short. Execute these troubleshooting steps to resolve filing status dilemmas safely:
- Run a comprehensive tax simulation using professional-grade software that models both filing statuses simultaneously over a multi-year horizon.
- Consult a Certified Public Accountant or Enrolled Agent who specializes in multi-earner household tax planning.
- Expect professional consultation fees to range from $350 to $850 for a detailed comparative filing analysis.
- Request an extension if complex calculations remain unresolved by the April filing deadline, keeping in mind that an extension to file is not an extension to pay.
- File an amended return (Form 1040-X) within the three-year statutory window if you discover a more beneficial filing status after submission.
Conclusion
Navigating tax rates for married couples in 2026 requires balancing bracket thresholds, standard deductions, and phase-out limits. While joint filing maximizes benefits for most households, running dual scenarios protects against hidden financial penalties. According to verified research and expert tax sources, proactive comparative modeling remains the single most effective safeguard for household wealth. Schedule a formal review with a licensed tax professional before finalizing your annual submission.
❓ Frequently Asked Questions
How do marginal tax rates differ between joint and separate filing statuses?
Joint filing brackets are roughly double the width of single brackets, whereas separate filing brackets are narrower, causing couples to hit higher tax thresholds much faster. This structural difference often leads to a higher combined tax bill when filing separately.
What standard deduction amounts apply to married couples filing jointly?
Married couples filing jointly receive a significantly higher standard deduction compared to individual filers, plus an additional standard deduction amount for each spouse aged 65 or older or blind.
Can we change our filing status after submitting our tax return?
Generally, you can amend a return to change from married filing separately to married filing jointly within three years of the original filing deadline, but you cannot switch from joint to separate after the filing deadline has passed.
How does filing separately affect income-driven student loan repayment plans?
Filing separately often excludes your spouse’s income from income-driven repayment calculations, which can lower monthly student loan payments, though you must weigh this against the higher tax liability.
Are tax credits lost when choosing to file separately?
Yes, married filing separately status disqualifies you from claiming several valuable tax credits, including the Earned Income Tax Credit, the Child and Dependent Care Credit, and education-related credits.
How do community property laws impact married filing separately returns?
In community property states, couples filing separately generally must split their earned income equally between both tax returns, which complicates tax calculations and rarely eliminates tax disparities.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.