Taxes for Graduate Students Step-by-Step Guide 2026
Graduate student tax obligations depend heavily on whether your funding comes from W-2 employment, fellowships, or tax-free tuition waivers. Failing to track fellowship income or make estimated quarterly payments can lead to unexpected IRS penalties. Knowing how to classify your income ensures you file correctly and claim valuable deductions.
Graduate student taxes hinge on a unique mix of funding sources that the IRS treats very differently. If you receive a tuition waiver, it is generally tax-free, but your living stipend is almost always fully taxable income.
Navigating these rules for the 2026 tax year requires understanding IRS Section 117 and managing your own withholding or quarterly estimated payments. Mastering this process now protects you from surprise tax bills and costly penalties.
Key Takeaways
- Qualified tuition reductions for required fees are tax-free under IRC Section 117.
- Stipends and fellowships used for living expenses are fully taxable income.
- Fellowships without W-2 withholding often require quarterly estimated tax payments using Form 1040-ES.
- Teaching and research assistantship wages are reported on a W-2 with taxes withheld.
- Grad students can utilize the Lifetime Learning Credit and student loan interest deductions.
What Causes Tax Confusion for Graduate Students
Tax software often treats students like typical employees or traditional undergraduates, which causes major reporting errors. You likely fall into a hybrid category where your income comes from a mix of teaching, research, and institutional gifts.
The Myth of the Standard Student Status
Many graduate students assume that because they hold student status, all their university income is automatically tax-free. In reality, the IRS views you as a working professional if you perform services for the university in exchange for your funding. Your tuition waiver is an educational benefit, but your paycheck or fellowship living allowance is compensation for your labor.
Confusing Tax Forms and Missing Withholding
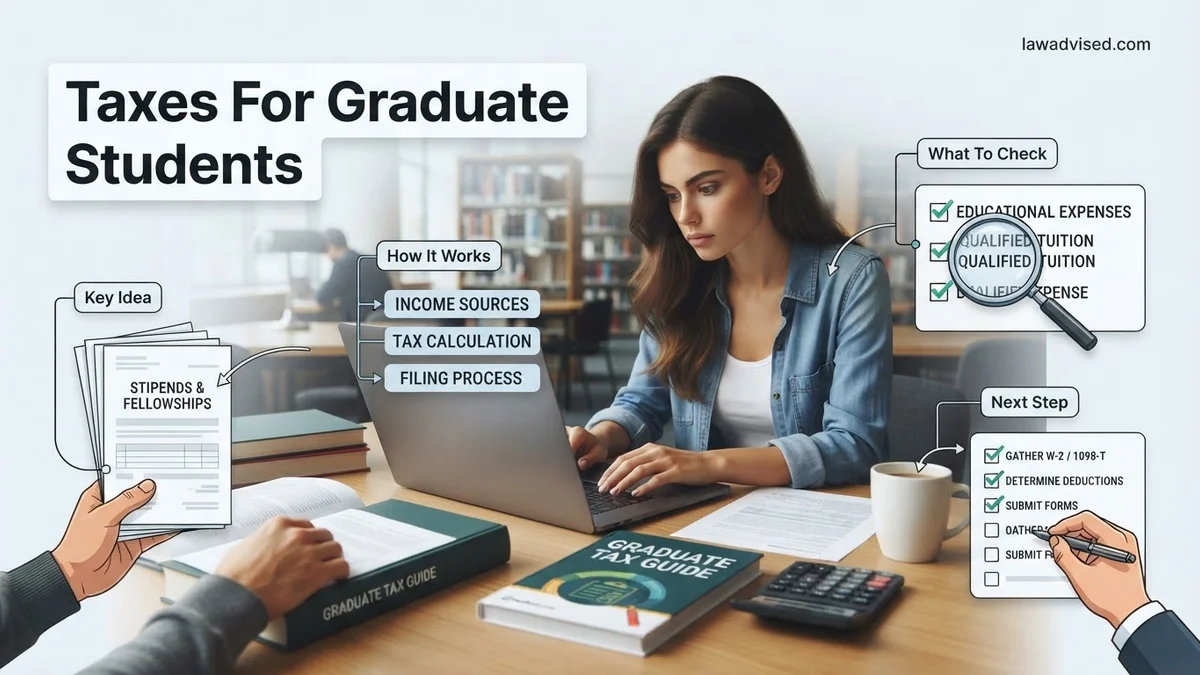
Confusion peaks when you receive multiple tax documents that do not neatly fit standard software prompts. You might receive a Form W-2 for a teaching assistantship, a Form 1098-T showing tuition charges, and nothing at all for a fellowship stipend. When organizations fail to withhold federal and state taxes from fellowship stipends, you face the responsibility of tracking and paying those taxes yourself.
How to Determine Taxability of Stipends and Tuition Waivers
The IRS separates graduate funding into two primary buckets: qualified tuition reductions and living stipends. Knowing how these categories work under IRC Section 117 prevents you from either overpaying the IRS or underpaying and facing late fees.
Tax-Free Qualified Tuition Reductions under IRC Section 117
Under Internal Revenue Code Section 117, tuition waivers for graduate teaching and research assistants are completely tax-free. To qualify for this exclusion, two conditions must be met for 2026:
- You must be a candidate for a degree at an eligible educational institution.
- The reduction must apply to tuition for education at the graduate level, and any service you provide (like teaching) must not be a requirement for all degree candidates.
If your university waives your tuition in exchange for teaching an undergraduate section, that waiver remains tax-free.
Taxable Stipends and Service Requirements
Living stipends, whether labeled as fellowships, traineeships, or assistantship salaries, are fully taxable income. If your funding requires you to provide a service—such as grading papers, conducting lab work, or teaching—that money is earned income. Even if your fellowship comes with no explicit service requirement, it is still taxable if you use it for living expenses like rent, food, and utilities rather than required tuition and books.
Step-by-Step Guide to Calculating and Filing Grad Student Taxes
Filing your taxes as a graduate student requires methodically gathering your financial documents before touching tax software. According to the IRS and higher education tax experts, preparation prevents costly calculation errors.
Step 1: Collect All Tax Forms
- Locate your Form 1098-T from your university detailing qualified tuition and related expenses paid.
- Gather all Form W-2 statements from teaching assistantships, research fellowships, or campus employment.
- Download Form 1099-NEC or 1099-MISC if you received freelance income, grading contracts, or outside stipends.
- Retrieve 1099-INT statements for interest earned on stipend savings accounts or emergency funds.
Step 2: Complete Your Income Calculations
- Subtract your tax-free fellowship or scholarship amounts used strictly for tuition, fees, and required books from your gross taxable income.
- Add your fully taxable stipends, wages, and non-qualified service grants together to find your total earned income.
- Calculate any self-employment net earnings if you performed independent consulting or side gigs during the 2026 tax year.
Step 3: Apply Deductions and File
- Input your data into IRS Free File or commercial tax software specifically designed to handle fellowship income reporting.
- Claim the Lifetime Learning Credit if eligible, which offers up to $2,000 per tax return for graduate-level coursework.
- Submit your federal and state tax returns electronically by the April 2026 deadline to avoid late penalties.
What If You Missed Estimated Tax Payments or Made Filing Errors
Many graduate students realize too late that unwithheld fellowship income required quarterly estimated tax payments. Missing these deadlines or making calculation mistakes triggers specific IRS penalty structures.
Handling Missed Quarterly Payments
- Calculate your total underpayment using IRS Form 2210 to determine if you meet penalty exception thresholds.
- Submit a larger lump-sum payment immediately with your annual tax return to stop additional interest accumulation.
- Request a first-time penalty abatement from the IRS if you have a clean compliance history for the preceding three tax years.
Amending an Incorrect Return
- Wait until the IRS processes your original 2026 tax return before submitting any modifications or corrections.
- Complete Form 1040-X, Amended U.S. Individual Income Tax Return, detailing exactly what figures changed.
- Mail the paper amendment to the appropriate IRS processing center or submit it electronically if supported by your tax software provider.
What If It Still Doesn’t Work?
If your tax situation remains complex or automated software rejects your fellowship entries, utilize these fallback solutions:
- Visit your university’s student financial services office to see if they provide free student access to specialized tax preparation software like Sprintax or Glacier Tax Prep.
- Locate a nearby IRS Volunteer Income Tax Assistance (VITA) clinic offering free tax help to individuals earning under the annual program limits.
- Hire a Certified Public Accountant (CPA) specializing in higher education tax law. According to the National Society of Accountants, hiring a professional for a standard graduate return generally ranges from $250 to $500.
- Contact the IRS dedicated taxpayer assistance line directly at 1-800-829-1040 to resolve specific reporting discrepancies on fellowship W-2 equivalents.
Conclusion
Navigating graduate student taxes for 2026 successfully comes down to distinguishing between taxable stipends and tax-free fellowships while tracking every deduction. Overlooking these distinctions leads to unnecessary overpayments and compliance notices. According to verified research and expert sources from the National Association of Student Financial Aid Administrators, proactive document organization remains the single most effective defense against filing errors. Take your first actionable step today by logging into your university portal and downloading your Form 1098-T and fellowship distribution records.
❓ Frequently Asked Questions
Why didn’t my university withhold federal taxes from my fellowship check?
Universities are typically not required to withhold federal or state income taxes on fellowship grants used for living expenses. Because of this lack of withholding, fellowship recipients must proactively calculate and pay their income taxes to avoid end-of-year penalties.
How do I know if I need to make quarterly estimated tax payments?
You generally need to make quarterly estimated tax payments (Form 1040-ES) if you expect to owe at least $1,000 in tax when your return is filed and your withholding/refundable credits cover less than the smaller of 90% of your current tax liability or 100% of your prior year tax.
What is the difference between W-2 income and fellowship income for a grad student?
W-2 income comes from working as a Graduate Teaching Assistant (TA) or Graduate Research Assistant (RA) where taxes are automatically withheld. Fellowship income is awarded for study or research without a specific service requirement and usually lacks tax withholding.
Are travel grants and research allowances taxable?
Travel grants and research stipends are generally taxable unless they meet specific IRS accountable plan rules set by your institution or are explicitly designated as tax-free working condition fringe benefits.
Can I deduct my textbook and computer expenses?
You can only deduct books, supplies, and equipment if they are explicitly required for your enrollment or attendance at the educational institution and you are claiming an eligible tax credit like the Lifetime Learning Credit.
How do international graduate students handle US taxes?
International graduate students on F-1 or J-1 visas are generally classified as nonresident aliens for tax purposes during their first five calendar years, requiring them to file Form 1040-NR instead of the standard resident tax forms.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.