Types of Income Tax in USA 2026 A Proven Guide
Navigating the U.S. tax system requires understanding that tax obligations are split across multiple government levels, including federal, state, and local jurisdictions. Taxpayers must also distinguish between ordinary income, capital gains, and payroll taxes to ensure full compliance with the law.
The United States tax system is built on a multi-layered structure where you pay taxes to different levels of government based on various types of earnings. When you navigate the 2026 tax landscape, you encounter three primary categories of income tax: federal, state, and local, each with its own distinct rules, brackets, and collection methods.
Understanding these categories helps you anticipate your total tax liability rather than just focusing on your federal paycheck withholding. By breaking down how ordinary income, capital gains, and geographic levies interact, you can map out your exact financial obligations for the year.
Key Takeaways
- Federal income tax applies to all U.S. citizens and residents based on progressive tax brackets.
- Most states levy their own income tax, though nine states currently have no state income tax.
- Local income taxes are collected by certain cities and counties to fund municipal services.
- Capital gains taxes apply differently to profits from selling assets depending on holding periods.
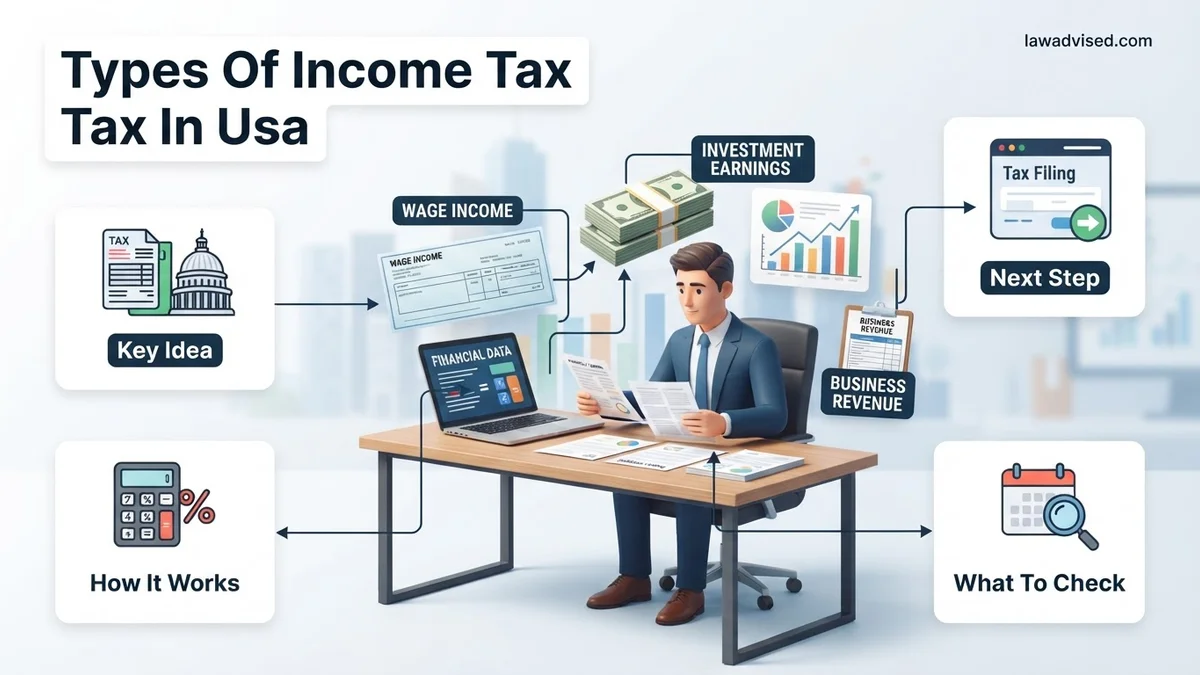
- Ordinary income includes wages, salaries, and tips, while passive income covers investments and rentals.
What Causes Confusion About Types of Income Tax in the USA
Taxpayers often get overwhelmed because they lump every deduction and tax rate into one single bucket. In reality, the U.S. system separates your money into different streams, taxing earned wages differently from investment profits or municipal earnings.
The Trap of Mixing Ordinary Income and Capital Gains
Your salary, wages, and freelance earnings count as ordinary income. They are taxed using progressive marginal brackets. Investment profits, like selling stocks or real estate, fall under capital gains. Capital gains face preferential tax rates of 0%, 15%, or 20% depending on your total taxable income and how long you held the asset.
Misunderstanding Standard Versus Itemized Deductions
- The standard deduction lowers your overall taxable income by a flat, government-set dollar amount based on your filing status.
- Itemized deductions require you to track specific expenses, such as mortgage interest, state and local taxes (SALT) up to statutory limits, and large medical bills.
- You choose whichever option reduces your final tax bill the most, but you cannot use both simultaneously.
How to Fix Your Understanding of Federal, State, and Local Tax Structures
To clear up the confusion, picture your tax liability as a pyramid. Federal income tax forms the massive base, state income tax adds the middle layer, and local taxes form the peak for residents of specific cities or counties.
The Dominance of Federal Income Tax
Federal income tax accounts for the vast majority of what you pay the government. For 2026, the federal system features multiple marginal tax brackets ranging from 10% up to 37%, depending on your filing status. Your employer withholds this directly from your paycheck based on your Form W-4, or you pay it via quarterly estimated payments if you are self-employed.
State and Local Layers
Beyond the federal government, most states levy their own income tax, which can be flat or progressive. However, states like Texas, Florida, and Nevada feature no state income tax at all. Additionally, specific municipalities—such as New York City or certain localities in Ohio and Pennsylvania—impose a local earned income tax, usually taking a small fractional percentage (often under 3%) of your wages to fund local public services.
Step-by-Step Guide to Identifying Your Specific Tax Obligations
Navigating the complex landscape of U.S. taxation requires a structured approach. By breaking down your financial profile, you can accurately determine which types of income tax apply to your situation for the 2026 tax year.
Step 1: Audit Your Income Sources
- List all streams of revenue earned throughout the calendar year, including W-2 wages, freelance client payments, and investment dividends.
- Determine if you earned income in multiple states, which triggers multi-state tax filing requirements.
- Calculate your passive gains from real estate or stock sales to account for capital gains tax exposure.
Step 2: Evaluate Your Residency and Location
- Verify your federal residency status, as U.S. citizens and resident aliens are taxed on worldwide income by the IRS.
- Check the local state and municipal tax codes for the specific cities and counties where you lived or worked.
- Consult the latest 2026 state tax brackets to see if your permanent domicile levies a flat income tax, progressive tax, or no income tax at all.
What If It Still Doesn’t Work and You Need Professional Tax Help?
When automated software or DIY calculations leave you uncertain about your total tax liabilities, bringing in a licensed professional is the safest recourse. According to National Society of Accountants data, taxpayers often save more money in avoided penalties and optimized deductions than the cost of hiring an expert.
If you encounter persistent discrepancies or complex multi-state filing issues, execute these fallback steps:
- Gather all prior-year tax returns, 1099s, W-2s, and receipts for business or itemized deductions into a secure digital folder.
- Search for a Certified Public Accountant (CPA) or Enrolled Agent (EA) specializing in individual or small-business taxation.
- Schedule an initial consultation to review your specific tax obligations for the 2026 filing season; expect standard consultation rates to range from $150 to $350 per hour.
- Engage the professional to file amended returns or handle correspondence if you have received notices regarding unpaid state or federal obligations.
Conclusion
Understanding the diverse types of income tax in the USA is essential for maintaining compliance and minimizing your legal tax burden. By properly categorizing federal, state, local, and capital gains liabilities, you protect your financial assets from unexpected penalties. According to verified research and expert sources from the IRS and leading financial institutions, proactive planning remains the single most effective strategy for tax season. Take your next actionable step today by reviewing your latest paystubs and income statements to map out your exact 2026 tax obligations.
❓ Frequently Asked Questions
What is the difference between ordinary income tax and capital gains tax?
Ordinary income tax applies to money earned from working, such as wages, salaries, and tips, taxed at standard marginal rates. Capital gains tax applies to profits realized from selling assets like stocks or real estate, often benefiting from lower tax rates if held long-term.
Which states do not have a state income tax?
States such as Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington, and Wyoming do not levy a traditional state income tax on wage earnings. New Hampshire historically taxed investment income, but that tax has been phased out.
How do local income taxes work in the United States?
Local income taxes, also known as payroll or earnings taxes, are levied by specific cities, counties, or school districts. These taxes are typically a small percentage of earned income and are common in states like Ohio, Pennsylvania, and New York.
What is the difference between a progressive, flat, and regressive tax?
A progressive tax increases the tax rate as income rises, which is how the federal income tax system functions. A flat tax applies the exact same tax rate to all income levels regardless of earnings, while a regressive tax takes a larger percentage of income from low-earning individuals.
Are payroll taxes considered income taxes?
No, payroll taxes—such as FICA taxes for Social Security and Medicare—are distinct from federal and state income taxes. They are automatically withheld from paychecks specifically to fund federal insurance programs rather than general government operations.
How are independent contractors taxed differently on their income?
Independent contractors and freelancers must pay self-employment tax in addition to standard income taxes. This covers both the employer and employee portions of Social Security and Medicare contributions.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.