Capital Gains Tax Explained Step-by-Step Guide for 2026
Capital gains tax is a levy on the profit you make when selling an asset like stocks, real estate, or crypto. Understanding how this tax works helps you distinguish between short-term and long-term rates so you can keep more of your hard-earned investment returns.
Capital gains tax is the levy you pay on the profit you make when selling an asset like stocks, real estate, or crypto for more than you originally paid for it. It is not charged on the total amount of money you receive from a sale—only on your actual net profit. How much you owe depends heavily on how long you owned the asset before selling.
As you navigate your investments in 2026, understanding these rules keeps you from getting hit with unexpected tax bills. Knowing how the system works allows you to time your sales strategically, leverage holding periods, and keep more of your hard-earned profits.
Key Takeaways
- Capital gains apply only when you sell an asset for a profit.
- Short-term gains are taxed at ordinary income tax rates.
- Long-term gains benefit from lower tax rates of 0%, 15%, or 20%.
- Your cost basis determines your exact net profit for tax purposes.
- Homeowners can exclude up to $250,000 of profit on a primary residence.
What Causes Capital Gains Tax Liabilities When Selling Assets
Recognizing Taxable Events
You trigger a capital gains tax liability the moment you execute a profitable sale of a capital asset. Simply watching your investments grow in value does not create a tax bill. Your gains remain unrealized until you actually sell the asset, exchange it, or convert it into cash.
- Selling stocks or mutual funds in a taxable brokerage account
- Cashing out cryptocurrency or swapping one token for another
- Selling a physical property that does not qualify for a primary residence exclusion
- Disposing of valuable collectibles like art, gold, or vintage cars
Short-Term Versus Long-Term Triggers
The IRS categorizes your gains based on your holding period, which directly impacts the tax rate you face. The holding period starts the day after you acquire the asset and ends on the day you sell it. Crossing the one-year threshold is the most important factor in minimizing your tax burden.
- Short-Term Gains: Assets held for one year or less are taxed at ordinary income tax rates, which can reach up to 37 percent depending on your tax bracket.
- Long-Term Gains: Assets held for longer than one year qualify for preferential tax rates of 0 percent, 15 percent, or 20 percent for most taxpayers.
Step-by-Step Guide to Calculating Your Capital Gains and Cost Basis
Determining Your Cost Basis
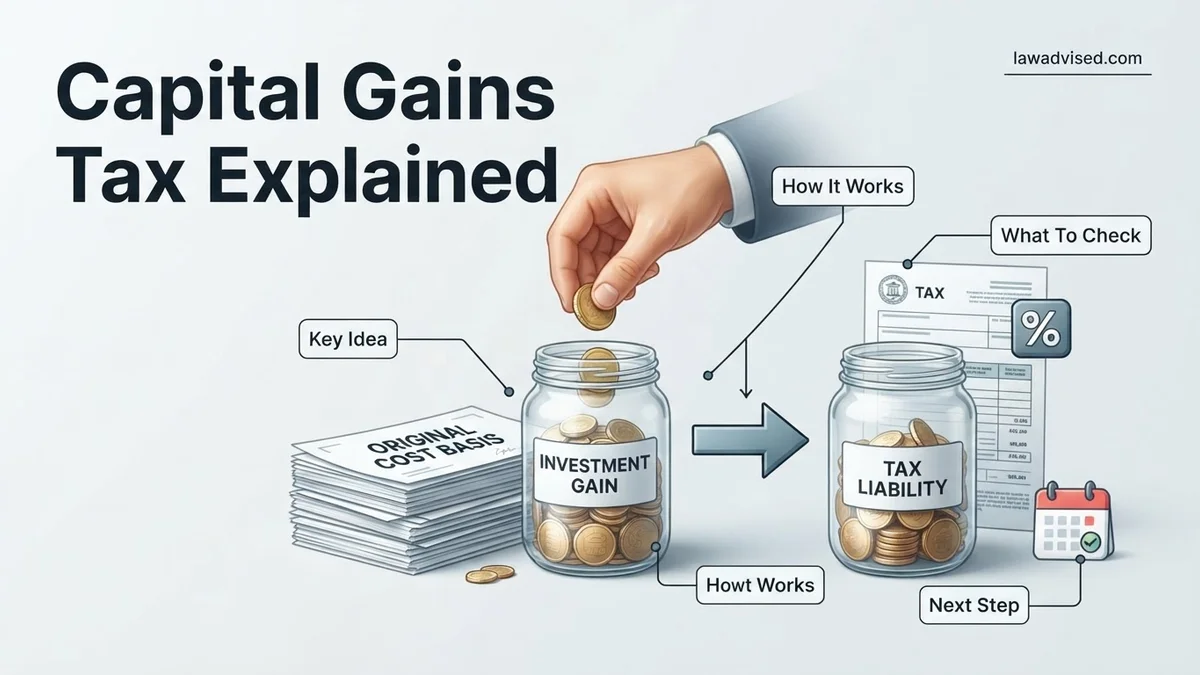
Your cost basis is the total financial investment you made in the asset, which serves as the baseline for calculating your profit. Getting this number right is vital because an accurate basis prevents you from overpaying taxes. You must include purchase prices, broker commissions, and certain improvement costs.
- Purchase Price: The actual amount you paid to acquire the asset.
- Transaction Fees: Commissions, broker fees, and legal costs paid during the purchase.
- Adjustments: Capital improvements made to real estate that increase the property’s overall value.
Calculating Net Profit and Final Tax Owed
Once you establish your cost basis, calculating your net capital gain requires a straightforward mathematical formula. You subtract your total cost basis and any allowable selling expenses from your final sale price. This final figure represents your net taxable profit for that specific transaction.
- Take your total sale proceeds (e.g., $10,000 from selling stock).
- Subtract your cost basis and selling fees (e.g., $4,000 purchase price plus $50 commission).
- Arrive at your net capital gain (e.g., $5,950 in taxable profit).
- Apply the applicable 2026 tax rate based on your income bracket and holding period to find your tax due.
Proven Strategies to Minimize, Exclude, or Defer Capital Gains Tax Legally
Minimizing your tax liability requires proactive planning before you trigger a sale. According to financial experts and IRS guidelines for 2026, several legal mechanisms exist to reduce or completely eliminate your capital gains burden.
Utilizing the Primary Residence Exclusion
Homeowners can exclude up to $250,000 of capital gains from their income if filing as single, or up to $500,000 if married filing jointly. To qualify, you must meet the ownership and use tests.
- Verify you owned the home for at least two out of the five years leading up to the sale date.
- Confirm you lived in the property as your primary residence for at least two out of those same five years.
- Ensure you have not claimed this specific exclusion on the sale of another home within the past 24 months.
Leveraging Tax-Advantaged Accounts and Exchanges
Retirement accounts such as traditional IRAs, Roth IRAs, and 401(k) plans allow assets to grow tax-deferred or entirely tax-free. For real estate investors, executing a Section 1031 exchange defers capital gains taxes indefinitely by reinvesting proceeds into a like-kind property.
What If Your Capital Losses Offset Your Gains and Lower Your Bill
Investment losses can work to your financial advantage by offsetting realized capital gains. According to IRS tax codes, capital losses must first be used to offset capital gains of the same type, such as short-term losses offsetting short-term gains.
Applying the Loss Offset Hierarchy
When your losses exceed your gains, you can reduce your ordinary taxable income. Strategic tax planning requires a systematic approach to loss harvesting.
- Calculate your total short-term and long-term capital gains for the 2026 tax year.
- Subtract your corresponding capital losses from those gains to determine your net capital gain or loss.
- Apply up to $3,000 of remaining net capital losses against your ordinary income if filing jointly or single ($1,500 if married filing separately).
- Carry forward any leftover losses indefinitely into future tax years until the balance is fully depleted.
What If It Still Doesn’t Work?
Complex investment portfolios and high-value asset sales can easily result in unexpected tax liabilities that standard software fails to resolve. If self-managed strategies fall short, consider these fallback steps.
- Review your transaction history to ensure cost basis tracking is accurate, as omitted reinvested dividends frequently inflate reported gains.
- Gather all documentation regarding home improvements or asset enhancements that increase your adjusted cost basis.
- Consult a Certified Public Accountant (CPA) or a certified financial planner specializing in tax mitigation strategies. Professional tax advisory fees typically range from $300 to $1,000 depending on the complexity of your asset portfolio.
- File for an IRS tax extension if you require additional time to accurately calculate complex capital gains and losses.
Conclusion
Navigating capital gains tax in 2026 demands a clear understanding of holding periods, loss-harvesting rules, and available legal exclusions. By systematically offsetting losses and leveraging primary residence exemptions, you can significantly reduce your overall tax burden. According to verified research and expert financial sources, proactive year-round tax planning remains the single most effective method for preserving investment returns. Your actionable next step is to audit your current portfolio and calculate your year-to-date realized gains before the end of the fiscal quarter.
❓ Frequently Asked Questions
What are the current long-term capital gains tax brackets?
Long-term capital gains are taxed at rates of 0%, 15%, or 20%, depending entirely on your taxable income and filing status for the year.
Do I have to pay capital gains tax if I do not withdraw the money from my brokerage account?
No, capital gains are only triggered when you actually sell or dispose of an asset. Simply watching your investments grow in value does not create a taxable event.
How do capital losses affect my taxes?
Capital losses can be used to offset your capital gains dollar-for-dollar. If your losses exceed your gains, you can deduct up to $3,000 of ordinary income per year.
Are cryptocurrency transactions subject to capital gains tax?
Yes, the IRS treats cryptocurrency as property, meaning selling crypto for fiat currency, trading one token for another, or using it to buy goods triggers a capital gain or loss.
What is the Net Investment Income Tax (NIIT)?
The NIIT is an additional 3.8% tax levied on investment income for high-income earners whose modified adjusted gross income exceeds specific statutory thresholds.
How can tax-advantaged accounts help avoid capital gains tax?
Accounts like IRAs, 401(k)s, and HSAs allow investments to grow and be sold inside the account without triggering immediate capital gains tax consequences.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.