Annualized Income Installment Method Explained 2026 Guide
The annualized income installment method allows taxpayers with fluctuating or seasonal earnings to calculate quarterly estimated taxes accurately based on when income was actually earned. By using IRS Form 2210 Schedule AI, you can lower or eliminate underpayment penalties by matching required payments to your real-world cash flow.
The annualized income installment method lets you calculate your quarterly estimated tax payments based on what you actually earned during specific months of the year, rather than assuming your income arrived evenly. By using IRS Form 2210 Schedule AI, you can legally lower or eliminate underpayment penalties if your earnings fluctuate throughout 2026.
This strategy matters practically because the standard IRS safe harbor rules assume you make the same amount of money in January as you do in July. If your cash flow spikes late in the year or arrives in unpredictable waves, paying standard quarterly installments forces you to tie up capital unnecessarily or trigger steep IRS penalties.
Key Takeaways
- Annualize income by period to match actual earnings.
- Use IRS Form 2210 Schedule AI to calculate penalties.
- Ideal for freelancers, seasonal businesses, and investors.
- Prevents overpaying taxes in early quarters.
- Requires meticulous bookkeeping for exact income dates.
Why Traditional Quarterly Tax Payments Fail Lumpy Earners
The Flaw in the Standard Safe Harbor Approach
The IRS normally expects you to pay estimated taxes in four equal installments based on the previous year’s liability or 90 percent of your current-year tax. If you use the current-year method, the government divides your expected tax evenly across all four quarters. This creates a cash flow trap for anyone whose income does not arrive in neat, predictable monthly increments.
Real-World Scenarios That Benefit From Annualization
If your income is front-loaded, back-loaded, or completely seasonal, the traditional method works against you. This calculation method is essential for specific financial profiles:
- Freelancers and consultants who land massive enterprise contracts late in the year
- Seasonal businesses like landscaping companies or holiday retailers
- Real estate agents and independent brokers with closing-dependent income
- Investors and traders experiencing heavy capital gains in specific quarters of 2026
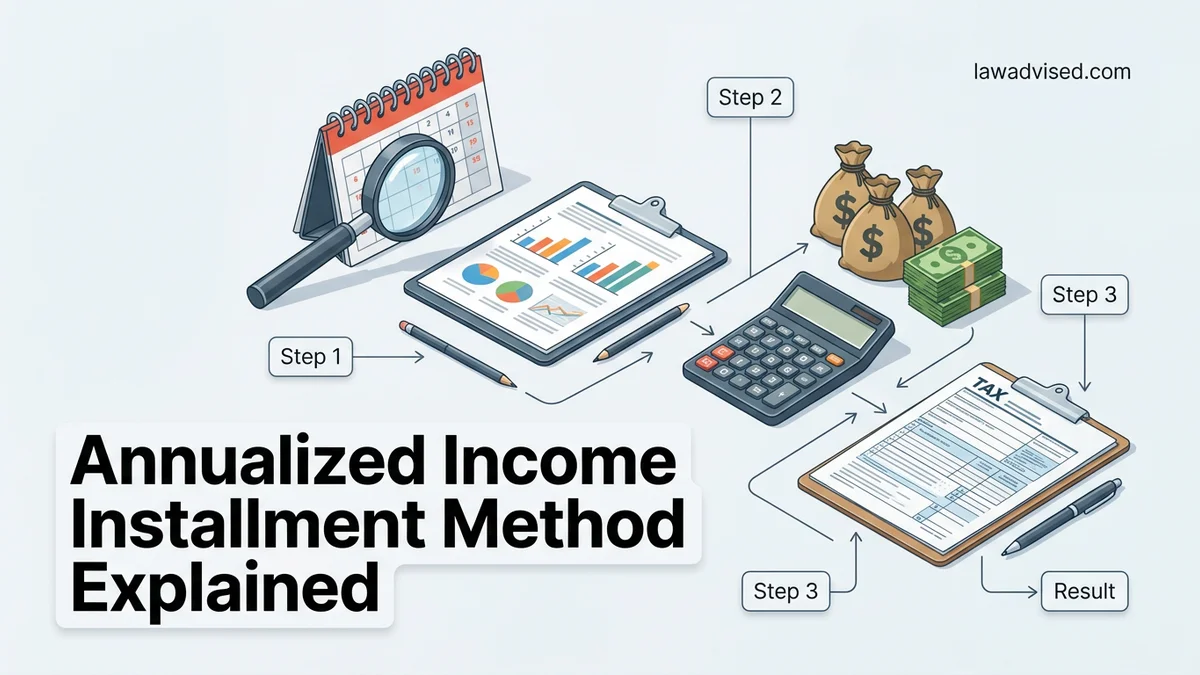
Master the Annualized Income Installment Method in 8 Simple Steps
Navigating estimated quarterly tax payments can be stressful, especially when your income fluctuates throughout the year. If you experience seasonal slumps, massive year-end bonuses, or irregular freelance contracts, paying equal quarterly installments might result in severe overpayments or underpayment penalties. This comprehensive walkthrough explains how to accurately calculate your quarterly obligations using the annualized income installment method, empowering you to keep more of your hard-earned cash in your pocket until it is actually due.
Step 1: Understand the Core Concept and Qualification Criteria
What you need: Access to prior year tax returns, current year profit and loss statements, and IRS Form 2210 instructions.
Instructions: Before diving into complex math, verify that your income is genuinely uneven throughout the year. The annualized income installment method allows you to base your estimated tax payments on the actual income you earned during specific periods, rather than assuming your income is evenly distributed. This method is exceptionally beneficial for seasonal businesses, commissioned sales professionals, and freelancers whose busiest months fall late in the calendar year. By matching your payments to your actual cash flow, you legally defer large tax outlays until the income is actually realized.
Pro Tip: Do not use this method if your income is steady month-to-month, as it introduces unnecessary paperwork and strict record-keeping requirements without providing financial benefits.
Step 2: Determine the Four Specific Annualization Periods
What you need: A calendar or spreadsheet, financial tracking software, and IRS Schedule AI (found in Form 2210).
Instructions: The IRS divides the year into distinct, cumulative periods for this calculation. You must look at your income from January 1 through the end of each specific period. Period 1 covers January 1 to March 31 (3 months). Period 2 covers January 1 to May 31 (5 months). Period 3 covers January 1 to August 31 (8 months). Period 4 covers the entire year, January 1 to December 31 (12 months). Gather your gross receipts, deductible business expenses, and personal deductions for each of these exact cutoff dates.
Pro Tip: Be meticulous with your cutoff dates. Invoices sent on April 1st belong in the second period, not the first, even if the client pays retroactively.
Step 3: Calculate Your Net Income for Each Period
What you need: Detailed income statements, receipts for business expenses, and a calculator or spreadsheet.
Instructions: For each of the four periods identified in the previous step, calculate your total adjusted gross income or net self-employment earnings. Sum up all revenue received during that specific timeframe and subtract all ordinary and necessary business expenses incurred during that exact same window. For example, in Period 2, you will calculate your total profit from January 1 through May 31. Keep these four distinct profit figures clearly labeled in your workspace, as you will use them independently for the subsequent mathematical scaling.
Pro Tip: Accrual-basis taxpayers must be careful with accounts receivable, while cash-basis taxpayers should focus strictly on cash actually deposited during each window.
Step 4: Annualize the Period Income Figures
What you need: IRS multiplication factors (4 for Period 1, 2.4 for Period 2, 1.5 for Period 3, and 1 for Period 4).
Instructions: Now, you must convert your cumulative period income into an annualized projection. Multiply your net income figure from Period 1 by 4 (since 3 months times 4 equals 12 months). Multiply your Period 2 net income by 2.4 (12 divided by 5). Multiply your Period 3 net income by 1.5 (12 divided by 8). Finally, multiply your Period 4 net income by 1 (since you already have the full year’s data). These resulting numbers represent what your total annual income would be if you continued earning at the exact pace you maintained during each respective period.
Step 5: Compute the Tax Liability for Each Annualized Amount
What you need: Current year federal and state income tax brackets, self-employment tax calculation worksheets, and deduction limits.
Instructions: Take each of the four annualized income figures you calculated in Step 4 and run them through the standard tax formulas. Subtract your estimated itemized or standard deductions to find the annualized taxable income for each period. Then, calculate the regular income tax and self-employment tax owed on those annualized amounts. This gives you four different projected annual tax liabilities. Remember to factor in any tax credits you expect to claim, as these will directly reduce the gross tax liability for each period.
Pro Tip: Tax brackets change annually, so ensure you are referencing the official IRS tax tables for the exact tax year you are filing for.
Step 6: Apply the Applicable Installment Percentage
What you need: IRS Schedule AI worksheet lines and a clear understanding of quarterly percentages (25%, 50%, 75%, and 100%).
Instructions: You cannot simply pay the full annualized tax for every quarter. You must multiply the tax liability calculated in Step 5 by the specific percentage mandated by the IRS for each payment window. For Period 1, multiply the annualized tax by 25% (or 0.25). For Period 2, multiply by 50% (0.50). For Period 3, multiply by 75% (0.75). For Period 4, multiply by 100% (1.00). This step scales the annualized projection down to the cumulative tax portion that should have been paid by the conclusion of each respective quarterly deadline.
Step 7: Subtract Prior Payments and Apply the “Smallest Rule”
What you need: Records of previous estimated tax payments made for the current year and standard required installment amounts.
Instructions: For each quarter, subtract the estimated taxes you have already paid in previous quarters of the current year from the cumulative amount calculated in Step 6. Furthermore, the IRS requires you to compare your annualized installment amount against your regular required installment (usually 25% of last year’s tax or 90% of this year’s current tax). For any given quarter, you are allowed to pay the smaller of the two amounts. If your annualized method yields a lower payment due to a seasonal dip, you can safely pay that lower amount and avoid penalty.
Pro Tip: If you use the annualized method, you must attach IRS Form 2210 to your final tax return to prove to the IRS why your quarterly payments fluctuated.
Step 8: File Form 2210 and Submit Your Payments on Schedule
What you need: Completed IRS Form 2210 (specifically Schedule AI), IRS payment portal access (EFTPS or IRS Direct Pay), and your tax software or accountant.
Instructions: With your customized quarterly installment amounts calculated, make your payments by the standard IRS quarterly deadlines (typically April 15, June 15, September 15, and January 15 of the following year). Keep detailed records of every calculation sheet and payment confirmation receipt. When tax season arrives, complete IRS Form 2210, checking the box indicating that you are using the annualized income installment method, and include Schedule AI with your tax submission to waive any potential underpayment penalties.
Pro Tip: Double-check your arithmetic on Schedule AI. A minor math error on an early quarter calculation can cascade and distort your subsequent quarterly payments.
✅ Final Checklist
- Verified that your income distribution is genuinely uneven or seasonal throughout the year.
- Accurately gathered financial statements for all four specific cumulative periods (3, 5, 8, and 12 months).
- Applied the correct IRS multiplication factors (4, 2.4, 1.5, and 1) to annualize period earnings.
- Subtracted prior tax payments and correctly utilized the “smallest rule” to optimize cash flow.
- Completed and attached IRS Form 2210 along with Schedule AI to your annual tax return.
Important Notes:
- Tax laws are complex; relying solely on self-calculation without basic accounting knowledge can lead to IRS underpayment penalties.
- Consider seeking professional help from a Certified Public Accountant (CPA) or Enrolled Agent (EA) if your business structure involves partnerships, S-corporations, or multi-state taxation.
- Estimated time to complete calculations: 2 to 4 hours per tax year; Professional service cost range: $300 to $800 if outsourced to a tax professional.
How to Calculate Estimated Taxes Using the Annualized Method
Step 1: Determine Your Actual Income Periods
To use Schedule AI for your 2026 taxes, you must break the year down into four specific cumulative periods. You will calculate your net income from the start of the year up to the end of each respective span:
- Period 1: January 1 to March 31
- Period 2: January 1 to May 31
- Period 3: January 1 to August 31
- Period 4: January 1 to December 31
Step 2: Annualize Your Income and Apply Tax Rates
Once you have your actual earnings for each period, you scale that number up to an annual figure by multiplying it by an annualization factor. For instance, you multiply your three-month income for Period 1 by 4. You then calculate the tax on that annualized amount, multiply it back down by the period’s specific percentage, and subtract any estimated taxes you already paid for earlier quarters.
Step-by-Step Guide to Filing IRS Form 2210 Schedule AI
Filing IRS Form 2210, specifically Schedule AI (Annualized Income Installment Method), requires precise bookkeeping and strict adherence to IRS guidelines. Taxpayers must calculate their income and deductions for four specific periods during the 2026 tax year. According to the IRS Instructions for Form 2210, missing a single column or miscalculating a period can trigger an automated balance due notice.
Filing Procedures
- Gather Period-End Financials: Compile accurate profit and loss statements, investment income records, and expense receipts for each of the four designated 2026 periods.
- Complete Part I of Form 2210: Determine if you actually owe a penalty and verify that you meet the criteria to use the annualized income method.
- Fill Out Schedule AI (Parts I and II): Enter your actual income and deductions for the specific periods into the respective columns, following the annualized factors provided by the IRS.
- Transfer Results to Part III: Carry the final calculated installment amounts from Schedule AI over to Form 2210, Part III, line 19, to establish your reduced or eliminated penalty.
- Attach to Your Return: File the completed Form 2210 and Schedule AI alongside your 2026 federal income tax return, whether filing electronically or via mail.
What to Do If Your Income Fluctuates Wildly Across Periods
Extreme income volatility can make the annualized method feel mathematically overwhelming. When business deals close in December or seasonal revenue spikes occur late in the year, tracking periods requires extreme precision. Financial analysts emphasize that accurate sub-period accounting prevents the IRS from disallowing your calculated installment reductions.
Management Strategies
- Implement Accrual Accounting Adjustments: Ensure your bookkeeping accurately reflects expenses in the exact period they were incurred, matching them to erratic revenue streams.
- Re-run Calculations Quarterly: Do not wait until tax season to compile your data. Re-calculate your annualized income immediately after each quarterly payment deadline passes in 2026.
- Consult a Certified Public Accountant: If your fluctuating income involves complex capital gains or multi-state taxation, professional oversight is essential to avoid costly filing errors.
What If It Still Doesn’t Work?
If manual calculations on Schedule AI yield confusing results or your tax software rejects your entries, specialized intervention is required. According to National Association of Tax Professionals (NATP) data, complex underpayment penalty disputes often require external resources. Consider these fallback steps if your self-filing attempt fails:
- Switch to Advanced Tax Software: Upgrade from basic consumer tax applications to professional-grade software that includes automated Schedule AI logic modules.
- Request a Penalty Abatement: If your underpayment stemmed from an unexpected disaster, casualty, or severe hardship, file a formal penalty waiver request with the IRS.
- Hire a Licensed Tax Professional: Engage a CPA or Enrolled Agent to review your bookkeeping and formally file the adjustment on your behalf. Professional fees for Form 2210 resolution generally range from $300 to $850 depending on return complexity.
Conclusion
The annualized income installment method provides a vital financial shield for 2026 taxpayers facing uneven cash flow, preventing unnecessary penalties on mismatched earnings. By meticulously calculating your income across specific seasonal periods and filing IRS Form 2210 Schedule AI correctly, you can legally align your tax payments with your actual financial reality. According to verified research and expert tax sources, taking a proactive, quarterly approach to your estimated payments remains the most effective defense against IRS underpayment assessments. Make your next step a complete review of your year-to-date financial statements to prepare for the upcoming filing deadline.
❓ Frequently Asked Questions
How do the standard estimated tax method and the annualized method differ?
The standard method assumes you earn your income evenly throughout the entire year, dividing your total tax liability into four equal parts. The annualized method recalculates your tax liability for every single payment period based on year-to-date actual earnings.
What are the specific date ranges used for annualizing income?
The standard IRS periods for individuals are typically the first 3 months, the first 5 months, the first 8 months, and the entire 12-month calendar year, depending on the specific payment due dates.
Can I use the annualized method for just one quarter and the standard method for others?
Yes, you can use the annualized income installment method for any period where it results in a lower required payment, applying it selectively to quarters with lower income.
What happens if I calculate my annualized installments incorrectly?
If your calculations result in an underpayment for a specific period, the IRS may assess underpayment interest and penalties for that specific quarterly shortfall.
Do I need to attach Form 2210 to my tax return if I use this method?
Yes, you must complete and attach Form 2210 with Schedule AI filled out to your tax return if you are claiming a lower penalty or requesting a waiver using this method.
How does seasonality affect the math on Schedule AI?
Seasonality means your early-year periods will show very low income and tax liability, resulting in zero or very low required installment payments for Q1 and Q2, while later quarters scale up automatically.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.