Net Investment Income Tax Explained A Step-by-Step 2026
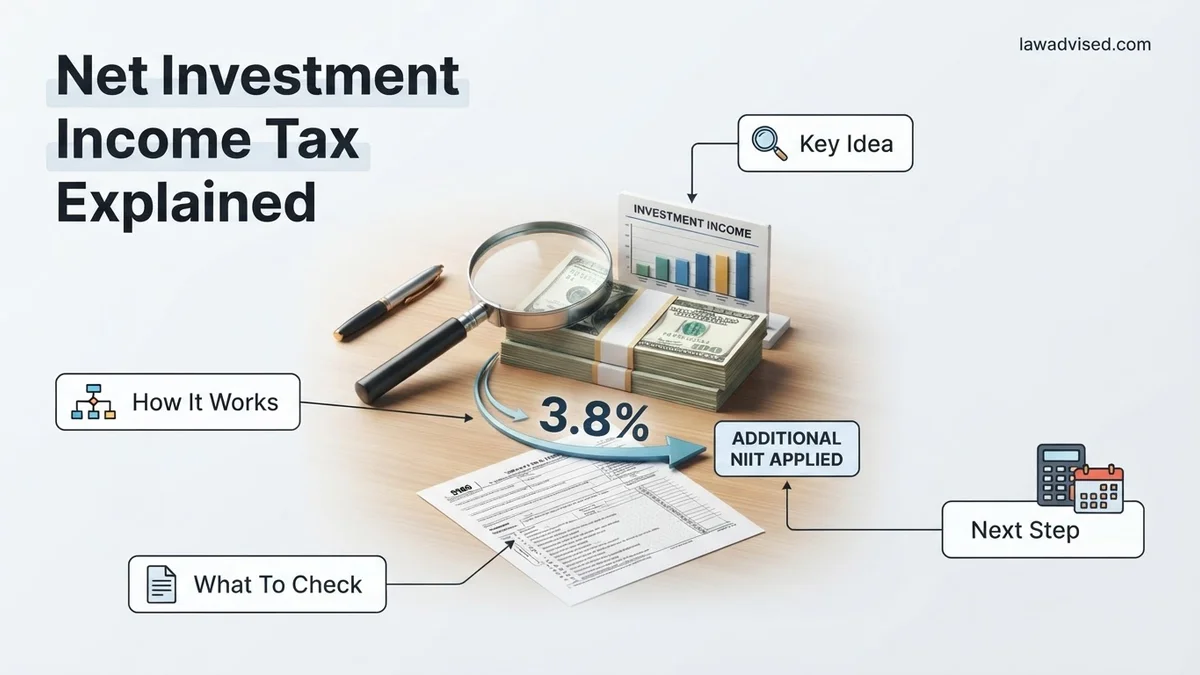
The Net Investment Income Tax (NIIT) is a 3.8% surtax levied on certain investment income for high-income earners. Understanding your modified adjusted gross income (MAGI) thresholds is essential to determining if you are required to pay this additional tax.
The Net Investment Income Tax (NIIT) is a 3.8% surtax levied on certain investment income for individuals, estates, and trusts whose modified adjusted gross income (MAGI) exceeds specific statutory thresholds. Introduced as part of the Affordable Care Act, this tax targets high-income earners who generate substantial passive returns from their assets.
Understanding how this tax applies to your specific financial situation in 2026 is crucial for preventing unexpected tax bills. If your investment portfolio, real estate ventures, or business interests produce significant passive cash flow, you need to know exactly when this 3.8% charge kicks in and how to calculate your potential exposure.
Key Takeaways
- The NIIT adds a 3.8% tax on investment income above specific MAGI thresholds.
- Single filers face the tax if their MAGI exceeds $200,000.
- Married couples filing jointly trigger the tax at a $250,000 threshold.
- Capital gains, dividends, rental income, and interest are fully subject to NIIT.
- W-2 wages, active business income, and traditional IRA distributions are exempt.
What Causes Net Investment Income Tax Liability
The MAGI Thresholds That Trigger the Tax
The NIIT does not apply to every taxpayer. Your liability depends entirely on your Modified Adjusted Gross Income (MAGI) and your IRS filing status. These thresholds remain fixed and are not indexed for inflation, meaning more taxpayers cross them each year as incomes rise.
- Married Filing Jointly: $250,000
- Single or Head of Household: $200,000
- Married Filing Separately: $125,000
- Qualifying Widow(er) with Dependent Child: $250,000
What Income Counts Toward the NIIT
Once your MAGI exceeds your applicable threshold, the 3.8% tax applies to the lesser of your net investment income or the amount by which your MAGI exceeds the threshold. Investment income is broad and captures multiple asset classes.
- Taxable interest, dividends, capital gains (from stock sales or real estate), and rental and royalty income.
- Income from passive business activities and trading in financial commodities or instruments.
- Distributions from certain non-retirement investment accounts.
Crucially, traditional retirement distributions from 401(k) plans or IRAs are excluded from net investment income, though they do count toward your overall MAGI calculation.
How to Calculate Your Net Investment Income Tax Step-by-Step
Step 1: Determine Your Modified Adjusted Gross Income
Your first calculation requires finding your 2026 MAGI. For most taxpayers, MAGI is your standard Adjusted Gross Income (AGI) with minor adjustments, usually involving foreign earned income exclusions. If your MAGI sits below your filing status threshold, you owe zero NIIT, regardless of how much investment income you generated.
Suppose you file as single and your 2026 MAGI is $230,000. Because this exceeds the $200,000 threshold by $30,000, you have met the primary condition to trigger the tax.
Step 2: Calculate Your Net Investment Income
Next, you must isolate your total gross investment income and subtract any properly allocated deductions. Allowable deductions include investment advisory fees, fiduciary expenses, and state and local income taxes properly allocated to that investment income.
- Add up all your taxable dividends, capital gains, and rental income.
- Subtract the direct expenses incurred to generate that specific income.
- The resulting figure is your Net Investment Income (NII). Imagine your NII totals $40,000.
Step 3: Apply the 3.8% Rate to the Final Amount
The final tax liability is based on the smaller of two figures: your total Net Investment Income, or the excess of your MAGI over the statutory threshold.
- Your excess MAGI: $30,000 ($230,000 MAGI minus the $200,000 single threshold).
- Your Net Investment Income: $40,000.
- The smaller amount is $30,000.
You multiply that $30,000 figure by the 3.8% tax rate, resulting in an additional NIIT liability of $1,140 to report on your federal tax return.
How to Fix or Minimize Your Exposure to the NIIT
Minimizing the Net Investment Income Tax requires proactive tax planning well before the end of the 2026 tax year. Because the 3.8 percent levy applies to the lesser of your net investment income or the amount by which your modified adjusted gross income exceeds statutory thresholds, reducing either metric is critical. Tax professionals recommend specific strategies to keep your MAGI below the threshold or lower your total investment income.
1. Utilize Tax-Advantaged Accounts
Maximizing contributions to traditional IRAs, 401(k)s, and health savings accounts directly reduces your adjusted gross income. Lowering your overall income can pull your MAGI below the 2026 statutory thresholds, entirely eliminating your NIIT liability.
2. Manage Capital Gains and Losses
Strategic tax-loss harvesting allows you to offset capital gains with capital losses. By selling underperforming assets at a loss, you reduce your net investment income calculation for the year. This directly decreases the base upon which the 3.8 percent tax is calculated.
3. Invest in Municipal Bonds
Interest earned from municipal bonds issued by state and local governments is generally exempt from federal income taxes. Furthermore, this interest is excluded from your net investment income calculation, making munis an attractive vehicle for high earners seeking tax-free yield.
What If Your Income Fluctuates Around the Thresholds?
Income volatility can trigger the NIIT in unpredictable ways, especially if you experience a sudden liquidity event like selling a business or commercial real estate. If standard tax reduction strategies fail to keep you under the statutory limits, consider these advanced financial steps:
- Implement installment sales to spread capital gains across multiple tax years, preventing a single-year spike in MAGI.
- Consult a certified public accountant or a certified financial planner specializing in high-net-worth tax strategies; professional advisory fees typically range from $2,000 to $5,000 annually depending on complexity.
- Engage in formal income-shifting strategies, such as establishing charitable remainder trusts to defer recognition of taxable gains.
- Review your quarterly estimated tax payments with a qualified tax preparer to avoid underpayment penalties if your investment income fluctuates drastically during the 2026 tax period.
Conclusion
Navigating the Net Investment Income Tax demands constant vigilance regarding your modified adjusted gross income and investment yields. By utilizing tax-advantaged accounts, harvesting losses, and timing capital realizations carefully, you can successfully shield a substantial portion of your wealth. According to verified research and expert sources from leading financial advisory firms, proactive multi-year tax planning remains the single most effective defense against the 3.8 percent levy. Schedule a comprehensive portfolio and tax review with a licensed financial professional today to optimize your 2026 tax strategy.
❓ Frequently Asked Questions
What are the exact MAGI thresholds for the Net Investment Income Tax?
The thresholds depend on your filing status: $250,000 for married filing jointly, $200,000 for single filers and heads of household, and $125,000 for married individuals filing separately. These thresholds are not indexed for inflation.
Is the sale of a primary residence subject to the NIIT?
Capital gains from selling a primary home are generally excluded from NIIT up to the standard Section 121 exclusion limits ($250,000 for single and $500,000 for married joint filers). Only gains exceeding these limits that qualify for taxable capital gains are subject to the surtax.
Are municipal bond interest payments subject to NIIT?
No, tax-exempt interest from municipal bonds remains exempt from federal income tax and is similarly excluded from the calculation of net investment income.
How does passive versus active business income affect the NIIT?
Income from a trade or business in which you do not materially participate is considered passive and is subject to the NIIT. Conversely, income from a business where you actively or materially participate is exempt.
Can investment expenses reduce my net investment income?
Yes, certain expenses that are directly allocable to investment income—such as investment advisory fees, custodial fees, and investment interest expenses—can be deducted to lower your net investment income figure.
Do traditional IRA or 401(k) withdrawals trigger the NIIT?
Distributions from traditional employer-sponsored plans and traditional IRAs are generally not included in net investment income, though they do count toward your overall modified adjusted gross income for threshold purposes.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.