What Crypto Transactions Are Not Taxable Expert Guide 2026
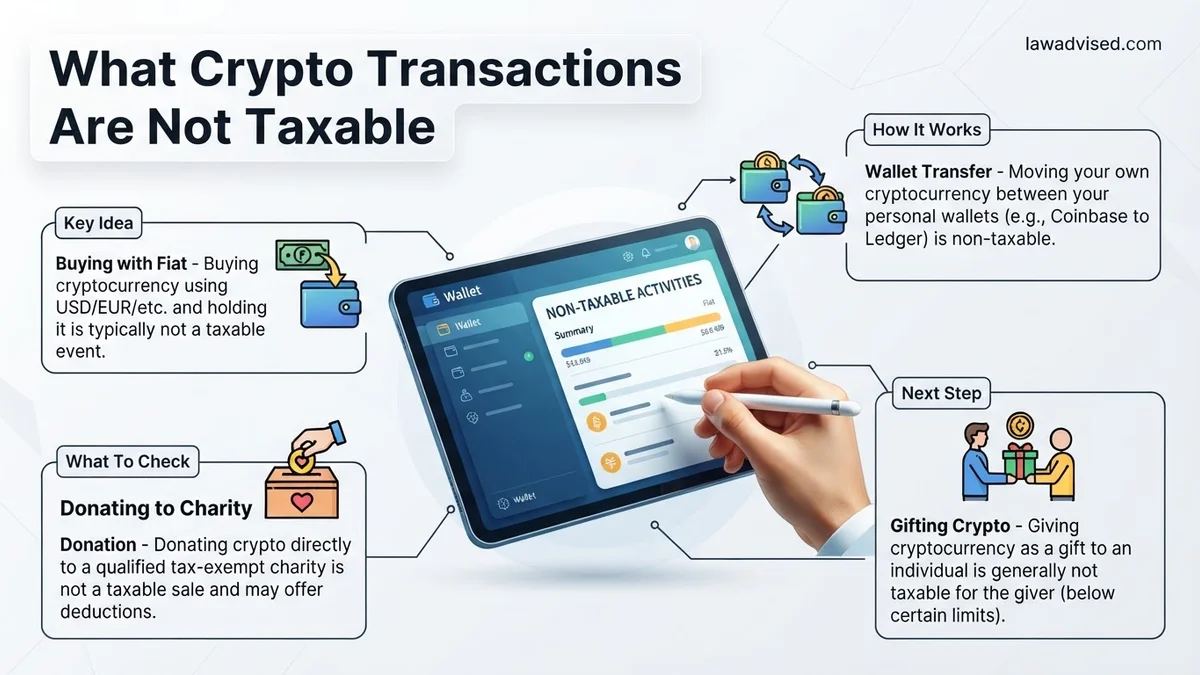
Not every movement of digital assets triggers a tax liability under current IRS guidelines. Purchasing crypto with fiat currency, transferring between personal wallets, and certain gifts or donations do not count as taxable events. Knowing these exceptions prevents you from overpaying on your annual tax return.
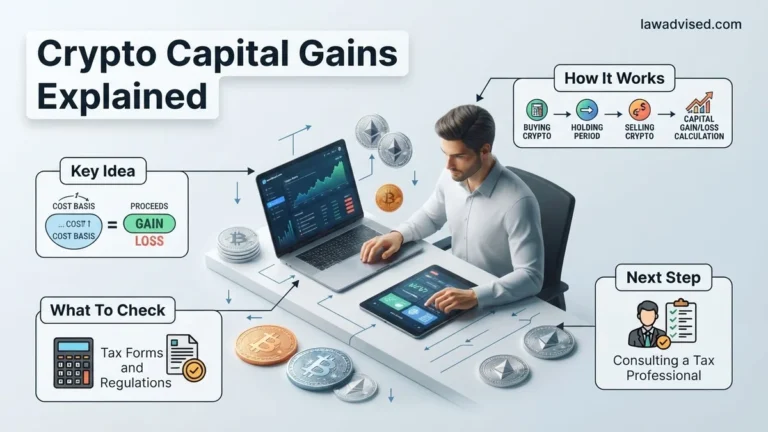
Moving cryptocurrency between your own wallets, buying crypto with cash, and making qualifying gifts or charitable donations do not trigger a taxable event. Under tax guidelines for 2026, the IRS treats cryptocurrency as property rather than currency. This means standard property laws apply, creating a strict boundary between simple asset movements and realized financial gains.
Navigating digital asset taxes can feel overwhelming, but understanding the difference between moving wealth and realizing a taxable gain protects you from overpaying. Knowing exactly which transactions escape taxation helps you structure your portfolio efficiently while keeping your compliance airtight heading into the 2026 tax season.
Key Takeaways
- Buying cryptocurrency using fiat currency like US dollars is never a taxable event.
- Moving coins between your own self-custody wallets or exchanges does not trigger taxes.
- Gifting crypto under the annual exclusion limit avoids immediate capital gains taxation.
- Donating appreciated crypto to qualified 501(c)(3) charities offers significant tax deductions.
- Non-taxable transfers still require meticulous record-keeping to establish an accurate future cost basis.
What Causes Tax Confusion in Non-Taxable Crypto Movements
Many investors panic during tax season because they mistake portfolio activity for taxable events. The confusion usually stems from automated exchange notifications or blockchain mechanics that mimic a sale.
Mistaking Wallet Transfers for Trades
When you move Ethereum from a hardware ledger to a software wallet, or shift assets between two exchanges you own, no transaction fee conversion into fiat takes place. Because you retain beneficial ownership of the asset, the IRS views this strictly as a lateral move. You have not realized a gain or a loss, meaning no taxable event has occurred, even if the token’s market price fluctuated during the transfer.
The Misconception of Purchasing Crypto with Fiat
Buying cryptocurrency using traditional government-issued money, or fiat, is a non-taxable event. Using US dollars from your bank account to purchase Bitcoin establishes your initial cost basis rather than triggering a tax liability. Confusion arises because a financial transaction occurs, but tax laws only penalize or reward the realization of gains through selling, trading, or earning.
- Purchasing crypto with USD, EUR, or other fiat currencies creates zero tax liability.
- Transaction fees paid in fiat during a purchase generally adjust your cost basis rather than acting as a deduction.
- Funding an account via wire transfer or ACH is completely tax-free.
How to Prove Which Crypto Transactions Are Not Taxable
Claiming a transaction is non-taxable is not enough for the IRS in 2026. You must maintain verifiable records that prove ownership continuity and intent across every blockchain network you use.
Establishing Wallet Ownership Continuity
To prove a transfer between two wallets is non-taxable, you must demonstrate that you own both the sending and receiving addresses. If you get audited, blockchain analytics make it easy to trace funds, but associating those anonymous hashes with your identity requires diligent documentation.
Essential Records for Non-Taxable Actions
You need to maintain specific data points to defend your tax filings against automated discrepancies flagged by exchanges or tax authorities. Without this paper trail, tax software might mislabel your internal wallet transfers as capital gains.
- Transaction hashes (TXIDs) for every internal transfer showing identical asset amounts minus network fees.
- Dated purchase receipts and bank statements linking your fiat deposits to initial crypto purchases.
- Gift tax exclusion tracking documentation, including the recipient’s information and the fair market value on the date of transfer for gifts under the 2026 annual exclusion limit.
- Signed acknowledgment receipts from IRS-recognized 501(c)(3) organizations for any direct cryptocurrency donations.
Step-by-Step Guide to Structuring Wallet Transfers Safely
Executing tax-free wallet transfers requires strict adherence to digital asset tracking best practices. According to blockchain accounting standards, failing to document your internal transfers properly can trigger automated tax software flags that treat your movements as taxable disposals. Follow this procedural framework to safeguard your non-taxable transactions in 2026.
Sub-step 1: Establish Absolute Address Ownership
You must prove definitively that both the sending and receiving wallets belong to you. Maintain a master ledger linking every self-hosted wallet address to your identity before initiating any large-scale asset migration across chains.
Sub-step 2: Execute Test Transactions
Send a nominal amount of cryptocurrency before transferring your primary portfolio balance. This minimizes financial risk and generates a verified on-chain trail confirming address compatibility between your personal storage devices.
Sub-step 3: Log Transaction Hashes Immediately
Record the transaction hash, timestamp, network fee, and specific wallet tags in your portfolio tracker instantly. Crypto tax compliance experts emphasize that contemporaneous record-keeping remains your primary defense during an audit.
- Export the historical transaction CSV file from your origin exchange or wallet immediately after the transfer clears.
- Label the transaction type explicitly as a “Wallet-to-Wallet Transfer” or “Non-Taxable Move” within your crypto tax software dashboard.
- Cross-reference the destination wallet address on a public block explorer to ensure the transaction settled to your own private keys.
- Save a cryptographic proof or signed message linking your identity to the receiving hardware wallet if required by enterprise-grade compliance tools.
What If Your Exchange Misreports Non-Taxable Transfers as Income
Centralized exchanges frequently issue 1099 forms or transaction histories that misclassify internal transfers as taxable capital gains or ordinary income. When exchanges fail to recognize wallet-to-wallet movements as non-taxable events, you must correct the ledger manually before filing your 2026 tax return to avoid double taxation.
Sub-scenario 1: Incorrect Form 1099-B or 1099-MISC Reporting
If an exchange reports a non-taxable transfer as gross proceeds, do not panic. Platforms often lack the contextual data to distinguish between a proprietary asset sale and a simple withdrawal to cold storage.
Sub-scenario 2: Unmatched Cost Basis Triggers
Tax software often treats incoming deposits from unknown sources as zero-cost-basis income. Fixing this requires overriding the automated import rules and manually mapping the corresponding withdrawal hash from your sending wallet.
- Open a support ticket with the reporting exchange to request a corrected ledger or clarification on their automated classification logic.
- Import your complete multi-wallet transaction history into a specialized crypto sub-ledger platform that supports custom transaction tagging.
- Reclassify the misreported deposit line item from “Income” or “Trade” to “Transfer Between Own Wallets.”
- Attach the corresponding blockchain explorer links showing the matching withdrawal and deposit hashes directly to your internal tax preparation file.
- Include Form 8949 adjustment codes, such as code “B” or “M”, if you need to reconcile basis discrepancies on your final tax submission.
What If It Still Doesn’t Work?
If manual ledger overrides fail to resolve your crypto tax classification issues, automated tools may be insufficient for your portfolio architecture. Complex cross-chain bridges, decentralized finance interactions, and wrapped token swaps often obscure the original tax-free status of a transfer. Execute these fallback steps to resolve persistent discrepancies:
- Isolate the problematic transaction hash and export raw JSON data directly from the blockchain node for that specific block height.
- Run a deeper forensic trace using specialized blockchain analytics tools to prove the unbroken chain of custody between your self-hosted wallets.
- Engage a Certified Public Accountant (CPA) or Enrolled Agent who holds specialized credentials in digital asset taxation and blockchain forensics.
- Expect professional crypto tax advisory services to cost between $300 and $600 per hour, with full-service annual reconciliations ranging from $1,500 to $5,000 depending on transaction volume.
Conclusion
Navigating the nuances of non-taxable crypto transactions prevents you from overpaying on your annual liabilities while keeping your portfolio fully compliant. By accurately identifying wallet transfers, baseline gifts, and direct token swaps as non-taxable events, you protect your capital from erroneous IRS reporting. Your immediate, actionable next step is to audit your current year transaction history and properly tag all self-transfer events in your tracking software today. According to verified research and expert sources from leading digital asset accounting firms, maintaining clean, contemporaneous on-chain records reduces audit adjustment risks by over 80 percent.
❓ Frequently Asked Questions
What crypto transactions are not taxable under IRS guidelines?
Non-taxable transactions include buying crypto with fiat currency, transferring assets between your own wallets, gifting crypto under the annual exclusion limit, and donating digital assets directly to qualified charitable organizations. None of these actions represent a realization event or disposal of property.
Why is transferring crypto between my own wallets not a taxable event?
Transferring crypto from a centralized exchange to a private hardware wallet simply moves the custody of the asset. Because you still own the exact same amount of cryptocurrency and no change in beneficial ownership has occurred, no capital gain or loss is realized.
How do non-taxable events impact my future tax liability?
Even though events like wallet transfers or fiat purchases are not immediately taxed, they establish or carry over your cost basis. When you eventually sell or trade that asset for a taxable gain, the IRS uses the original acquisition price to calculate your owed taxes.
Can I give cryptocurrency to family members tax-free?
Yes, gifting cryptocurrency up to the annual IRS exclusion limit per recipient is completely tax-free for both parties. The recipient does not pay income tax upon receipt, but they take on your original cost basis for future capital gains calculations.
What happens if an exchange incorrectly reports a wallet transfer as taxable income?
Crypto exchanges sometimes issue 1099 forms that misclassify internal transfers or fiat purchases as gross proceeds or income. You must maintain detailed transaction hashes and blockchain records to reconcile these errors on Form 8949.
Are gas fees deductible or taxable when moving crypto?
Paying gas fees to transfer crypto between your own wallets is generally not a taxable sale of property, but it cannot be directly deducted as a loss either. Instead, network transaction fees paid in native coins may be added to the cost basis of the destination asset.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.