Minimum Income to File Taxes 2026 Expert Guide & IRS Rules
Navigating IRS rules to determine the minimum income to file taxes depends heavily on your filing status, age, and source of income. This guide breaks down the exact IRS filing thresholds for 2026 so you know precisely when a tax return is legally required.
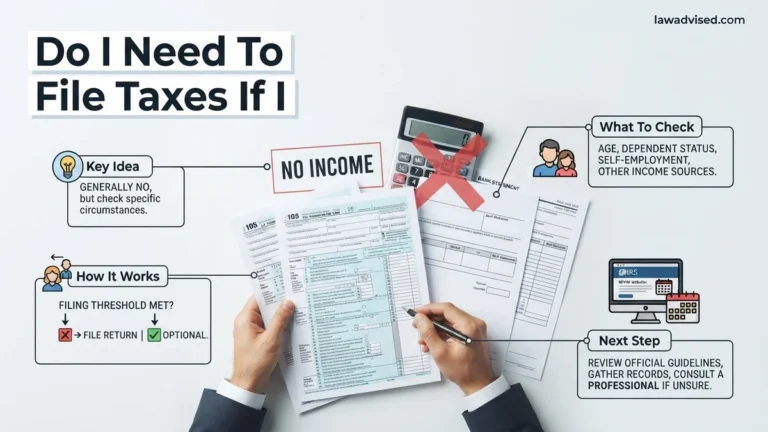
For the 2026 tax year, whether you must file a federal income tax return depends primarily on your total gross income, your filing status, and your age. If your gross income stays below the specific IRS threshold for your situation, you generally are not required to file a return. However, knowing these exact dollar amounts prevents you from skipping a return when you actually qualify for refundable tax credits.
Determining your filing requirement matters practically because filing is often the only way to claim money the IRS owes you through credits like the Earned Income Tax Credit. Even if you fall below the mandatory minimum income to file taxes, submitting a return is necessary to get back any federal income tax withheld from your paychecks throughout 2026.
Key Takeaways
- Filing thresholds vary by filing status, standard deduction amounts, and age.
- Self-employed individuals must file if net earnings reach $400 or more.
- Dependents face strict, lower income limits before a tax return is required.
- You should still file below the threshold to claim refundable tax credits.
- Always verify unearned income limits separately from traditional wage earnings.
What Causes IRS Filing Obligations and Determines Your Threshold
Filing Status and Standard Deduction Alignment
The IRS ties your filing obligation directly to the standard deduction for each specific filing status. When your gross income equals or exceeds the standard deduction allotted for your category, a federal tax return becomes mandatory.
- Single: Your filing trigger matches the base standard deduction for single filers.
- Married Filing Jointly: The threshold combines both spouses’ deductions into a higher joint limit.
- Head of Household: You receive a higher threshold than single filers to account for dependent care costs.
Age Adjustments for Older Taxpayers
Your birth date also shifts your mandatory filing threshold upward. The IRS grants an additional standard deduction if you reach age 65 before the close of the 2026 tax year. This means you can earn slightly more money before crossing the mandatory filing line compared to younger workers in the exact same household situation.
How to Calculate Your Gross Income and Compare It to 2026 IRS Limits
Summing Up Your Worldwide Income Sources
To see if you cross the 2026 threshold, you must calculate your total gross income. Gross income includes all income you receive in the form of money, goods, property, and services that is not exempt from tax.
- Wages, salaries, tips, and professional fees from employers or clients.
- Unemployment compensation, taxable pension distributions, and certain retirement account withdrawals.
- Investment gains, taxable interest, and dividend income earned throughout the year.
Comparing Totals Against the Official Thresholds
Once you total your gross income, compare that single figure against the official 2026 IRS limits for your specific demographic. Remember to exclude tax-exempt sources, such as certain life insurance payouts or municipal bond interest, from your initial calculation. If your final gross income sits even one dollar above your designated limit, federal law requires you to file a 2026 tax return.
Step-by-Step Guide to Evaluating Special Rules for Self-Employment and Dependents
Determining your filing requirement becomes more complex when you earn independent income or can be claimed as a dependent by another taxpayer. According to IRS guidelines for 2026, standard gross income thresholds do not apply universally to every financial situation.
Evaluating Self-Employment Net Earnings
If you work freelance, gig-economy jobs, or run a small business, the threshold drops significantly. You must file a federal tax return if your net self-employment earnings reach $400 or more, regardless of your age or filing status.
- Calculate your total gross business receipts or revenue for the 2026 tax year.
- Subtract all ordinary and necessary business expenses to find your net earnings.
- Compare your net profit to the $400 statutory threshold set by the IRS.
- File Form 1040 and Schedule SE if your net earnings meet or exceed this amount to pay self-employment tax for Social Security and Medicare.
Assessing Dependent Filing Status
Taxpayers who qualify as dependents on someone else’s return face unique rules. Financial analysts note that unearned income, such as dividends or interest, triggers lower thresholds than earned income from a W-2 job.
- Review the dependency rules to confirm whether a parent or guardian will claim you for 2026.
- Calculate your total earned income (wages, tips, salaries) and unearned income (investments, trust payouts).
- Apply the 2026 dependent specific limits, where unearned income exceeding $1,300 or total income exceeding the standard deduction for dependents requires filing.
What If Your Income Is Below the Minimum But You Still Want to File
Falling below the IRS minimum income threshold for 2026 does not mean you are prohibited from submitting a tax return. In many cases, filing a voluntary return is financially advantageous because it unlocks unclaimed federal benefits.
Key Benefits of Voluntary Filing
Tax experts emphasize that leaving money on the table happens frequently when low-income earners skip filing. Refundable tax credits like the Earned Income Tax Credit (EITC) and the Child Tax Credit can deliver substantial cash payouts even with zero tax liability.
- Claim refundable credits that pay out money directly to you, even if you owe zero income tax.
- Recover federal income tax withheld from your paychecks throughout the year by your employer.
- Establish an official filing record, which lenders and financial institutions often require for loan applications or student aid.
What If It Still Doesn’t Work?
Navigating complex 2026 tax thresholds can occasionally lead to uncertainty or conflicting calculations. If standard guidelines fail to clarify your filing requirement, use these troubleshooting steps to find resolution:
- Run your specific income and deduction figures through the Interactive Tax Assistant tool on the official IRS website.
- Gather all W-2s, 1099s, and records of unearned income to perform a secondary reconciliation of your gross total.
- Consult a certified public accountant (CPA) or Enrolled Agent (EA) to review edge cases involving multi-state residency or complex investment portfolios. Professional tax advisory services typically cost between $150 and $450 depending on complexity.
- Utilize IRS-certified free tax preparation programs like VITA (Volunteer Income Tax Assistance) if your household income falls below the program limit.
Conclusion
Navigating the minimum income to file taxes for 2026 ensures compliance while protecting valuable financial opportunities. Accurately assessing your filing status prevents costly IRS penalties while maximizing potential refunds from withheld taxes. According to verified research and expert tax sources, reviewing your exact gross income against current statutory thresholds remains the single most effective way to optimize your annual tax strategy. Take your next step today by gathering your earnings documents and running your totals against the latest IRS guidelines.
❓ Frequently Asked Questions
What happens if I fail to file a tax return when my income is above the minimum threshold?
Failing to file a required tax return can result in failure-to-file penalties, interest charges, and potential delays in receiving any refunds owed to you by the IRS.
How do married couples determine their filing threshold when filing jointly?
Married couples filing jointly combine their gross incomes and compare the total against the combined standard deduction threshold established for joint filers.
Do scholarship amounts count as gross income for tax filing purposes?
Taxable scholarships and fellowships count toward gross income, whereas qualified tuition and related expenses used for required education do not.
Are Social Security benefits considered gross income for filing requirements?
Social Security benefits may be included in gross income calculations depending on your total provisional income and combined filing status.
What are the specific tax rules for minor children or student dependents?
Dependents have unique, much lower earned and unearned income thresholds that dictate whether they must file their own separate tax returns.
Should I file a tax return even if my income is well below the minimum requirement?
Filing is recommended if you qualify for refundable credits like the Earned Income Tax Credit or need to claim withheld income taxes back from the government.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.