Crypto Capital Gains Explained 2026 A Step-by-Step Guide
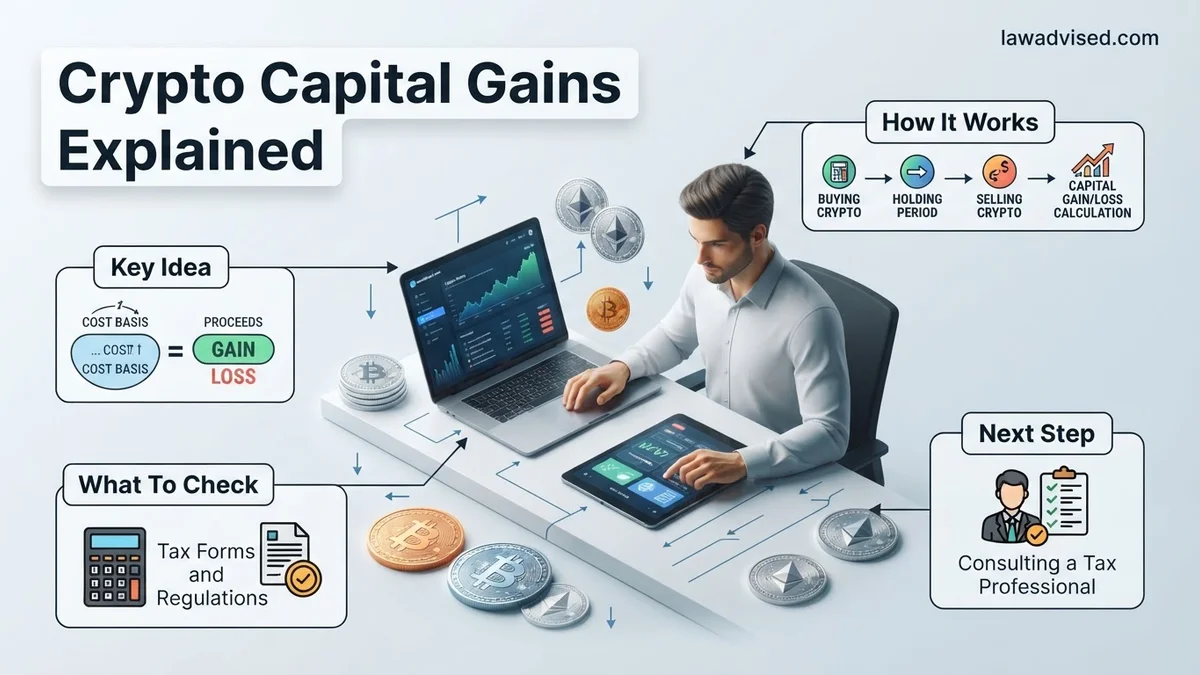
Navigating crypto capital gains requires understanding how the IRS and tax authorities treat digital assets as property rather than currency. You trigger a taxable event whenever you sell crypto for fiat, trade one token for another, or use it to purchase goods and services. Calculating your liability depends directly on your cost basis, proceeds, and how long you held the asset.
Cryptocurrency capital gains happen whenever you sell, trade, or spend your digital assets for more than you originally paid for them. Tax authorities worldwide view crypto as property, meaning every single disposal is a taxable event that requires accurate tracking, calculation, and reporting.
As tax enforcement tightens globally in 2026, understanding how these gains are calculated protects you from unexpected audit penalties and ensures you do not overpay. This step-by-step guide breaks down exactly what triggers a taxable event and how to compute your exact profits or losses.
Key Takeaways
- Crypto is taxed as property, meaning every trade is a taxable event.
- Calculate gains by subtracting your cost basis from your total proceeds.
- Short-term capital gains are taxed at standard ordinary income tax rates.
- Long-term capital gains qualify for preferential lower tax brackets.
- Tracking tools and FIFO/LIFO methods simplify accurate tax reporting.
What Causes Crypto Capital Gains and Taxable Events
Common Taxable Crypto Triggers
Many crypto holders mistakenly believe that taxes are only owed when converting digital assets back into fiat currency like US dollars. In reality, the tax code covers a wide range of everyday crypto transactions. You trigger a taxable capital gain or loss the moment you execute any of the following actions:
- Selling cryptocurrency for fiat currency (like USD or EUR).
- Trading one cryptocurrency for another, such as swapping Ethereum for Solana.
- Purchasing goods or services using cryptocurrency.
- Receiving crypto through certain airdrops or hard forks where you gain dominion over the asset.
Non-Taxable Events to Keep in Mind
Not every movement of crypto triggers a tax liability. Knowing what is exempt saves you from needlessly reporting non-taxable transactions:
- Transferring crypto between your own wallets or exchanges.
- Buying cryptocurrency using fiat currency and simply holding it.
- Gifting crypto up to the annual exclusion limits (though recipient basis rules apply later).
- Donating cryptocurrency directly to a qualified tax-exempt charity.
How to Step-by-Step Calculate Your Crypto Gains and Losses
The Golden Formula: Proceeds Minus Cost Basis
Calculating your crypto capital gains relies on a straightforward financial equation. For every taxable disposal, you must determine your exact proceeds and subtract your cost basis. The resulting number is your capital gain or loss.
- Proceeds: The fair market value of the asset in fiat currency at the exact moment you sold, traded, or spent it, minus any transaction or exchange fees.
- Cost Basis: What you originally paid for the asset, including any purchase fees or commissions.
- The Calculation: Proceeds minus Cost Basis equals your Capital Gain (if positive) or Capital Loss (if negative).
A Practical Calculation Example
Imagine you purchased one Ethereum back in 2024 for 2,000 dollars, paying a 10 dollar purchase fee. Your total cost basis is 2,010 dollars. In 2026, you decide to trade that Ethereum for a different altcoin when Ethereum is valued at 4,000 dollars, incurring a 15 dollar trading fee.
Your proceeds equal 3,985 dollars (4,000 dollar market value minus the 15 dollar fee). Subtracting your 2,010 dollar cost basis leaves you with a taxable capital gain of 1,975 dollars. You must report this specific gain on your 2026 tax filing, regardless of whether you converted the funds back to cash.
Best Practices for Distinguishing Short-Term and Long-Term Holding Periods
Accurately separating short-term from long-term capital gains is essential for optimizing your tax liability in 2026. The Internal Revenue Service applies ordinary income tax rates to assets held for one year or less, while preferential long-term rates apply to assets held for over 365 days. Managing this distinction requires meticulous ledger maintenance.
Step 1: Implement Specific Identification Methods
According to crypto tax experts, defaulting to FIFO (First-In, First-Out) can trigger unnecessarily high tax burdens if your earliest acquisitions were low-cost tokens. Use specific identification methods to designate exact tax lots upon disposal. This strategy allows you to sell higher-cost lots first, minimizing realized gains.
Step 2: Automate Date Tracking Across Wallets
Holding periods reset when transferring assets between non-custodial wallets and centralized exchanges if the transaction is mislabeled. Use automated portfolio trackers that ingest transaction hashes to preserve original acquisition timestamps. Verifying these holding periods prevents the common error of misclassifying short-term trades as long-term investments.
What If Your Crypto Accounting Method Still Does Not Match Exchange Records?
Reconciling discrepancies between self-hosted software and Form 1099s issued by centralized exchanges can be challenging. When automated accounting tools fail to align with historical exchange exports, systematic manual intervention is required to satisfy regulatory standards for 2026 tax filings.
Fallback Troubleshooting Steps
- Export raw CSV files directly from every exchange API and manually cross-reference transaction IDs with your blockchain explorer logs.
- Isolate missing cost basis data by tagging untracked airdrops, hard forks, or decentralized finance (DeFi) staking rewards as zero-cost basis items until verified.
- Re-run the calculation engine using an alternative valuation method, such as moving from FIFO to LIFO, to identify where decimal rounding or token ticker changes caused ledger drift.
- Engage a certified public accountant (CPA) specializing in digital assets if discrepancies exceed standard thresholds or involve complex cross-chain bridges. Professional tax advisory services typically range from $300 to $1,500 depending on portfolio volume.
Conclusion
Navigating crypto capital gains in 2026 requires understanding the crucial divide between short-term and long-term holding periods while maintaining airtight transaction records. Reconciling software outputs with exchange statements prevents costly compliance flags and audits. According to verified research and expert sources from leading digital asset advisory firms, proactive portfolio tracking remains the single most effective way to legally minimize tax liabilities. Your immediate actionable next step is to audit your active wallet connections today to ensure every historical trade log accurately reflects its true acquisition date.
❓ Frequently Asked Questions
How are mining, staking, and airdrops taxed?
Mining, staking rewards, and airdrops are taxed as ordinary income based on the fair market value of the tokens at the time you receive control of them. When you eventually sell those tokens, any subsequent price change is treated as a capital gain or loss.
What happens if I experience a capital loss on my crypto?
Crypto capital losses can be used to offset your capital gains from other investments dollar-for-dollar. If your total losses exceed your gains, you can deduct up to $3,000 of ordinary income per year.
What accounting method should I use for crypto cost basis?
The most common and widely accepted accounting method is FIFO (First-In, First-Out), though LIFO (Last-In, First-Out) or HIFO (Highest-In, First-Out) may be permitted depending on your jurisdiction and recordkeeping.
Do I owe taxes if my crypto loses value and I just hold it?
No, holding crypto that has dropped or risen in value does not trigger a taxable event. Taxes are only realized when you dispose of, trade, or spend the asset.
Are hardware wallet purchases considered taxable dispositions?
Moving crypto from an exchange to a private hardware wallet you own is a non-taxable transfer because there is no change in beneficial ownership.
What records do I need to keep for crypto taxes?
You should maintain records of the date and time of every transaction, the fair market value in fiat at the time of the transaction, transaction fees, and wallet addresses involved.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.