Bitcoin Taxes Explained 2026 A Step-by-Step Guide
Navigating bitcoin taxes requires understanding when a taxable event actually occurs during trading, selling, or earning crypto. This guide breaks down capital gains, income tax rules, and how to accurately report your transactions to tax authorities.
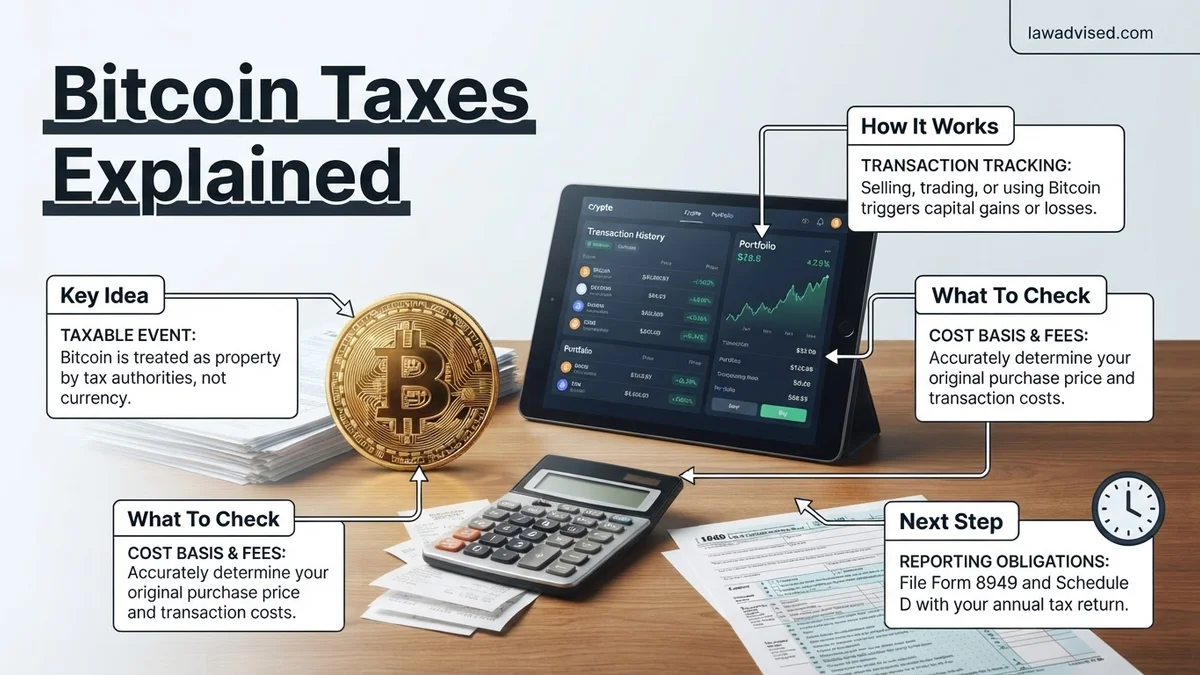
Tax authorities treat Bitcoin and other cryptocurrencies as property, not currency, meaning every time you trade, sell, or spend your digital assets, you trigger a potential tax event. For the 2026 tax year, reporting compliance has tightened significantly, with major exchanges and decentralized platforms facing stricter data-sharing mandates to track user transactions.
Navigating these rules successfully requires you to understand the exact line between a taxable transaction and a non-taxable movement of funds. Missing a single crypto-to-crypto trade on your return can trigger automated IRS audits, making accurate tracking essential for every digital asset holder this year.
Key Takeaways
- Trading one cryptocurrency for another is a taxable event.
- Transferring coins between your own personal wallets is never taxed.
- Short-term capital gains apply to assets held for one year or less.
- Mining and staking rewards are taxed as ordinary income upon receipt.
- Crypto tax software simplifies calculating your cost basis and capital gains.
What Causes Taxable Events in Bitcoin Transactions
You need to know precisely which actions trigger a tax obligation and which do not. The IRS looks closely at how you move, spend, or exchange your Bitcoin holdings.
Taxable Bitcoin Events
- Selling Bitcoin for fiat currency: Converting your BTC into US dollars and withdrawing it to your bank account is a direct capital gains event.
- Trading Bitcoin for another altcoin: Swapping BTC for Ethereum or any other token is treated as selling your Bitcoin at market value and immediately buying a new asset.
- Spending Bitcoin on goods or services: Using your Bitcoin to buy a coffee or a car is legally treated as selling the crypto for its cash value at that exact moment.
- Earning Bitcoin: Receiving BTC through mining, staking rewards, or getting paid in crypto counts as ordinary income based on its fair market value on the day you receive it.
Non-Taxable Bitcoin Events
- Buying Bitcoin with fiat currency: Simply purchasing and holding Bitcoin in your own wallet does not create a tax bill.
- Transferring between personal wallets: Moving your BTC from an exchange to a hardware wallet or between two wallets you own is a non-taxable event.
- Gifting Bitcoin: Giving Bitcoin to someone else typically does not trigger immediate taxes, though the recipient inherits your original cost basis.
How to Calculate Your Bitcoin Capital Gains and Losses
When you dispose of Bitcoin through a sale or trade, you must calculate your exact capital gain or loss. This process relies on comparing what you originally paid against what you received.
The Core Formulas You Need
- Cost Basis: This is the total amount you spent to acquire the Bitcoin, calculated as the purchase price plus any transaction or exchange fees you paid.
- Proceeds: This is the total value you received when disposing of the Bitcoin, calculated as the final sale price minus any transaction fees.
- The Calculation: Subtract your cost basis from your proceeds. If the number is positive, you have a capital gain. If it is negative, you have a capital loss.
Applying Holding Periods in 2026
- Short-Term Gains: If you held the Bitcoin for one year or less before disposing of it, your gains are taxed at your ordinary federal income tax bracket.
- Long-Term Gains: If you held the Bitcoin for more than one year, you qualify for preferential long-term capital gains tax rates of 0 percent, 15 percent, or 20 percent depending on your total taxable income.
- Tax-Loss Harvesting: You can use your capital losses from Bitcoin to offset your capital gains from stocks or other crypto, and deduct up to $3,000 of excess losses against your ordinary income.
Step-by-Step Instructions to Report Crypto on Your Tax Return
Filing your digital asset transactions accurately requires a methodical approach to ensure compliance with the latest regulations. Whether you use specialized software or prepare returns manually, following a structured workflow prevents costly calculation errors.
Gathering Documentation and Form 8949
You must compile all transaction histories from every exchange and wallet you utilized during the tax year. The primary document required by the IRS is Form 8949, which details each capital asset disposition, paired with Schedule D to summarize overall gains and losses.
- Download comprehensive CSV transaction exports from all centralized exchanges, decentralized platforms, and cold storage wallets you accessed.
- Reconcile your trades, transfers, and income events using specialized crypto tax software or a detailed ledger to determine precise cost basis.
- Transfer the finalized totals of your short-term and long-term capital gains and losses onto Form 8949.
- Carry the final combined totals from Form 8949 over to Part I or Part II of Schedule D on your Form 1040.
What If Your Crypto Tax Records Are Incomplete or Missing
Missing historical records from defunct exchanges or untracked wallet transfers present a significant hurdle during tax season. Constructing a defensible audit trail requires systematic reconstruction methods to satisfy reporting obligations without guessing.
Reconstructing Historical Data
When original trade data is unavailable, taxpayers must apply specific investigative steps to piece together their transaction history.
- Request historical account statements, API keys, or trade archives directly from customer support channels of operational or recently closed platforms.
- Query public blockchain explorers using your known wallet public addresses to trace historical incoming and outgoing transaction timestamps.
- Apply conservative cost basis estimations, such as assigning a zero cost basis to unverified tokens, keeping in mind that this increases tax liability.
- Consult a certified public accountant or digital asset tax attorney to evaluate compliance risks before filing an incomplete return.
What If It Still Doesn’t Work?
If self-reconciliation fails or your transaction volume exceeds standard software capabilities, targeted troubleshooting steps are required to avoid filing inaccurate data.
- Upgrade to an enterprise-tier crypto tax software package that supports advanced manual tagging and customized ledger overrides.
- Engage a specialized certified public accountant or Enrolled Agent who focuses exclusively on blockchain forensics and digital asset taxation.
- Prepare for professional service fees, which typically range from $500 to $2,500+ depending on transaction volume and the complexity of decentralized finance interactions.
- File for a standard six-month tax extension using Form 4868 to secure adequate time for comprehensive data reconstruction.
Conclusion
Navigating digital asset reporting demands precision, diligent record-keeping, and strict adherence to evolving tax guidelines. According to verified research and tax experts, proactive tracking throughout the year significantly reduces audit risks and prevents overpayment. Take your next actionable step today by exporting your current transaction history and running an initial compliance audit.
❓ Frequently Asked Questions
What is the difference between short-term and long-term capital gains for Bitcoin?
Short-term capital gains apply to Bitcoin held for one year or less and are taxed at your ordinary income tax rate. Long-term capital gains apply to assets held for more than one year and benefit from lower preferential tax rates.
How do I calculate a capital gain or loss on a Bitcoin sale?
Subtract your cost basis (purchase price plus fees) from your proceeds (sale price minus fees). The resulting positive number is a capital gain, while a negative number is a capital loss.
What tax forms do I need to file for my Bitcoin transactions?
You typically need to report your cryptocurrency capital gains and losses on IRS Form 8949 and summarize them on Schedule D of your Form 1040 tax return.
How are airdrops and hard forks taxed?
Airdrops and hard forks that result in new tokens are generally taxed as ordinary income based on the fair market value of the coins at the time you gain dominion and control over them.
What happens if I forget to report my Bitcoin transactions?
Failing to report cryptocurrency transactions can lead to IRS audits, back taxes, substantial penalties, and potential interest charges on unpaid tax liabilities.
Can I use crypto tax software to automate my reporting?
Yes, dedicated crypto tax software can connect to your exchange accounts and wallets via API to automatically track transactions, calculate cost basis, and generate completed tax forms.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.