Crypto Mining Taxes Explained 2026 Step-by-Step Guide
Navigating crypto mining taxes requires reporting mined coins as ordinary income based on their fair market value the exact day you receive them. Failing to account for these IRS rules can lead to significant penalties, making proper tracking of income and operational expenses essential.
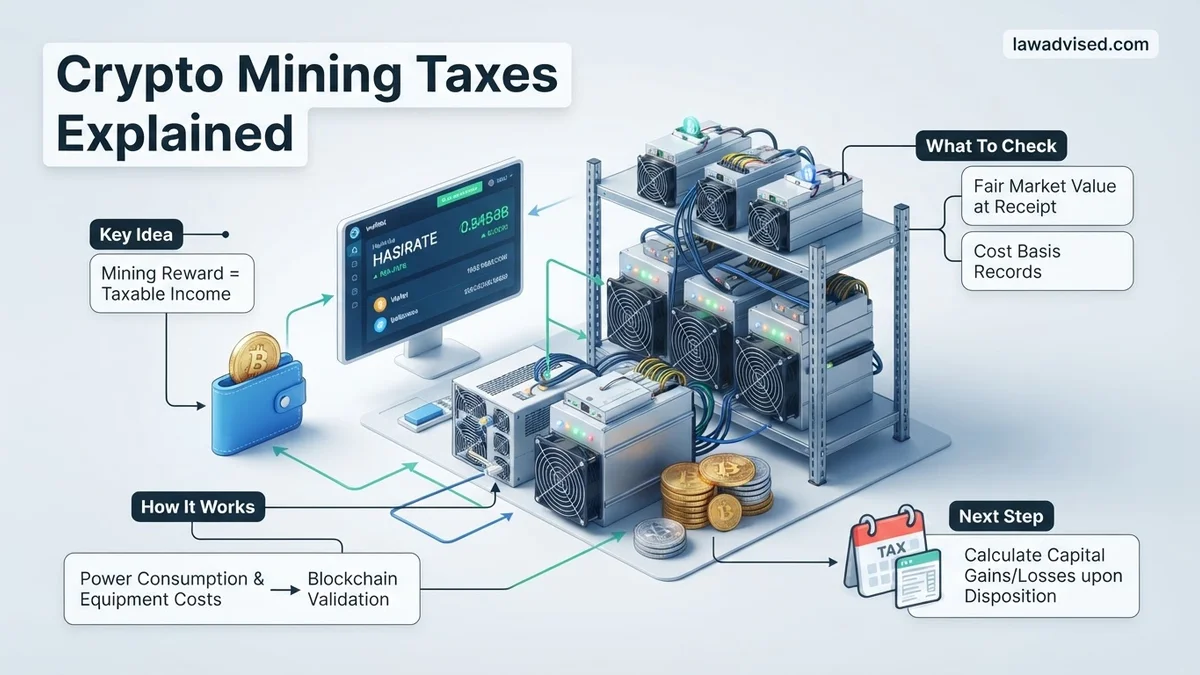
You owe federal income tax on cryptocurrency mining rewards the exact moment they hit your wallet, calculated at their fair market value in US dollars. The IRS treats newly minted coins as ordinary income, meaning you must report these earnings on your tax return regardless of whether you immediately sell them or hold them for the long term.
Navigating these tax obligations in 2026 requires precise record-keeping and a clear understanding of how mining activities are classified under current tax code. This guide breaks down the mechanics of reporting mining income and utilizing legitimate deductions to protect your bottom line.
Key Takeaways
- Report mined crypto as ordinary income at the fair market value on the day of receipt.
- Deduct eligible business expenses like specialized hardware, electricity, and facility maintenance.
- Distinguish between hobby mining and commercial operations to maximize valid tax write-offs.
- Calculate capital gains or losses when you eventually sell, trade, or spend your mined assets.
- Maintain detailed transaction logs to accurately track your cost basis for every block rewarded.
What Causes Tax Liabilities When Earning Crypto Mining Rewards
Immediate Income Recognition Event
The IRS considers cryptocurrency mining as a taxable event the second you gain dominion and control over the asset. When your mining pool payout or newly solved block reward transfers to your digital wallet, you have received gross income. You cannot defer this tax liability until you convert the crypto into fiat currency or trade it for another token.
Self-Employment Tax Obligations
If you operate your mining operation as a business or a regular side hustle, your mining rewards are also subject to self-employment tax. This covers your contributions to Social Security and Medicare.
- Mining as a sole proprietorship requires filing Schedule C.
- Net earnings from mining exceeding four hundred dollars trigger self-employment tax.
- You must calculate this in addition to your standard federal income tax bracket.
How to Calculate Fair Market Value and Report Mining Income
Determining Dollar Value at Receipt
To report your taxes accurately, you need to establish the fair market value of the mined cryptocurrency on the exact day and hour you received it. If you mine 0.05 Ethereum on a Tuesday afternoon when ETH trades at three thousand dollars, you report one hundred and fifty dollars of ordinary income.
- Use reputable crypto pricing APIs or major exchange data for your timestamp.
- Log the exact UTC time and date of every single payout.
- Maintain a ledger spreadsheet to track coin price fluctuations daily.
Reporting on IRS Forms
Filing your 2026 crypto mining taxes correctly means using the appropriate IRS forms to separate ordinary income from subsequent capital gains. If you later sell that mined crypto for a higher price, you will face capital gains tax on the appreciation.
- Report mining income on Schedule 1 of Form 1040, or Schedule C if operating a business entity.
- Track your cost basis meticulously because your initial income value becomes your tax basis for future sales.
- Answer the digital asset question truthfully on page one of your tax return.
How to Fix High Tax Bills by Deducting Rig Expenses and Electricity
Mining cryptocurrency generates significant overhead that can dramatically lower your 2026 taxable income. According to IRS guidelines, legitimate business miners can write off ordinary and necessary expenses incurred during operations. Maximizing these deductions is the single most effective way to lower an inflated crypto tax bill.
Step 1: Deducting Hardware and Rig Depreciation
ASIC miners and high-end GPUs are expensive capital assets. Under Section 179 and bonus depreciation rules active for the 2026 tax year, miners can often deduct the full cost of new hardware in the year of purchase rather than depreciating it over several years. Keep all original purchase invoices, serial numbers, and delivery dates to substantiate these hardware write-offs.
Step 2: Writing Off Electricity and Facility Costs
Power consumption accounts for up to 70 percent of a miner’s operational expenses. To legally deduct electricity costs, miners must maintain a dedicated workspace or commercial facility. Home miners must calculate the exact kilowatt-hour (kWh) usage of their rigs relative to the total household consumption using sub-meters. According to CPA tax specialists, failing to isolate commercial power usage from personal utility bills is a primary trigger for IRS scrutiny.
- Calculate total monthly kWh consumed strictly by mining hardware based on manufacturer wattage specifications.
- Multiply the consumed kWh by your local commercial or residential utility rate to establish the direct business expense.
- Deduct auxiliary operational costs, including industrial cooling fans, racking units, high-speed internet data plans, and commercial lease payments.
What If It Still Doesn’t Work: Managing Capital Gains and IRS Audits
If deductions fail to reduce your tax liability below acceptable thresholds, or if complex coin-to-coin transactions have triggered unexpected capital gains liabilities, immediate structural adjustments are necessary. High-volume miners facing aggressive tax bills or potential audits should execute the following fallback steps:
- Reconcile all wallet addresses using specialized 2026 crypto accounting software to ensure no mined coins were double-counted as both ordinary income and capital gains.
- Separate hobby mining from commercial mining activities if the IRS reclassifies your operation, adjusting your deductible expense limits accordingly.
- Hire a Certified Public Accountant (CPA) or Enrolled Agent (EA) specializing in digital asset taxation; professional advisory fees typically range from $1,500 to $5,000 depending on transaction volume.
- Establish a formal corporate structure, such as a Single-Member LLC or S-Corporation, to legally isolate personal assets from future mining tax liabilities.
Conclusion
Navigating crypto mining taxes in 2026 requires meticulous record-keeping, accurate fair market value tracking at the exact moment of coin receipt, and aggressive utilization of hardware and utility deductions. According to verified research and tax experts, failing to properly account for operational expenses is the leading cause of costly IRS audits for digital asset miners. Your immediate actionable next step is to audit your current mining ledger and cross-reference your electricity expenses against your exchange payouts today.
❓ Frequently Asked Questions
How does the IRS classify cryptocurrency obtained through mining?
The IRS classifies mined cryptocurrency as gross income. This means the fair market value of the coins on the day you gain dominion and control over them must be reported on your tax return as taxable income.
What is the difference between hobby mining and business mining for tax purposes?
Business miners operate with the primary intent to make a profit, allowing them to deduct expenses like hardware depreciation, repairs, and electricity. Hobby miners engage in the activity recreationally and cannot deduct these operational costs from their taxes.
How do I calculate the cost basis for mined crypto when I decide to sell it?
Your initial cost basis is the fair market value of the cryptocurrency at the exact time you mined it and reported it as income. When you sell the asset later, your capital gain or loss is the difference between your selling price and this initial cost basis.
Are mining pool fees tax-deductible?
Yes, pool fees charged by mining pools are considered ordinary and necessary business expenses. If you operate a mining business, you can deduct these fees directly from your gross mining revenue.
What records should I keep to stay compliant with crypto mining tax laws?
You should maintain comprehensive logs showing the exact date and time you received mined rewards, the fair market value in USD at that moment, transaction hash IDs, receipts for all hardware purchases, and monthly utility bills.
What happens if I fail to report my crypto mining income to the IRS?
Failing to report mining income can result in IRS audits, back taxes, severe underreporting penalties, and accumulating interest. Because blockchain transactions are permanent and traceable, non-compliance carries a high risk of detection.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.