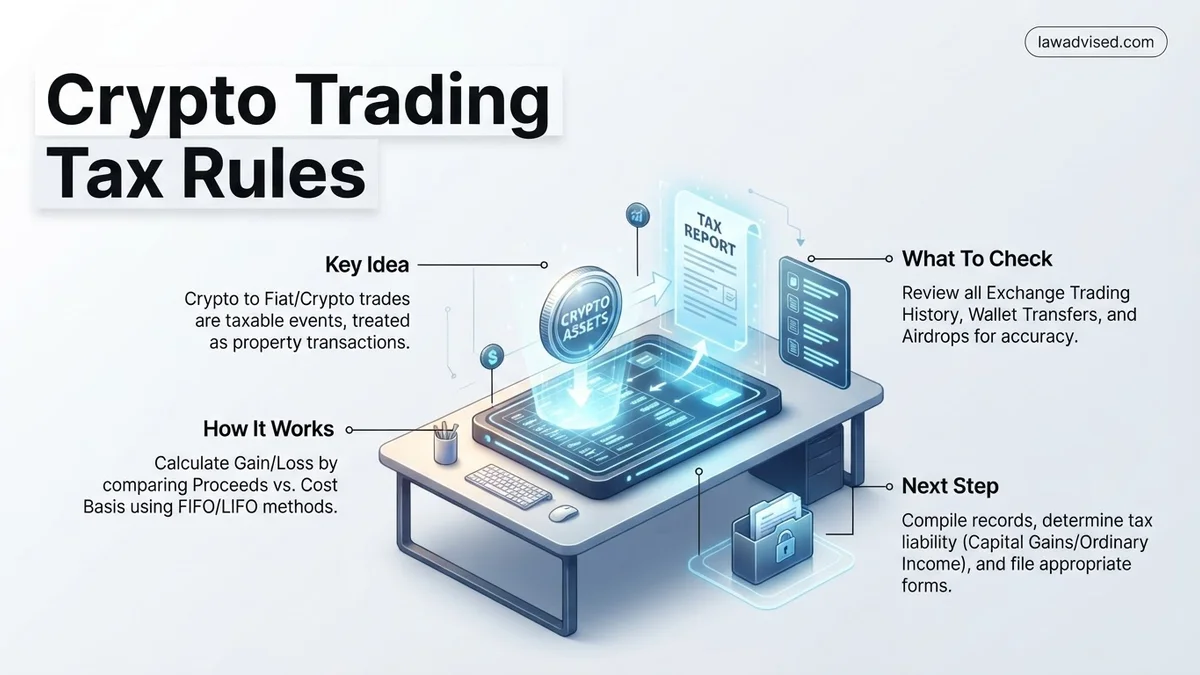
Crypto Trading Tax Rules 2026 A Step-by-Step Guide
Navigating crypto trading tax rules requires identifying taxable events like crypto-to-crypto trades and sales for fiat currency. Capital gains and income tax rates apply depending on how long assets are held and how they are acquired. Proper reporting on IRS Form 8949 prevents costly compliance penalties.
Navigating crypto trading tax rules requires understanding that the Internal Revenue Service and global tax authorities treat digital assets strictly as property, not currency. Every single time you trade one token for another, spend crypto on goods, or earn rewards through staking, you trigger a reportable event that impacts your total tax liability for the year.
Ignoring these rules is no longer an option as tax agencies in 2026 enforce stricter reporting mandates through automated exchange data sharing. To protect yourself from unexpected audits and severe penalties, you must distinguish between events that trigger taxes and routine wallet movements that do not, while accurately calculating your cost basis and capital gains.
Key Takeaways
- Crypto-to-crypto trades are fully taxable events that trigger capital gains or losses.
- Moving assets between your own wallets is a non-taxable event.
- Short-term capital gains are taxed at ordinary income rates based on your tax bracket.
- Staking, mining, and airdrops are taxed as ordinary income upon receipt.
- Always calculate cost basis using IRS-compliant accounting methods like FIFO, LIFO, or HIFO.
What Causes Tax Liabilities in Crypto Trading and Why Tracking Fails
Taxable Events vs Non-Taxable Events
The biggest misconception in crypto trading is that you only owe taxes when you cash out to fiat currency like US dollars. In reality, the moment you trade Ethereum for Solana, you have legally disposed of property, making it a fully taxable event. Tax agencies view crypto-to-crypto trades as selling one asset to buy another at current market value.
You face specific rules regarding which transactions trigger immediate reporting:
- Taxable: Selling crypto for fiat currency (USD, EUR).
- Taxable: Trading one cryptocurrency for another (e.g., BTC for ETH).
- Taxable: Using cryptocurrency to purchase goods or services.
- Taxable: Earning rewards from staking, mining, or airdrops.
- Non-Taxable: Buying cryptocurrency using fiat currency and holding it.
- Non-Taxable: Moving crypto between your own wallets or hardware devices.
Why Manual Tracking Fails Active Traders
If you trade across multiple centralized exchanges, decentralized protocols, and various Layer 2 networks, manual spreadsheets will fail you. Gas fees, bridge transactions, and airdrops muddy the waters quickly. By the time tax season arrives in 2026, missing just a few historical price feeds can throw off your entire portfolio accounting, leaving you vulnerable to paying taxes on phantom gains or failing to claim legitimate capital losses.
How to Calculate Capital Gains, Losses, and Cost Basis Step by Step
The Core Calculation Formula
To report your taxes accurately, you must determine the capital gain or loss for every single disposition. The formula is straightforward, but gathering the correct inputs requires precision. You take your Proceeds (the fair market value of the asset when disposed of, minus transaction fees), and subtract your Cost Basis (what you originally paid for the asset, plus any purchase fees).
If your proceeds exceed your cost basis, you have a capital gain. If your cost basis is higher, you have registered a capital loss that can offset your gains and up to $3,000 of ordinary income.
Choosing Your Accounting Method (FIFO, LIFO, and HIFO)
When you buy the same cryptocurrency at different times and prices, how do you know which specific coin you are selling? Tax regulators allow a few specific accounting methods to match your cost basis to your proceeds:
- FIFO (First-In, First-Out): Assumes the first coins you bought are the first ones you sell. This often results in higher capital gains if you bought early and cheap.
- LIFO (Last-In, First-Out): Assumes the most recently purchased coins are sold first. This can help minimize gains during a rising market.
- HIFO (Highest-In, First-Out): Sells the units with the highest cost basis first. This aggressive strategy minimizes your taxable gains as much as possible, provided you have clear records.
How to Fix Crypto Income Reporting and Properly File IRS Form 8949
Accurately reporting digital asset transactions requires meticulous record-keeping and correct form selection. According to IRS guidelines, every digital asset sale, trade, or conversion must be documented individually or summarized via specific aggregation rules.
Step-by-Step Reporting Procedure
- Compile transaction histories: Gather all CSV exports, API keys, and manual logs from every centralized exchange, decentralized finance protocol, and self-hosted wallet utilized throughout the 2026 tax year.
- Reconcile missing cost bases: Identify any crypto-to-crypto trades or airdrops missing historical acquisition data, calculating the fair market value in US dollars at the exact hour of receipt.
- Complete IRS Form 8949: List each distinct disposal separately in Part I (for short-term holdings under one year) or Part II (for long-term holdings exceeding one year), detailing the asset name, acquisition date, proceeds, cost basis, and resulting gain or loss.
- Transfer totals to Schedule D: Aggregate the final net short-term and long-term figures from Form 8949 and report them directly onto Schedule D of your Form 1040.
- Attach Form 8949 digitally: If filing electronically through commercial tax software, ensure Form 8949 data matches your attached PDF statements or is transmitted via the IRS MeF system.
What If Your Crypto Exchanges Fail to Provide Correct Tax Documents
Many centralized and decentralized platforms issue incomplete or entirely inaccurate 1099 forms. Relying on flawed exchange data can trigger automated IRS audits, as reporting discrepancies are easily flagged by matching algorithms.
Resolving Inaccurate Exchange Reporting
- Cross-reference with raw data: Download raw CSV files directly from the platform and compare transaction timestamps against your personal portfolio trackers.
- Override erroneous 1099 amounts: File your taxes using your independently calculated figures rather than the incorrect exchange-generated 1099, keeping a documented reconciliation statement on hand.
- Utilize crypto-specific tax software: Process your raw wallet addresses and exchange histories through specialized reconciliation software to override bad exchange data automatically.
- Request a corrected form: Contact exchange customer support to formally request a corrected 1099-B or 1099-DA, noting that resolution can take up to 30 business days during peak filing season.
What If It Still Doesn’t Work?
If manual reconciliation fails or your transaction volume exceeds standard software capabilities, targeted fallback measures are required to remain compliant with 2026 tax standards.
- Isolate problematic wallets: Quarantine complex liquidity pool transactions or smart contract interactions into a separate spreadsheet for manual blockchain explorer verification.
- Engage a Certified Public Accountant: Consult a CPA who holds a Certified Digital Asset Advisor (CDAA) designation or specialized blockchain credentials.
- Prepare for professional fees: Expect to pay between $500 and $3,000 depending on your transaction volume, multi-chain activity, and the complexity of your decentralized finance history.
- File for an extension: Submit Form 4868 by the April deadline to secure an automatic six-month extension, preventing hasty filing errors while you resolve complex data discrepancies.
Conclusion
Navigating 2026 crypto trading tax rules demands precision, thorough data aggregation, and strict adherence to IRS Form 8949 requirements. When exchanges fail to deliver accurate documentation, independent blockchain reconciliation safeguards you against costly reporting penalties. According to verified research and tax experts, proactive data cleanup throughout the year eliminates compliance risks. Take your next actionable step today by exporting your complete transaction history from every platform you utilize.
❓ Frequently Asked Questions
What constitutes a taxable event under current crypto tax rules?
Taxable events include selling cryptocurrency for fiat currency, trading one crypto asset for another, using crypto to purchase goods or services, and earning crypto through mining, staking, or airdrops.
How do I calculate the cost basis of my digital assets?
Cost basis is the total amount you paid for the cryptocurrency, including transaction fees and commissions, denominated in US dollars at the time of acquisition.
Which accounting methods does the IRS accept for crypto?
The IRS accepts specific identification methods such as FIFO (First-In, First-Out), LIFO (Last-In, First-Out), and HIFO (Highest-In, First-Out) provided you maintain consistent records.
How are crypto capital losses reported and used?
Capital losses from crypto trades can offset your capital gains. If your losses exceed your gains, you can deduct up to $3,000 of ordinary income per year.
Do I have to report crypto if I only bought it with USD and held it?
No, simply buying and holding cryptocurrency in your own wallet is not a taxable event and does not need to be reported until you dispose of it.
What happens if I fail to report my crypto transactions on my tax return?
Failing to report crypto transactions can result in IRS audits, back taxes, substantial underpayment penalties, and potential interest or legal consequences.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.