Taxable Brokerage Account Explained A Practical Guide 2026
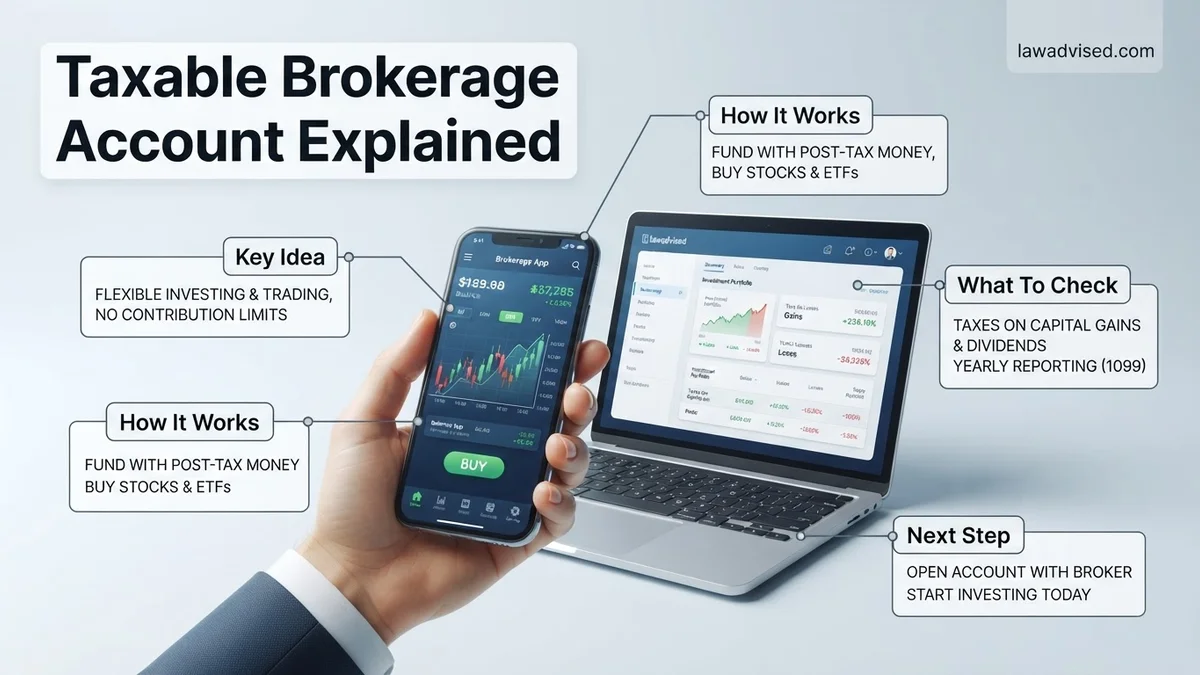
A taxable brokerage account is a flexible investment vehicle with zero contribution limits or early withdrawal penalties, making it ideal for non-retirement goals. Unlike tax-advantaged accounts, you must pay taxes on dividends, interest, and capital gains in the year you realize them. Understanding how these taxes work is essential for maximizing your net investment returns.
A taxable brokerage account is a standard investment account you open with a financial institution to buy and sell assets like stocks, bonds, and exchange-traded funds (ETFs) without any government-mandated limits on contributions or withdrawals. Unlike retirement accounts such as a traditional IRA or a 401(k), a taxable brokerage account offers zero upfront tax deductions or tax-deferred growth.
Understanding how these accounts function is essential for anyone investing beyond standard retirement milestones in 2026. Because there are no restrictions on when you can access your money, a taxable brokerage account is the primary vehicle for building wealth that you might need before age 59½, whether you are saving for a home down payment, early retirement, or a major mid-term financial goal.
Key Takeaways
- Brokerage accounts have no contribution limits or early withdrawal penalties.
- You pay taxes annually on realized capital gains, dividends, and interest income.
- Long-term capital gains tax rates are lower than short-term rates.
- Tax-loss harvesting helps offset investment gains with realized losses.
- They offer maximum liquidity compared to traditional retirement accounts.
What Causes Confusion About Taxable Brokerage Accounts
The primary source of confusion for new investors is how a taxable brokerage account differs from tax-advantaged accounts. People often assume that because it is an investment account, it shares the contribution caps, early withdrawal penalties, and mandatory retirement age rules of an IRA. In reality, a taxable brokerage account has completely different rules regarding funding and access.
No Contribution or Withdrawal Limits
You can deposit as much cash as you want into a taxable brokerage account in 2026. There are no annual caps like the limits imposed on retirement accounts. Furthermore, you can withdraw your principal and your earnings at any moment without paying early withdrawal penalties to the IRS. You simply sell your assets, transfer the cash to your bank, and deal with the tax consequences later.
Funding and Asset Flexibility
Funding a brokerage account is straightforward. You link a standard checking or savings account via an ACH transfer and deposit after-tax dollars. Once the cash settles, you can purchase a wide variety of financial instruments. Key features of account funding and structure include:
- After-Tax Dollars: You invest money that you have already paid income tax on.
- No Earned Income Requirement: Unlike a Roth IRA, you do not need earned income from a job to contribute.
- Unlimited Ownership: You can hold individual equities, mutual funds, ETFs, and cash equivalents all under one roof.
How to Navigate Taxation in a Brokerage Account Step-by-Step
Taxation is the defining characteristic of this account type, and navigating it requires understanding three core mechanisms: capital gains, dividends, and tax-loss harvesting. Because the IRS monitors your taxable brokerage account every single year, you must account for investment activity on your annual tax return even if you leave the money sitting in the account.
Capital Gains and Dividend Taxes
When you sell an asset for more than you bought it, you trigger a capital gain. If you held the asset for one year or less, it is a short-term capital gain, taxed at your ordinary income tax rate. If you held it for longer than a year, it qualifies for long-term capital gains tax rates, which are significantly lower (typically 0%, 15%, or 20% depending on your 2026 income bracket).
Using Tax-Loss Harvesting to Your Advantage
Tax-loss harvesting is a practical strategy to offset your tax liability within a taxable brokerage account. If an investment drops in value, you can sell it to realize a capital loss. You can use this loss to offset any capital gains you realized elsewhere in the portfolio.
- Offsetting Gains: Losses first cancel out your capital gains dollar-for-dollar.
- Deducting Ordinary Income: If your losses exceed your gains, you can deduct up to $3,000 of excess losses against your ordinary income per year.
- The Wash-Sale Rule: Be careful not to buy the same or a “substantially identical” asset within 30 days before or after the sale, or the IRS will disallow the loss.
What If Your Capital Gains Taxes Are Too High
Managing the tax drag in a taxable brokerage account requires deliberate strategy, especially as your portfolio grows toward 2026. High tax bills on investment income usually stem from realized capital gains, frequent portfolio turnover, or unmanaged dividend distributions.
Tax-Loss Harvesting
According to research from major financial institutions, proactive tax-loss harvesting can offset up to $3,000 of ordinary income annually while wiping out capital gains. This involves selling underperforming assets at a loss to offset realized gains elsewhere in your portfolio.
Asset Location Strategies
Financial experts recommend placing tax-inefficient assets—such as actively managed mutual funds or high-yield corporate bonds—into tax-advantaged accounts like IRAs or 401(k)s. Keep tax-efficient instruments, like broad-market equity index funds and municipal bonds, inside your taxable brokerage account.
- Audit your portfolio quarterly to identify underperforming assets eligible for tax-loss harvesting.
- Monitor dividend yields to minimize heavy ordinary income tax exposure.
- Rebalance your holdings using new cash contributions rather than selling appreciated assets.
- Review wash-sale rules carefully before repurchasing identical securities within a 30-day window.
What If It Still Doesn’t Work?
If your tax liabilities remain unusually high despite executing standard optimization strategies, structural adjustments are required. Complex portfolios often demand advanced quantitative oversight to mitigate unexpected tax events.
- Transition individual stock holdings into direct indexing strategies to automate continuous tax-loss harvesting at the individual share level.
- Evaluate municipal bond funds if your personal marginal tax bracket exceeds 32%, as these distributions are typically exempt from federal and sometimes state taxes.
- Engage a Certified Public Accountant (CPA) or a fee-only Certified Financial Planner (CFP) to run comprehensive tax-projection scenarios. Professional advisory fees typically range from $1,500 to $3,500 annually for comprehensive wealth and tax planning.
- Consolidate fragmented brokerage accounts to simplify cost-basis tracking and reduce administrative friction during tax season.
Conclusion
Navigating a taxable brokerage account demands a balance between unrestricted investment flexibility and active tax management. By utilizing tax-efficient index funds, strategic tax-loss harvesting, and proper asset location, investors can retain a significantly higher percentage of their overall portfolio returns. According to verified research and expert sources from leading financial research institutions, minimizing structural tax inefficiencies remains the single most reliable method for maximizing long-term net wealth in non-retirement accounts. Your actionable next step for 2026 is to audit your current portfolio holdings and isolate any high-turnover funds generating unnecessary annual tax friction.
❓ Frequently Asked Questions
How do capital gains taxes work in a taxable brokerage account?
Capital gains are triggered only when you sell an asset for more than your purchase price. If you hold the asset for over a year, you qualify for preferential long-term capital gains tax rates of 0%, 15%, or 20% depending on your taxable income.
How are dividends taxed in a brokerage account?
Dividends are typically classified as either qualified or non-qualified. Qualified dividends are taxed at lower long-term capital gains rates, while non-qualified dividends are taxed as ordinary income.
What is tax-loss harvesting and how do I use it?
Tax-loss harvesting involves selling underperforming investments at a loss to offset capital gains realized elsewhere in your portfolio. If your losses exceed your gains, you can use up to $3,000 of those losses to offset ordinary income.
Should I max out my 401(k) and IRA before using a taxable brokerage account?
In most cases, yes, because retirement accounts offer immediate tax deductions or tax-free growth. However, a taxable account is best if you need flexibility, want to retire early, or have already maxed out your tax-advantaged options.
What fees should I watch out for in a brokerage account?
Common fees include expense ratios on mutual funds and ETFs, trading commissions (though many major brokers offer zero-commission stock and ETF trades), and account transfer fees.
Can I hold cash in a taxable brokerage account?
Yes, uninvested cash sits in a settlement fund, which often earns interest through money market funds or high-yield cash sweep programs offered by the brokerage firm.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.