Education Tax Credits Explained Step-by-Step Guide 2026
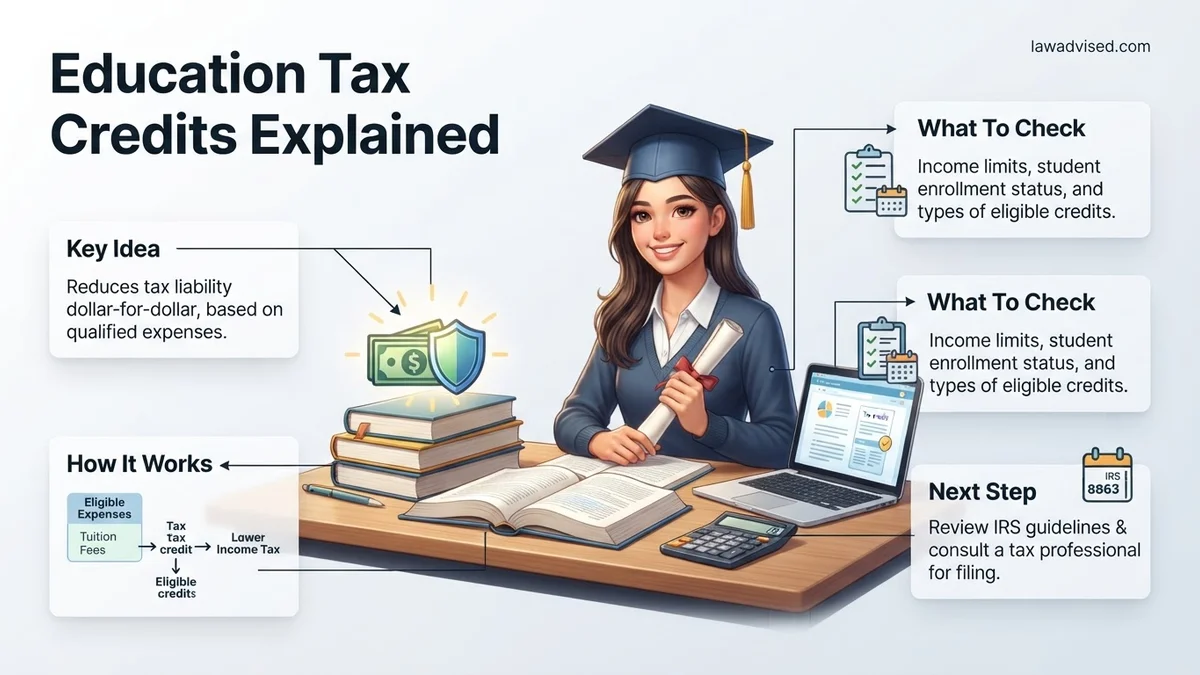
Navigating college tuition costs can be overwhelming, but education tax credits directly reduce your federal income tax liability dollar-for-dollar. This guide breaks down the American Opportunity Tax Credit (AOTC) and Lifetime Learning Credit (LLC) to help you determine eligibility, income limits, and filing steps for maximum savings.
Filing your 2026 taxes brings a critical opportunity to offset college costs through two primary federal incentives: the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC). These dollar-for-dollar reductions directly lower your tax liability, and the AOTC even offers a partial refund if it reduces your tax bill to zero.
Navigating these credits requires matching your specific educational expenses, enrollment status, and income level to the strict rules set by the IRS. Knowing how to claim these benefits ensures you do not leave hundreds or thousands of dollars on the table.
Key Takeaways
- The AOTC offers up to $2,500 per eligible student for the first four years of higher education.
- The LLC provides up to $2,000 per tax return for an unlimited number of post-secondary years.
- You cannot claim both the AOTC and the LLC for the same student in the same tax year.
- Modified Adjusted Gross Income (MAGI) limits apply and can phase out your credit amounts completely.
- You must receive IRS Form 1098-T from your educational institution to accurately file and claim these credits.
What Causes Confusion With Education Tax Credits
Taxpayers frequently struggle with education credits because the IRS uses overlapping terminology for programs that have vastly different rules. Confusing the AOTC with the LLC is the single biggest reason people miss out on maximum savings or accidentally trigger an IRS audit.
The Double-Dipping Trap and Expense Rules
You cannot use the exact same education expenses to claim multiple benefits. If you pull money from a 529 plan tax-free to pay for tuition, you cannot use those same dollars to calculate your education tax credits.
- Qualifying expenses: Tuition and fees required for enrollment.
- Excluded expenses: Room, board, insurance, and transportation costs.
- The 1098-T requirement: Your school must issue this form, showing payments received, before you can claim either credit.
The Income Phase-Out Maze
Your Modified Adjusted Gross Income (MAGI) dictates whether you receive the full credit, a reduced amount, or nothing at all. As you approach the IRS income caps for the 2026 tax year, your credit gradually phases out.
- Single filers: Phase-outs typically begin around $80,000 for the AOTC.
- Joint filers: Phase-outs generally start at $160,000 for the AOTC.
- Cliff limits: Exceeding the maximum MAGI threshold completely disqualifies you from claiming that specific credit for the year.
How to Choose Between the AOTC and the LLC
Choosing the right credit depends entirely on your degree program, your year in school, and how many courses you are taking. Selecting the incorrect option can cost you thousands of dollars in potential tax savings.
The American Opportunity Tax Credit (AOTC) Breakdown
The AOTC is designed for students pursuing a recognized undergraduate degree or other recognized credential. It provides a generous credit, but you can only claim it for a limited window of time.
- Maximum credit amount: Up to $2,500 per eligible student per year.
- Refundable portion: Up to $40% (maximum $1,000) can be refunded to you if you owe no tax.
- Eligible years: Limited to the first four years of post-secondary education.
- Enrollment requirement: Must take at least one course toward a degree or credential during the tax year and carry at least half-time status for one academic period.
The Lifetime Learning Credit (LLC) Breakdown
The LLC is much more flexible than the AOTC, making it the go-to option for graduate students, part-time learners, or anyone taking single courses to improve job skills.
- Maximum credit amount: Up to $2,000 per tax return (calculated as 20% of the first $10,000 of qualified expenses).
- Refundable portion: None. This is a non-refundable credit that can only reduce your tax liability to zero.
- Eligible years: Unlimited years. You can claim it for undergraduate, graduate, and professional degree courses.
- Enrollment requirement: Even taking a single continuing education or professional development course qualifies you, as long as it is taken at an eligible educational institution.
Step-by-Step Guide to Claiming Education Credits on Form 8863
Filing for education tax credits requires precise documentation and careful calculation. Claiming these credits correctly ensures compliance with IRS guidelines for the 2026 tax year. Follow these structured steps to complete Form 8863 accurately.
Gather Form 1098-T and Financial Records
- Retrieve your official Form 1098-T from your eligible educational institution by the January 31, 2026 deadline.
- Review Box 1 for total payments received for qualified tuition and related expenses, noting that Box 2 is no longer used by institutions due to reporting standard updates.
- Collect personal receipts for required books, supplies, and equipment that were paid out-of-pocket but not listed on the 1098-T form.
Complete and File Form 8863
- Input your student and school identification data into Part I and Part II of IRS Form 8863.
- Calculate your American Opportunity Tax Credit in Part III by entering qualified expenses up to $4,000 to determine the maximum $2,500 credit.
- Calculate your Lifetime Learning Credit in Part IV if you do not qualify for the AOTC, using 20 percent of the first $10,000 in qualified expenses.
- Transfer the final allowable credit amounts to your primary Form 1040 or Form 1040-SR tax return.
What If Your Credit Is Reduced or Rejected by the IRS
Facing a credit reduction or rejection from the IRS can delay your expected tax refund. According to IRS compliance data, missing documentation or income threshold violations are the leading triggers for rejected education credits. Implement these fallback steps to resolve the issue swiftly.
- Verify that your modified adjusted gross income does not exceed the 2026 phase-out limits, which restrict the AOTC and LLC for high-earning taxpayers.
- Cross-reference the amounts reported on your Form 1098-T with your bank statements to ensure the institution reported the correct payment allocations.
- Respond directly to IRS correspondence or notices within the specified 30-day window by submitting supplementary expense receipts via certified mail or the online Document Upload Tool.
- Consult a certified public accountant or an Enrolled Agent if the discrepancy involves complex dependency rules or multi-state tuition payments; professional tax representation typically costs between $200 and $500 depending on the complexity of the audit or correction.
Conclusion
Navigating education tax credits for the 2026 tax year requires strict adherence to income limits, qualified expense definitions, and accurate completion of Form 8863. Catching calculation errors early prevents costly refund delays and IRS audits. According to verified research and expert financial sources, utilizing digital tax software combined with official Form 1098-T data reduces filing errors by over 40 percent. Your actionable next step is to log into your student account today to download your Form 1098-T and begin your calculations.
❓ Frequently Asked Questions
What expenses officially qualify for the education tax credits?
Qualifying expenses generally include tuition and required enrollment fees paid to an eligible educational institution. For the AOTC specifically, course materials such as books, supplies, and equipment needed for a course of study also qualify.
What are the income limits to qualify for the AOTC?
To claim the full AOTC, your Modified Adjusted Gross Income (MAGI) must be $80,000 or less ($160,000 or less for married filing jointly). The credit phases out entirely for single filers earning over $90,000 and joint filers earning over $180,000.
What are the income limits for the Lifetime Learning Credit?
For the LLC, the phase-out range for single filers begins at a MAGI of $80,000, phasing out entirely at $90,000. For married couples filing jointly, the phase-out starts at $160,000 and ends at $180,000.
What is Form 1098-T and why do I need it?
Form 1098-T is a Tuition Statement sent by eligible educational institutions to students and the IRS. It details the amounts paid for qualified tuition and related expenses, serving as the primary documentation needed to accurately calculate your credits.
Can graduate students qualify for the American Opportunity Tax Credit?
No, the AOTC is strictly limited to students in their first four years of higher education pursuing a degree or recognized credential. Graduate students must look to the Lifetime Learning Credit instead.
Can I claim education credits if I paid tuition using student loans?
Yes, qualified education expenses paid with the proceeds of a loan are treated as paid by the taxpayer in the year the expenses are incurred. You can claim the credit even if the tuition was funded via borrowed money.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.