Benefits of Married Filing Jointly The Best Tax Guide 2026
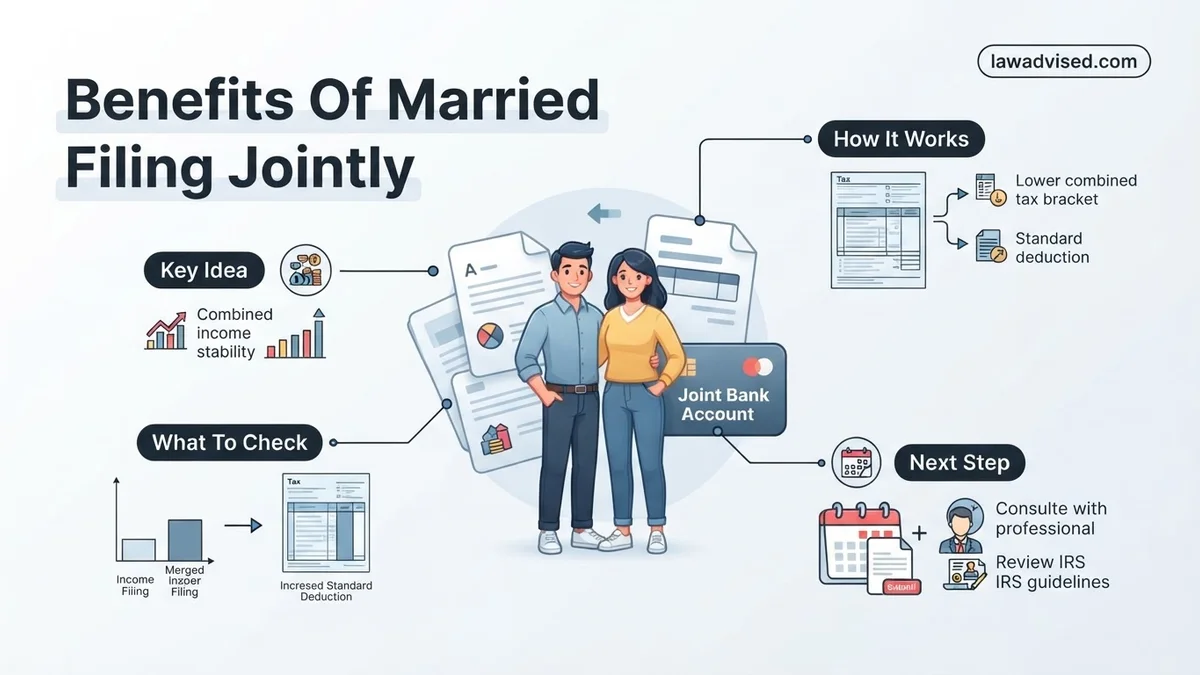
Choosing the right tax status is critical for maximizing your household income. Married Filing Jointly offers significantly higher standard deductions, broader tax brackets, and exclusive access to valuable tax credits that separate filers simply miss out on. Reviewing these distinct financial advantages ensures you keep more of your hard-earned money.
Choosing the Married Filing Jointly (MFJ) status on your tax return consistently unlocks much larger tax savings and financial benefits than filing separate returns. The primary advantages include significantly higher standard deductions, wider tax brackets, and eligibility for valuable federal tax credits that are completely restricted if you choose to file separately.
Navigating the 2026 tax landscape requires understanding why the federal tax code heavily favors joint returns. For the vast majority of married couples, combining your incomes and deductions under one joint return creates a much lower overall tax liability, leaving more money in your household budget.
Key Takeaways
- Joint filers enjoy a standard deduction that is precisely double the single filing amount.
- Wider tax brackets protect dual-income households from hitting higher marginal rates prematurely.
- Filing jointly unlocks valuable credits like the Earned Income Tax Credit and Child Tax Credit.
- Education tax credits feature higher income phase-out thresholds for joint filers.
- Both spouses share joint and several liability for the accuracy of the tax return.
What Causes Lower Tax Refunds When Couples File Separately
Filing as Married Filing Separately (MFS) often feels like a safe way to keep finances independent, but the tax code penalizes this choice heavily. When you split your tax returns, you slam the door on numerous deductions and credits designed to lower household tax burdens.
Loss of Lucrative Tax Credits
The penalty for filing separately hits hardest through the loss of major tax credits. If you use the MFS status:
- You completely lose eligibility for the Earned Income Tax Credit (EITC).
- You cannot claim the Child and Dependent Care Credit in most circumstances.
- You lose access to the American Opportunity Tax Credit and Lifetime Learning Credit for higher education expenses.
- Your income phase-out thresholds for child tax credits are cut in half.
Restricted Deductions and Income Thresholds
Beyond losing credits, separate filers face aggressive income restrictions. For example, the deduction for student loan interest phases out at much lower individual income limits. Additionally, if one spouse itemizes deductions, the other spouse is forced to itemize as well, even if their personal itemized deductions are zero. This structural rigidity almost always results in a higher combined tax bill and a drastically lower tax refund.
How to Maximize Savings Using Married Filing Jointly Status
Filing a joint return unleashes the full power of the federal tax code to lower your taxable income. By merging your financial profiles, you immediately benefit from doubled threshold limits and optimized tax brackets for 2026.
Doubled Standard Deductions
The standard deduction for married couples filing jointly is exactly double the amount allowed for single filers. For the 2026 tax year, this substantial deduction shields a massive portion of your combined household income from federal taxation before you even begin applying deductions or credits. This simple mechanism reduces your adjusted gross income (AGI) right out of the gate.
Wider Tax Brackets for Combined Income
Tax brackets for joint filers are significantly wider than single brackets, which protects dual-income households from hitting higher marginal tax rates too quickly.
- Income thresholds for lower tax brackets (such as the 10%, 12%, and 22% brackets) stretch much further for couples.
- This prevents the “marriage penalty” in tax brackets, ensuring that two modest incomes combined do not instantly trigger a higher tax bracket than they would face individually.
- Capital gains thresholds also scale favorably, allowing you to pay lower long-term capital gains rates on investment returns.
Step-by-Step Guide to Calculating Your Joint Tax Brackets
Calculating your married filing jointly tax bracket for 2026 requires understanding how the IRS applies progressive tax rates to combined household income. Financial planning experts recommend following a structured mathematical process to determine your exact tax liability before submitting your return.
Step 1: Determine Your Combined Gross Income
First, compile all W-2s, 1099s, and investment income statements for both spouses. Add these gross figures together to establish your total household income for the 2026 tax year. According to IRS guidelines, joint filers must report all worldwide income regardless of which spouse earned it.
Step 2: Subtract the Standard Deduction
Next, subtract the applicable standard deduction from your combined gross income to find your taxable income. For the 2026 tax year, the married filing jointly standard deduction is indexed for inflation, providing a significantly higher shelter than single filing statuses. If either spouse is over 65 or blind, remember to add the additional standard deduction amount.
Step 3: Apply the 2026 Joint Tax Brackets
Finally, apply the progressive tax bracket thresholds specifically designated for married couples filing jointly. Because the income thresholds for each tax bracket are roughly double those of single filers, couples avoid the severe ‘marriage penalty’ that historically affected dual-income households.
- Calculate income falling into the lowest marginal bracket (10%) and record the tax owed.
- Move up sequentially through the 12%, 22%, 24%, 32%, 35%, and top 37% brackets as applicable.
- Sum the tax calculated across all tiers to determine your total baseline income tax liability before credits.
What If It Still Doesn’t Work and You Need Innocent Spouse Relief
Sometimes filing a joint return creates unexpected liabilities due to a spouse’s unreported income or erroneous deductions. If you face tax debt or penalties stemming entirely from your partner’s actions on a joint return, standard filing protections may not suffice. Tax attorneys and certified public accountants recommend exploring specific statutory relief options.
- Verify your eligibility for Innocent Spouse Relief under IRC Section 6015(b) if you had no knowledge of the understatement when signing the 2026 return.
- Consider Separation of Liability relief if you are divorced, legally separated, or have lived apart from your spouse for at least 12 months.
- Request Equitable Relief if you do not qualify for the first two options but holding you liable would be fundamentally unfair.
- Consult a qualified tax professional or Low Income Taxpayer Clinic (LITC) to file IRS Form 8857 correctly. Professional fees for filing relief claims typically range from $1,500 to $3,500 depending on complexity.
Conclusion
Filing your taxes as married filing jointly in 2026 unlocks substantial financial advantages, including wider tax brackets, enhanced deductions, and valuable credits. By accurately calculating your combined income and leveraging statutory protections when necessary, you can optimize your household tax strategy. According to verified research and expert financial sources, utilizing joint filing correctly saves American families thousands of dollars annually. Your next actionable step is to gather all income documents and run your 2026 projections through reputable tax software before the April deadline.
❓ Frequently Asked Questions
What are the primary financial benefits of married filing jointly?
Joint filers receive double the standard deduction of single filers, access to wider tax brackets, and eligibility for exclusive credits such as the Child Tax Credit and EITC.
How do tax brackets differ between joint and separate filing?
Joint filing brackets are designed to prevent the marriage penalty by providing income thresholds that are more than double the single rates, protecting dual incomes.
What is joint and several liability?
This IRS rule means both spouses are legally responsible for the entire tax debt, interest, and penalties due on a joint return, even if only one earned the income.
Can newly married couples file jointly for the entire year?
Yes, as long as your marriage is legally recognized by December 31 of the tax year, the IRS treats you as married for the full twelve months.
Does filing jointly affect student loan repayment plans?
Income-driven repayment plans often factor in joint income when calculating monthly payments, which can sometimes increase your monthly student loan bill.
When is married filing separately actually recommended?
Couples might choose separate status to manage immense medical debt deductions or to protect themselves from a spouse’s questionable tax practices.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.