Medical Expense Deduction Explained A Step-by-Step 2026
Navigating the medical expense deduction requires itemizing your taxes and ensuring your total qualified costs exceed 7.5% of your Adjusted Gross Income (AGI). Only the portion that surpasses this strict threshold can actually be deducted from your taxable income. Proper record-keeping is essential to legally claim these out-of-pocket medical costs on your tax return.
You can deduct unreimbursed medical expenses on your 2026 federal income taxes only if your total qualifying costs exceed 7.5 percent of your Adjusted Gross Income (AGI). To claim this tax break, you must choose to itemize your deductions using Schedule A instead of taking the standard deduction.
Navigating this tax rule requires knowing exactly which expenses clear the IRS hurdle and how to run the numbers. If your out-of-pocket healthcare costs are piling up due to chronic conditions, unexpected surgeries, or high insurance premiums, understanding this threshold can save you thousands of dollars.
Key Takeaways
- You must itemize deductions on Schedule A to claim medical expenses.
- Only medical expenses exceeding 7.5% of your AGI are deductible.
- Insurance premiums paid with after-tax dollars qualify as medical expenses.
- Cosmetic procedures and general health items generally do not qualify.
- Keep meticulous receipts and mileage logs for all medical travel.
What Causes High Medical Expenses to Qualify for Deductions
To make the medical expense deduction worth your time, your cumulative costs need to punch through a strict IRS percentage floor. The rules dictate what you can and cannot count toward that total.
The 7.5 Percent AGI Hurdle Explained
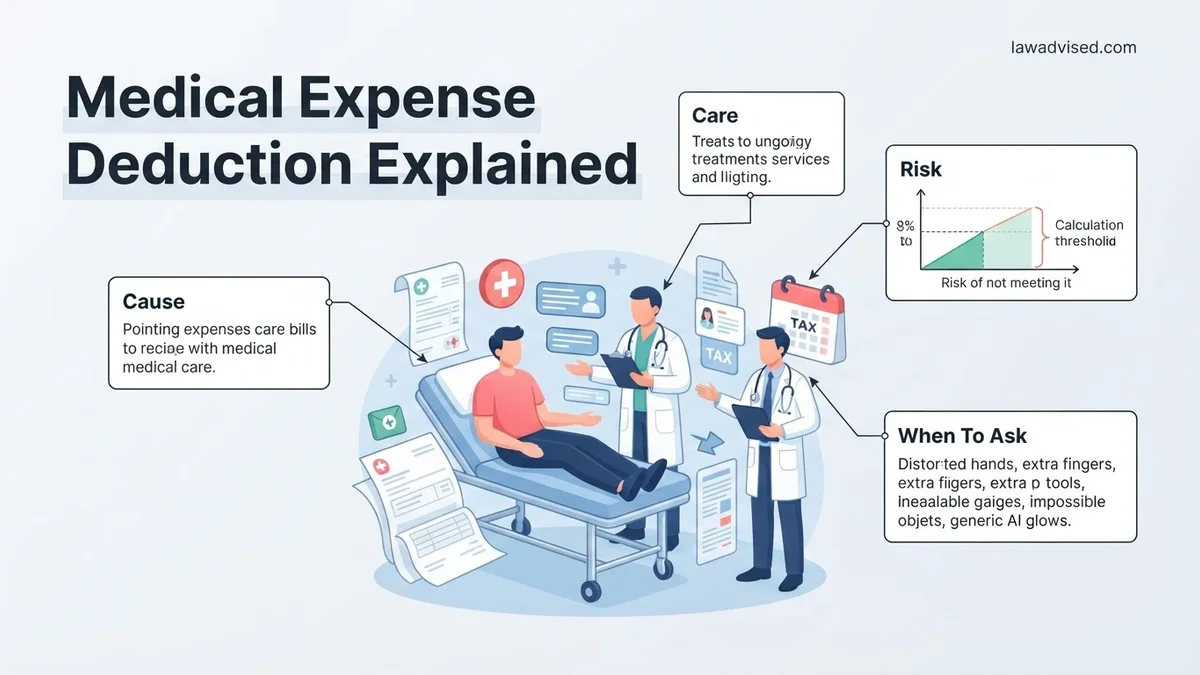
The biggest obstacle to claiming this deduction is the 7.5 percent adjusted gross income floor. Only the portion of your medical expenses that goes beyond 7.5 percent of your AGI is deductible. If your AGI for 2026 is $80,000, your threshold is $6,000. Any qualifying medical spending above that $6,000 mark is what you actually deduct. If your total expenses equal $7,500, your final deduction amount is just $1,500.
What the IRS Allows vs. Excludes
You cannot write off every single health-related purchase you make during the year. The IRS maintains strict guidelines on eligible expenses.
- Allowed: Prescription medications, doctor visits, hospital care, dental treatments, eyeglasses, physical therapy, and long-term care insurance premiums.
- Allowed: Medical travel expenses, including mileage for driving to appointments or public transportation costs tied to healthcare.
- Excluded: Cosmetic procedures, gym memberships for general wellness, over-the-counter vitamins, and teeth whitening treatments.
- Excluded: Any medical expenses that were paid for or reimbursed by your health insurance or a flexible spending account (FSA).
How to Calculate and Claim Your Medical Expense Deduction Step-by-Step
Crunching the numbers correctly ensures you maximize your tax savings without triggering an audit. Follow a structured approach to gather your receipts and file accurately.
Step 1: Gather and Tally All Eligible Expenses
Collect every receipt, billing statement, and insurance statement of benefits from the 2026 tax year. Separate out anything that was reimbursed by your insurance provider or paid using pre-tax dollars from a Health Savings Account (HSA) or FSA. Add up what is left.
- Include out-of-pocket copays and deductibles.
- Include specialized equipment like wheelchairs or prescribed home modifications.
- Include health insurance premiums you paid directly with after-tax money.
Step 2: Compare Your Total Against Your AGI
Take your projected or final 2026 Adjusted Gross Income and multiply it by 0.075. Compare that number to your total eligible medical expenses. If your total medical expenses are lower than that figure, you will not qualify to itemize for medical costs. If your expenses are higher, subtract the threshold amount from your total expenses to find your actual deduction.
Step 3: Complete Schedule A and File
To claim the deduction, you must complete IRS Form 1040 and attach Schedule A (Itemized Deductions). Enter your total qualified medical expenses on Line 1, input your AGI on Line 2, and enter the final allowable deduction on Line 4. Remember that itemizing only makes sense if your total itemized deductions—combining medical, state and local taxes, and charitable donations—exceed the 2026 standard deduction for your filing status.
What If Your Medical Expenses Fall Below the 7.5% AGI Threshold
Falling short of the 7.5% Adjusted Gross Income threshold is a common frustration for taxpayers attempting to claim the medical expense deduction in 2026. When your total qualified expenses do not clear this statutory hurdle, the entire deduction is lost on standard individual returns. Strategic tax planning requires understanding alternative pathways to utilize medical expenditures before the calendar year closes.
Bunching Your Medical Expenses
To overcome the 7.5% barrier, financial advisors frequently recommend a strategy known as expense bunching. By consolidating elective procedures, dental work, and medical device purchases into a single tax year, you concentrate your spending to exceed the AGI floor.
- Schedule non-emergency procedures, such as Lasik surgery or major dental restorations, within the same calendar year.
- Prepay for upcoming treatments or order necessary long-term medical supplies before December 31, 2026.
- Coordinate the timing of elective surgeries with years where your income temporarily drops, lowering your overall AGI threshold.
Alternative Tax-Advantaged Accounts
If your aggregated expenses ultimately fail to surpass the 7.5% AGI requirement, alternative tax vehicles provide immediate relief without relying on itemization. Health Savings Accounts and Flexible Spending Accounts allow pre-tax dollar contributions for identical qualified medical expenses.
- Maximize your Health Savings Account contributions for 2026, which offer an immediate above-the-line deduction regardless of itemization.
- Utilize an employer-sponsored Flexible Spending Account to pay for predictable out-of-pocket healthcare costs with pre-tax earnings.
- Review state-level tax deductions, as several states maintain lower AGI percentage thresholds than the federal standard for medical expense write-offs.
What If It Still Doesn’t Work?
If your calculated medical expenses remain stubbornly below the threshold and alternative funding strategies are exhausted, you must pivot your tax strategy. When standard itemization fails to yield a financial benefit, consider the following fallback steps:
- Take the Standard Deduction: Verify whether taking the 2026 standard deduction surpasses your total itemized deductions, which simplifies filing and often yields a higher refund.
- Consult a Certified Public Accountant: Schedule a consultation with a licensed tax professional to review complex, multi-year medical scenarios and potential state-level deductions. Professional tax preparation fees typically range from $250 to $600 depending on complexity.
- Audit Your Expense Categorization: Re-examine your compiled receipts against the official IRS Publication 502 to ensure no overlooked items—such as transportation for care or specialized home modifications—were omitted.
- Plan for Future Years: Establish a medical tracking system early in the upcoming tax cycle to identify bunching opportunities well before the end of the fiscal year.
Conclusion
Navigating the medical expense deduction requires careful calculation of your Adjusted Gross Income and rigorous tracking of qualified healthcare outlays against the 7.5% threshold. When expenses fall short, strategic bunching or utilizing pre-tax accounts prevents financial loss. According to verified research and tax experts from the American Institute of CPAs, proactive year-round documentation remains the most effective defense against missed deductions. Your immediate next step is to audit your year-to-date medical receipts and calculate your current AGI percentage to determine if expense bunching is viable before December 31, 2026.
❓ Frequently Asked Questions
How do I calculate the 7.5% AGI threshold for my medical expenses?
Multiply your total Adjusted Gross Income by 0.075. If your total qualified out-of-pocket medical expenses exceed that number, you can deduct the difference between your expenses and that threshold amount.
What common medical and dental expenses qualify for the deduction?
Qualifying costs include payments to doctors, dentists, surgeons, and chiropractors, as well as inpatient hospital care, prescription drugs, eyeglasses, hearing aids, and qualified nursing services.
Are cosmetic procedures ever considered deductible medical expenses?
Generally, cosmetic procedures like face lifts or teeth whitening do not qualify because they are not medically necessary. However, procedures required to correct a deformity from a congenital defect, injury, or disease are deductible.
What tax form is required to claim the medical expense deduction?
You must file IRS Form 1040 and attach Schedule A (Itemized Deductions) to report your medical and dental expenses alongside other itemized deductions like mortgage interest and state taxes.
Can I deduct medical expenses that were reimbursed by insurance?
No, you can only deduct unreimbursed medical expenses that you paid out of pocket during the tax year. Any expenses covered by insurance or health reimbursement arrangements must be excluded.
What records should I keep to substantiate my medical deductions?
Keep all itemized receipts, bills from healthcare providers, pharmacy statements, and a detailed mileage log tracking travel to and from medical appointments in case the IRS audits your return.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.