Adjusted Gross Income Explained Step-by-Step Guide for 2026
Adjusted Gross Income (AGI) is your total gross income minus specific above-the-line deductions. It serves as the critical baseline the IRS uses to determine your taxable income, tax bracket, and eligibility for credits.
Adjusted Gross Income, or AGI, is your total taxable income minus specific adjustments known as above-the-line deductions. This single number serves as the baseline the IRS uses to determine your ultimate tax liability, your eligibility for valuable tax credits, and whether you qualify for specific deductions for the 2026 tax year.
You need to know your AGI because it acts as the gateway for your entire tax return. Many tax breaks, from child tax credits to medical expense deductions, phase out based entirely on this specific figure. Getting your AGI calculation right prevents costly processing delays and ensures you do not miss out on money you legally deserve.
Key Takeaways
- AGI equals your total gross income minus specific allowable above-the-line deductions.
- Gross income includes wages, business earnings, interest, dividends, and capital gains.
- Above-the-line deductions lower your AGI without requiring itemized deductions.
- Common deductions include student loan interest, HSA contributions, and retirement plan payments.
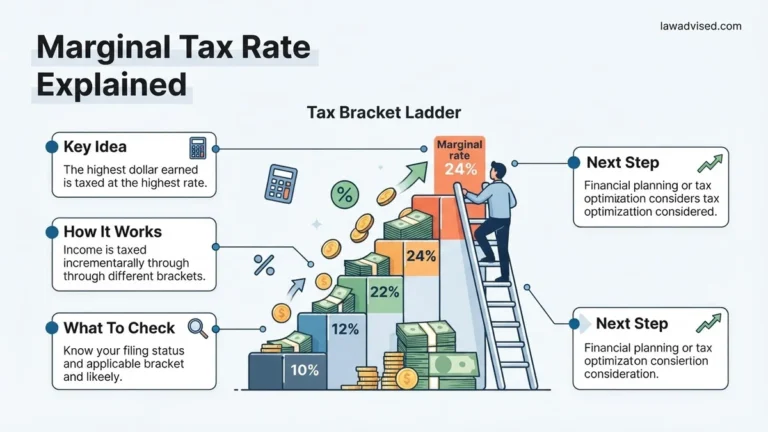
- Your AGI dictates your tax bracket and limits for many valuable tax credits.
What Causes Confusion in Calculating Adjusted Gross Income
Total Income Versus Gross Income
People frequently confuse gross income with total income, leading to errors right at the start of their tax preparation. Gross income includes every dollar you earn, but tax rules treat different streams of income with unique reporting requirements for 2026. Your salary, freelance earnings, rental income, and investment dividends all lump together into this initial pool before any deductions apply.
Above-the-Line Versus Below-the-Line Deductions
The biggest hurdle in understanding AGI is separating deductions that lower your AGI from those that do not. Above-the-line deductions directly reduce your gross income to arrive at your AGI. Below-the-line deductions, such as the standard deduction or itemized deductions, happen after your AGI is already calculated. Mixing these two categories up will throw off your entire financial picture.
Master Adjusted Gross Income in 6 Simple Steps
Adjusted gross income (AGI) forms the foundation of your entire tax return, acting as the crucial dividing line between everything you earned and what the government can actually tax. Whether you are preparing to file your annual taxes, applying for income-driven student loan repayment, or trying to qualify for specific healthcare subsidies, calculating and understanding your AGI is an essential financial skill. This practical walkthrough will take you through the exact process of identifying, calculating, and optimizing your AGI so you can keep more of your hard-earned money and avoid costly reporting mistakes.
Step 1: Gather All Gross Income Sources
What you need: W-2 forms from employers, 1099 forms for freelance or contract work, investment statements, and records of any other income.
Instructions: Your journey to finding your AGI begins by compiling every single dollar of taxable income you received during the calendar year. This gross income encompasses more than just your standard salary or hourly wages. You must systematically account for tips, business income, capital gains from selling stocks or property, rental income, unemployment benefits, pensions, interest, and dividends. Pull up your digital files or gather your paper tax documents, and create a master list. Sum up all these various revenue streams to establish your total gross income figure. Missing even a single 1099 form can trigger an automated flag and delay from the IRS, so leave no stone unturned.
Pro Tip: Keep a running digital spreadsheet year-round to track miscellaneous income like side hustles or investment dividends, saving you hours of frantic searching during tax season.
Step 2: Differentiate Between Gross Income and AGI
What you need: A basic understanding of tax terminology and last year’s tax return for reference.
Instructions: It is vital to understand the fundamental math equation that drives your taxes: Gross Income minus Above-the-Line Deductions equals AGI. While gross income is your total earnings before any deductions, AGI is a much smaller, more taxpayer-friendly number. The IRS uses AGI to determine your eligibility for numerous tax credits, deductions, and government programs. By subtracting specific allowable adjustments from your gross income, you effectively lower your tax liability. Recognize that AGI is calculated before you choose between taking the standard deduction or itemizing, meaning anyone can take advantage of these adjustments regardless of how they file.
Pro Tip: Do not confuse AGI with your Modified Adjusted Gross Income (MAGI), which is your AGI with certain deductions added back in for specific programs like Roth IRAs or health insurance subsidies.
Step 3: Identify Your “Above-the-Line” Deductions
What you need: IRS Form 1040, receipts, and deduction eligibility documents (such as student loan interest statements).
Instructions: Now that you have your total gross income, you need to hunt for your adjustments to income, formally known as above-the-line deductions. These are specific expenses the IRS allows you to subtract directly from your gross income to arrive at your AGI. Common adjustments include eligible educator expenses, student loan interest payments (up to $2,500), contributions to a traditional Individual Retirement Account (IRA), health savings account (HSA) contributions, self-employment tax deductions, and early withdrawal penalties on savings. Review IRS Schedule 1 of Form 1040 to check the complete, current list of available adjustments and match them against your annual expenses and financial contributions.
Pro Tip: You can claim above-the-line deductions even if you take the standard deduction, making them some of the most powerful tax-saving tools available to everyday filers.
Step 4: Calculate Your Preliminary AGI
What you need: A calculator or tax software, your gross income total, and your total above-the-line deductions.
Instructions: With your gross income total established in Step 1 and your validated adjustments gathered in Step 3, you are ready to perform the core mathematical calculation. Take your total gross income and subtract the sum of all your qualified adjustments to income. The resulting number is your Adjusted Gross Income. Double-check your arithmetic to ensure complete accuracy. For example, if you earned $70,000 in gross salary and made a $4,000 deductible contribution to an HSA along with $1,000 in student loan interest payments, your total adjustments equal $5,000, leaving you with an AGI of $65,000.
Pro Tip: Most modern tax software automates this subtraction for you, but manually calculating it first acts as a foolproof audit against software entry errors.
Step 5: Review for Accuracy and Omissions
What you need: Your completed preliminary AGI calculation and your primary tax forms (W-2s, 1099s, 1098-Es).
Instructions: Before locking in your numbers, conduct a thorough audit of your calculation. Compare the income figures you used against the exact numbers reported to the IRS by your employers and financial institutions. If your reported AGI does not match the information the IRS receives electronically, it will almost certainly trigger a processing delay or a matching notice. Verify that every deduction you claimed is fully supported by documentation, such as Form 1098-E for student loan interest or contribution receipts for your IRA and HSA accounts. Ensure that you have not double-counted any deductions or miscategorized any income streams.
Pro Tip: If you filed jointly with a spouse, ensure that both partners’ incomes and individual adjustments are fully accounted for in the final combined AGI figure.
Step 6: Leverage Your AGI for Financial Planning
What you need: Your finalized AGI figure and current-year IRS tax bracket and credit threshold charts.
Instructions: Your AGI is not just a tax-season formality; it is a vital metric for year-round financial planning. Look up your AGI against current IRS guidelines to see which tax bracket you fall into and what tax credits (like the Earned Income Tax Credit or Child Tax Credit) you qualify for. If your AGI is slightly too high to qualify for a specific deduction, Roth IRA contribution window, or subsidy, use the remaining months of the year to lower it proactively. You can strategically reduce your future AGI by increasing pre-tax retirement contributions, maximizing your HSA deposits, or utilizing flexible spending accounts (FSAs) through your employer.
Pro Tip: Review your paystubs mid-year to estimate your annual AGI, allowing you to adjust your withholding or retirement contributions before December 31.
✅ Final Checklist
- All gross income sources (W-2s, 1099s, investment dividends) are fully accounted for.
- Above-the-line deductions (HSA, student loan interest, IRA contributions) are verified with proper documentation.
- Gross income minus adjustments math has been double-checked for complete mathematical accuracy.
- AGI figure matches or accounts for all electronically filed third-party tax documents sent to the IRS.
- Final AGI number has been evaluated against target thresholds for tax credits and deductions.
Important Notes:
- Ensure you maintain receipts and tax documentation for at least three years in case of an IRS inquiry.
- Seek guidance from a Certified Public Accountant (CPA) or licensed tax professional if you have complex self-employment, rental, or international income.
- Calculating AGI typically takes 1 to 3 hours depending on the complexity of your financial portfolio, with zero direct monetary cost if calculated manually or via free IRS filing tools.
How to Calculate Your AGI Step-by-Step
The Exact AGI Formula
Calculating your Adjusted Gross Income for 2026 follows a strict, straightforward mathematical formula set by the IRS. You start with your total gross income and subtract eligible adjustments. Common deductions that get subtracted at this stage include:
- Traditional IRA contributions you made for the tax year
- Eligible student loan interest payments up to the annual limit
- Health Savings Account (HSA) contributions
- Self-employed health insurance premiums and retirement plan contributions
A Practical Numeric Example for 2026
Imagine your gross income for 2026 sits at $75,000 from your primary job, plus an additional $5,000 from freelance consulting work, giving you a total gross income of $80,000. During the year, you made a $3,000 contribution to a traditional IRA and paid $1,000 in qualifying student loan interest. Your calculation looks like this:
- Start with total gross income of $80,000
- Subtract your $3,000 IRA contribution
- Subtract your $1,000 student loan interest
- Your final Adjusted Gross Income equals $76,000
How to Leverage Above-the-Line Deductions to Lower Your AGI
Above-the-line deductions are your primary defense for actively reducing your Adjusted Gross Income for the 2026 tax year. These adjustments lower your taxable baseline without requiring you to itemize your deductions. Strategic taxpayers use these adjustments to unlock income-sensitive phase-outs and tax credits.
Key Adjustments to Target
- Traditional IRA Contributions: You can deduct contributions up to annual IRS limits if you or your spouse lack a workplace retirement plan. This directly strips dollars off your gross total.
- Student Loan Interest: Taxpayers can deduct up to $2,500 of interest paid on eligible student loans annually. This deduction applies even if you take the standard deduction.
- Health Savings Account (HSA) Contributions: Contributions to an HSA are 100 percent tax-deductible. For 2026, maximizing these deposits creates an immediate downward adjustment to your income.
- Self-Employment Taxes: Self-employed individuals deduct half of their self-employment tax directly from gross income. This shields business owners from heavy tax burdens before standard calculations begin.
What If Your AGI Disqualifies You from Tax Credits
Exceeding income limits for major credits like the Child Tax Credit or premium tax credits creates immediate financial pain. When your AGI crosses statutory thresholds, valuable benefits phase out entirely. Fortunately, retroactive and current-year maneuvers can sometimes restore eligibility.
Recovery Strategies for High AGI
- Maximize Late-Window Retirement Contributions: You can often make prior-year or current-year contributions to specific retirement accounts before the tax filing deadline to pull your AGI below critical phase-out lines.
- Accelerate Business Expenses: If you own a pass-through entity or sole proprietorship, purchase necessary equipment before December 31, 2026. This lowers your net business income and, consequently, your overall AGI.
- Audit Your Capital Gains: Review taxable investment accounts for unrecognized losses. Strategic tax-loss harvesting offsets realized gains and reduces your overall AGI calculation.
What If It Still Doesn’t Work?
If your calculated Adjusted Gross Income remains stubbornly high and disqualifies you from crucial 2026 tax benefits, do not guess your way through compliance. Complex tax situations require systematic troubleshooting beyond standard software.
- Re-verify Income Documentation: Cross-reference every W-2, 1099, and K-1 form against your tax software imports to catch transposition errors.
- Review Timing of Income Recognition: Consult a certified public accountant to evaluate whether year-end bonuses or freelance payments can be deferred into the subsequent tax cycle.
- Engage a Qualified Tax Professional: Hire a Certified Public Accountant (CPA) or Enrolled Agent (EA) to perform a comprehensive tax liability review. Professional intervention typically costs between $300 and $1,000 depending on business complexity.
- File for an Extension: If missing documentation prevents accurate AGI computation, file Form 4868 to secure an extension. This avoids late-filing penalties while you organize your financial records.
Conclusion
Mastering your Adjusted Gross Income is essential for minimizing your 2026 tax liability and protecting valuable credits. By strategically applying above-the-line deductions and monitoring your gross receipts, you can successfully lower your taxable baseline. According to verified research and expert sources from the IRS, proactive tax planning remains the single most effective tool for retaining hard-earned capital. Your next actionable step is to review your current pay stubs and retirement contributions today to identify immediate adjustment opportunities before the fiscal year closes.
❓ Frequently Asked Questions
How does AGI differ from modified adjusted gross income (MAGI)?
MAGI is your AGI with certain tax deductions and tax-exempt income added back in. The IRS uses MAGI to determine eligibility for specific programs like Roth IRAs and premium tax credits.
Do capital losses affect my adjusted gross income?
Yes, net capital losses can reduce your gross income up to $3,000 per year, which directly lowers your AGI.
Can my adjusted gross income be higher than my gross income?
No, because AGI is calculated by taking your gross income and subtracting eligible deductions, your AGI will always be equal to or lower than your gross income.
Are traditional IRA contributions included in AGI calculations?
Yes, traditional IRA contributions can be deducted above the line, which directly reduces your overall AGI depending on your income level and workplace plan coverage.
How do self-employed individuals calculate AGI?
Self-employed individuals deduct business expenses and half of their self-employment tax from their gross business income before arriving at their final AGI.
Does unemployment income count toward gross income?
Yes, federal law considers unemployment compensation fully taxable, meaning it must be included in the gross income figure used to calculate your AGI.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.