American Opportunity Tax Credit Explained Expert 2026 Guide
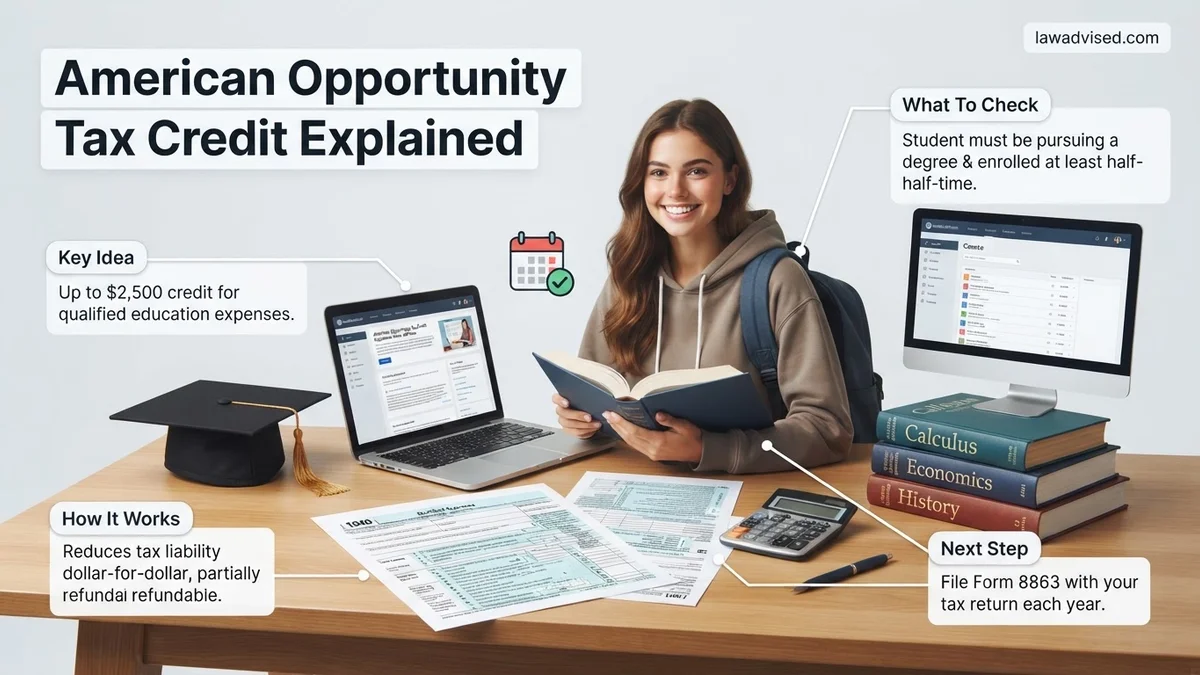
The American Opportunity Tax Credit (AOTC) provides a dollar-for-dollar reduction in federal income tax for eligible students pursuing a higher education degree. Claimants can receive up to $2,500 per eligible student for qualified tuition and related expenses during their first four years of college.
The American Opportunity Tax Credit (AOTC) is a federal tax benefit worth up to $2,500 per eligible student for higher education expenses. If you are footing the bill for college in 2026, this credit directly reduces your tax liability dollar-for-dollar, and up to $1,000 of it can be refunded to you even if you owe no federal income tax.
Navigating college expenses is stressful, but understanding how to leverage the AOTC can put thousands of dollars back into your pocket. To secure this financial relief, you must meet strict criteria regarding enrollment status, income limits, and eligible academic expenses before filing your 2026 tax return.
Key Takeaways
- Earn up to $2,500 per eligible student for qualified higher education expenses.
- The credit applies only to the first four years of higher education.
- Up to 40% of the credit (maximum $1,000) is fully refundable.
- Students must be enrolled at least half-time in a degree program.
- Income phase-outs apply for taxpayers with a modified adjusted gross income over $80,000 ($160,000 if filing jointly).
What Causes Eligibility Issues and How the AOTC Works
Many taxpayers lose out on the AOTC because they misunderstand the baseline requirements set by the IRS. Eligibility issues usually stem from failing to meet the minimum course load or exceeding the strict four-year lifetime limit per student.
Core Enrollment and Student Criteria
- Degree Program: The student must be pursuing a degree or other recognized education credential.
- Half-Time Enrollment: The student must be enrolled at least half-time for at least one academic period beginning in 2026.
- Four-Year Limit: You cannot claim the AOTC for more than four tax years total per student. If you completed four years of higher education before 2026, you no longer qualify.
- Disciplinary Record: The student cannot have any federal or state felony drug convictions at the end of the tax year.
Income Limits and Phase-Outs
Your Modified Adjusted Gross Income (MAGI) dictates whether you can claim the full credit, a partial credit, or nothing at all in 2026. For married couples filing jointly, the phase-out range begins at a MAGI of $180,000. If your joint income exceeds $200,000, the credit drops to zero. For single filers, the phase-out starts at $80,000, with a complete cutoff at $90,000. Staying aware of these thresholds prevents unexpected tax bill surprises.
How to Calculate Your American Opportunity Tax Credit Benefit
The math behind the AOTC is designed to heavily reward your first dollars spent on higher education. You cannot simply guess your credit amount; you must calculate it using a specific tiered formula based on actual out-of-pocket costs.
The Dollar-for-Dollar Formula
The credit calculation uses a structured formula applied to your qualified expenses:
- 100 percent of the first $2,000 you spend on eligible expenses.
- 25 percent of the next $2,000 you spend on eligible expenses.
- Maximum payout: The absolute limit caps out at $2,500 per eligible student per year.
For example, if you pay $3,000 in qualifying college costs for the 2026 tax year, your credit equals $2,250 (100 percent of the first $2,000, plus 25 percent of the remaining $1,000). If you spend $4,000 or more, you hit the maximum $2,500 threshold.
Understanding the Refundable Portion
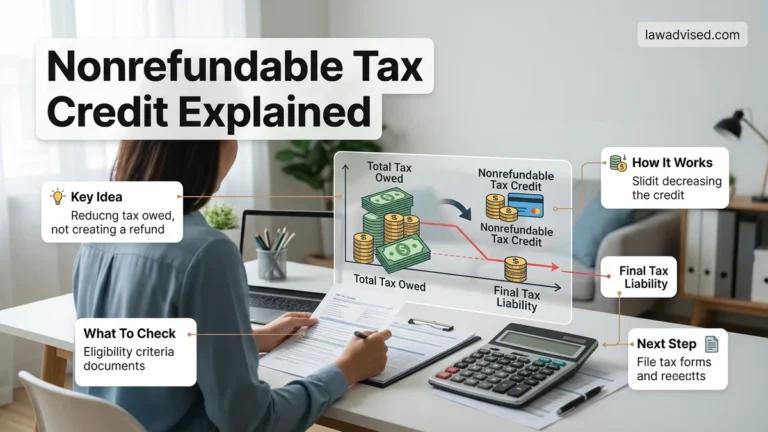
Unlike non-refundable tax breaks that only wipe out your tax liability, the AOTC features a powerful refundable component. Up to 40 percent of your calculated credit—with a maximum of $1,000—is fully refundable. If your total tax liability for 2026 drops to zero and you still have credit remaining, the IRS will issue you a check for that remaining balance.
Step-by-Step Guide to Claiming the AOTC on Your Tax Return
Claiming the American Opportunity Tax Credit requires precise documentation and adherence to IRS filing guidelines. Tax experts recommend gathering all necessary materials before opening your tax preparation software for the 2026 filing season to avoid costly calculation errors.
1. Secure Form 1098-T from Your Eligible Educational Institution
By January 31, 2026, your college or university must issue Form 1098-T, Tuition Statement. This document details the qualified tuition and related expenses paid during the previous tax year. Verify that Box 1 reflects the actual amounts paid rather than just amounts billed, as the IRS mandates the cash method of accounting for this credit.
2. Complete IRS Form 8863
You must fill out and attach IRS Form 8863, Education Credits (American Opportunity and Lifetime Learning Credits), to your federal income tax return. Part I of this form specifically calculates the AOTC. Ensure you enter the correct Employer Identification Number (EIN) for the educational institution and verify that the student pursued an eligible program leading to a degree or recognized credential.
3. Transfer Data to Form 1040
After calculating your allowable credit on Form 8863, transfer the final non-refundable and refundable amounts to the appropriate lines on your IRS Form 1040 or 1040-SR. If you qualify for the maximum $1,000 refundable portion, ensure that your tax software correctly routes this calculation to the refundable credits section of your return.
What If Your Credit Is Rejected or Your Claim Gets Audited
If the IRS rejects your AOTC claim or flags your return for an audit, immediate and structured action is required. Tax compliance data from 2026 indicates that most education credit rejections stem from missing Form 1098-T data or mismatched taxpayer identification numbers.
1. Review the IRS Notice Carefully
Examine the specific error code or explanation letter provided by the IRS. The notice will indicate whether the rejection is due to a math error, a missing student Social Security Number, or an institutional reporting discrepancy.
2. Gather Supporting Receipts and Records
Compile canceled checks, bank statements, or credit card receipts proving that you paid qualified tuition and fee expenses directly to the institution. Remember that course-related books and supplies must be backed by itemized store receipts if they exceed standard estimates.
3. Amend Your Return Using Form 1040-X
If you forgot to claim the credit initially or need to correct Form 8863 data, file an amended return using IRS Form 1040-X. Processing amended returns typically takes between 8 to 12 weeks during peak 2026 filing periods.
What If It Still Doesn’t Work?
If your attempts to claim or appeal the AOTC fail due to complex income phase-outs or dependency status disputes, consider these fallback steps:
- Evaluate Alternative Credits: If you have exhausted the four-year limit for the AOTC, pivot to the Lifetime Learning Credit, which has no lifetime dollar cap and allows for post-baccalaureate coursework.
- Verify Dependency Rules: Consult IRS Publication 970 to confirm whether the student qualifies as your dependent, as claiming errors frequently trigger automated disallowance.
- Consult a Certified Public Accountant: For persistent IRS audit flags, engage a licensed CPA or Enrolled Agent. Professional tax representation for credit audits typically ranges from $300 to $900 depending on complexity.
- Utilize IRS Taxpayer Assistance Centers: Schedule an in-person appointment at a local IRS office if correspondence yields no resolution. Bring copies of your 2026 Form 1098-T and prior year transcripts.
Conclusion
Navigating the American Opportunity Tax Credit requires strict attention to income thresholds, lifetime limits, and precise IRS documentation. By securing Form 1098-T early and accurately completing Form 8863, taxpayers can maximize up to $2,500 in annual education savings. According to verified research and expert financial sources, proactive record-keeping remains the single most effective safeguard against rejected claims or compliance audits. Take the immediate next step by logging into your student financial portal to download your official 1098-T statement today.
❓ Frequently Asked Questions
What are the exact income limits to qualify for the AOTC?
To claim the full credit, your modified adjusted gross income (MAGI) must be $80,000 or less ($160,000 or less for married filing jointly). The credit phases out completely for single filers making over $90,000 and joint filers making over $180,000.
Does room and board count as a qualified expense for the AOTC?
No, expenses for room and board, insurance, medical care, transportation, and personal living expenses are never considered qualified education expenses under IRS rules.
What student enrollment status is required to be eligible?
The student must be enrolled at least half-time for at least one academic period that begins during the tax year in a program leading to a degree, certificate, or other recognized educational credential.
What tax form do I need from my college to claim the AOTC?
You must receive Form 1098-T (Tuition Statement) from your eligible educational institution, which outlines the payments received for qualified tuition and related expenses.
How do I officially claim the AOTC on my federal tax return?
You must file IRS Form 8863 (Education Credits) along with your Form 1040 or 1040-SR, ensuring you report the employer identification number (EIN) of the educational institution.
Can a student with a felony drug conviction claim the credit?
No, federal law prohibits anyone with a federal or state felony conviction for possessing or distributing a controlled substance as of the end of the tax year from claiming the AOTC.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.