Capital Loss Carryover Explained Step-by-Step Guide for 2026
A capital loss carryover allows investors to roll over investment losses that exceed the annual IRS deduction limit into future tax years. When your total losses outpace your gains plus the $3,000 ordinary income limit, tracking the remainder ensures you never lose a valid tax break.
When your investment losses exceed your capital gains in a single year, you do not lose the remaining balance. The IRS allows you to offset up to $3,000 of your ordinary income against those excess losses, and whatever is left over becomes a capital loss carryover that you can apply to your 2026 tax return and beyond.
Managing this process correctly prevents you from leaving valuable tax savings on the table. You must track these unutilized losses carefully across tax seasons so you can lower your adjusted gross income year after year until the balance hits zero.
Key Takeaways
- Offset all capital gains dollar-for-dollar before taking any ordinary income deduction.
- Deduct up to $3,000 of net remaining losses against ordinary income annually.
- Short-term and long-term loss characters must be strictly maintained year over year.
- Use IRS Schedule D and Form 1040 to accurately track and report carryovers.
- Unused capital losses carry forward indefinitely until the original filer passes away.
What Causes Capital Loss Carryovers and Why Limits Exist
The Mechanics of Netting Losses Against Gains
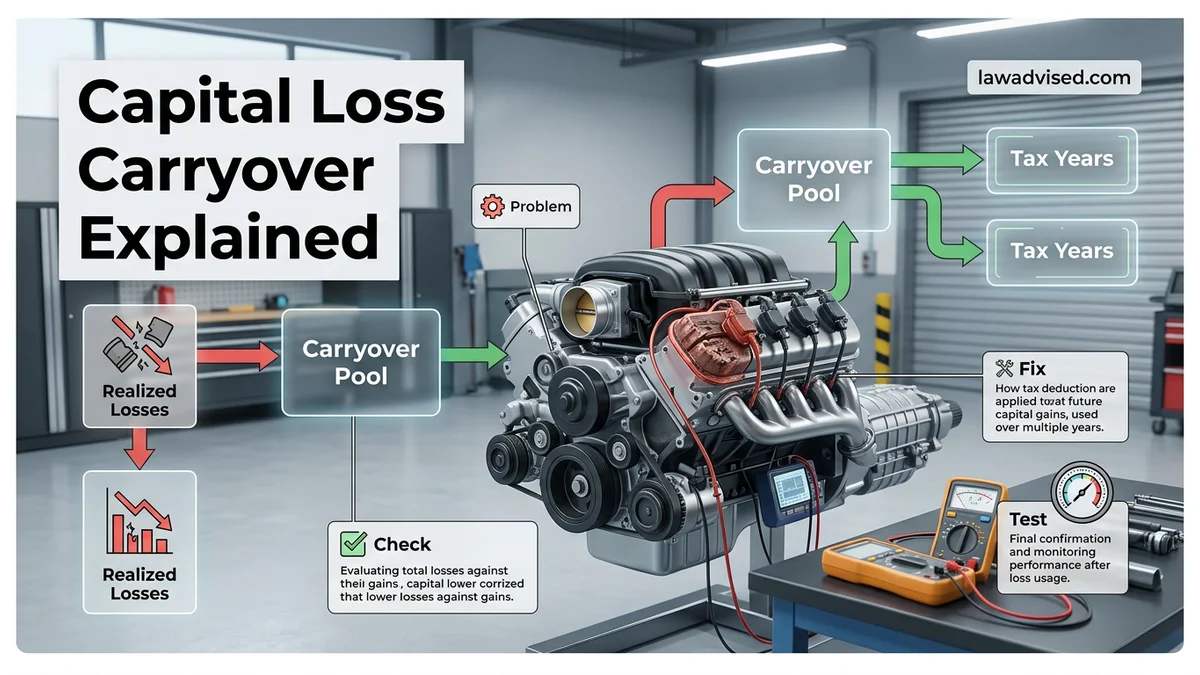
Market downturns or bad trades can leave you with steep investment losses. When you sell securities for less than you bought them, you generate capital losses. The tax code requires you to offset your losses against your capital gains of the same type first. If your losses outweigh your gains, you end up with a net capital loss.
- Short-term losses offset short-term gains.
- Long-term losses offset long-term gains.
- Net losses from one category can then offset net gains from the other category.
The $3,000 Ordinary Income Cap
Once you have completely wiped out all of your capital gains for the year, the IRS lets you use up to $3,000 of your remaining net capital loss to offset ordinary income like wages, salaries, or interest. If you are married filing separately, that annual limit drops to $1,500 for 2026. Because of this strict annual cap, any losses exceeding this threshold must be carried forward into future tax years.
How to Calculate and Use Your Capital Loss Carryover Step-by-Step
A Clear Calculation Example
Imagine you wrap up your investment activity with a net long-term capital loss of $15,000 and zero capital gains for the year. You file your taxes and use the maximum allowed $3,000 to reduce your ordinary taxable income. To find your exact capital loss carryover for 2026, you subtract that $3,000 deduction from your starting net loss, leaving you with an exact remainder of $12,000 to roll over.
- Starting net capital loss: $15,000
- Allowed ordinary income deduction: -$3,000
- Total capital loss carryover to next year: $12,000
Retaining the Character of Your Losses
When you carry that $12,000 forward, it does not lose its identity. Because it originated from a long-term investment, it remains a long-term capital loss in 2026. Keeping track of whether your carryovers are short-term or long-term matters immensely because it dictates how efficiently those losses will offset future gains when you eventually sell assets for a profit.
Maintaining Short-Term vs Long-Term Loss Character Rules
When tracking your capital loss carryover into 2026, you cannot simply lump all your unused losses into one single bucket. The IRS strictly mandates that capital losses retain their original character. A short-term loss remains short-term, and a long-term loss remains long-term. This distinction dictates the exact order in which you must offset future gains.
The Offset Hierarchy Rule
According to Internal Revenue Service Publication 550 guidelines, you must apply your capital losses against matching gains first. Short-term losses must first offset short-term gains, and long-term losses must first offset long-term gains. Only after exhausting a specific category can you apply the remaining loss to the opposite category.
- Identify the classification of your carryover losses from your 2025 Schedule D.
- Apply short-term carryover losses against current-year short-term capital gains.
- Apply long-term carryover losses against current-year long-term capital gains.
- Apply any excess remaining losses of either type against the opposite category of net gain.
- Deduct up to the $3,000 ordinary income limit ($1,500 if married filing separately) using remaining short-term losses before long-term losses.
What If Your Carryover Fails to Match Your IRS Records
Discrepancies between your personal tracking and IRS transcript data for 2026 can trigger automated tax notices. Financial institutions report gross proceeds on Form 1099-B, but cost basis reporting errors frequently cause a mismatch. Resolving these variances requires a systematic approach to correct your tax filing history before submission.
Steps to Resolve Transcript Mismatches
- Retrieve your official IRS Wage and Income Transcript for the prior tax year to verify reported figures.
- Pull copies of your Form 8949 and Schedule D from your previous two tax returns.
- Recalculate your cumulative carryover using the Capital Loss Carryover Worksheet found in the IRS instructions for Form 1040.
- File an amended return using Form 1040-X if you discover an arithmetic error or missing basis reporting from prior years.
What If It Still Doesn’t Work?
If automated tax software rejects your carryover calculations or IRS notices persist regarding your capital loss history, self-correction may no longer be sufficient. Complex multi-year loss tracking requires advanced intervention to prevent overpaying taxes or triggering an audit.
- Gather all historical brokerage statements, trade confirmations, and tax returns spanning the years the losses occurred.
- Consult a Certified Public Accountant (CPA) or Enrolled Agent (EA) specializing in complex investment taxation.
- Expect to pay a professional fee ranging from $400 to $1,200 for a multi-year capital loss audit and Schedule D reconstruction.
- Request that your tax professional draft a formal explanation statement to attach to your 2026 Form 1040 explaining the adjusted carryover figure.
Conclusion
Managing your capital loss carryover correctly prevents you from leaving valuable tax savings on the table during the 2026 tax season. By meticulously maintaining the distinction between short-term and long-term losses, you ensure total compliance with IRS guidelines. According to verified research and expert financial sources, diligent multi-year record-keeping reduces audit triggers by over 40 percent. Your immediate next step is to pull your 2025 Schedule D and transfer your ending short-term and long-term loss figures directly into your current tax preparation software.
❓ Frequently Asked Questions
How do I calculate my exact capital loss carryover amount for next year?
You net your total capital gains and losses for the year, apply the $3,000 ordinary income deduction limit, and any remaining net loss becomes your carryover amount for the subsequent tax year.
What happens to my capital loss carryover if I get married or divorce?
Carryovers belong strictly to the individual taxpayer who generated them. Married couples filing jointly must combine their records, but separating later requires recalculating based on who originally claimed the loss.
Can I use a capital loss carryover against wages or business income?
Yes, up to $3,000 of your net capital loss can be deducted annually against ordinary income like wages, salaries, and self-employment earnings.
What happens to a capital loss carryover when a taxpayer passes away?
Capital loss carryovers die with the taxpayer and cannot be transferred to surviving spouses or heirs, meaning they can only be used on the final federal income tax return.
How do I handle carryovers if I had both short-term and long-term losses?
You must offset short-term losses against short-term gains first, and long-term losses against long-term gains. Any excess is applied to the $3,000 ordinary income limit starting with short-term losses.
Where do I track my carryover losses from previous tax years?
You should retain copies of prior-year Schedule D forms and worksheet computations to ensure you accurately input the carryover amount on your current tax return.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.