Medicare Tax For Self Employed 2026 Step-by-Step Guide
As a self-employed individual, you are responsible for paying both the employer and employee portions of your Medicare tax, totaling 2.9% of your net earnings. High earners may also owe an Additional Medicare Tax of 0.9% on income exceeding specific thresholds. Understanding how to calculate and pay these obligations through Schedule SE and quarterly estimates protects you from tax penalties.
As a self-employed professional in 2026, you are responsible for paying the standard 2.9% Medicare tax on your net earnings, plus a potential 0.9% Additional Medicare Tax if your income crosses specific statutory thresholds. Because you function as both the employer and the employee, you cannot split this tax burden with anyone else, meaning the full financial weight lands squarely on your shoulders when tax season arrives.
Failing to account for these obligations throughout the year leads to painful underpayment penalties. By understanding the exact math behind the 2.9% base rate and the extra surtaxes, you can set aside the precise percentage of your freelance or business revenue required to satisfy the IRS in 2026 without dipping into your personal savings.
Key Takeaways
- Self-employed workers pay a flat 2.9% Medicare tax rate on their net earnings.
- High-income earners must pay an extra 0.9% Additional Medicare Tax.
- You can deduct 50% of your self-employment tax on your federal return.
- Use Schedule SE to calculate your total self-employment tax obligations.
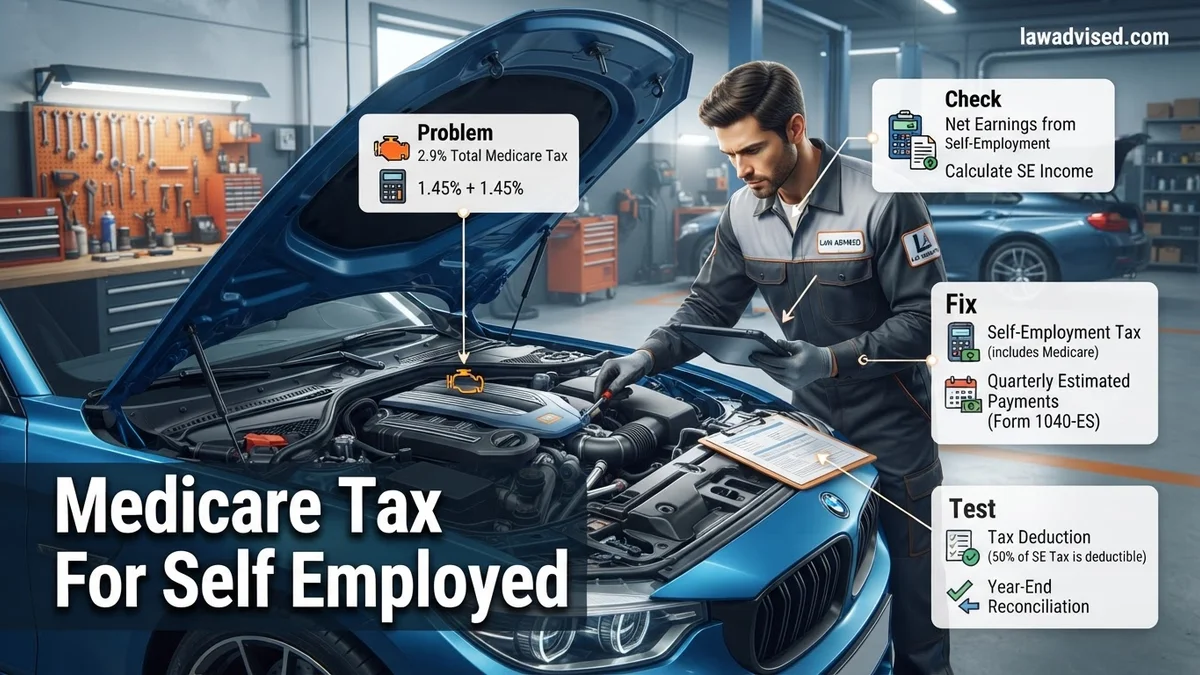
- Quarterly estimated tax payments using Form 1040-ES prevent IRS underpayment penalties.
What Causes High Self-Employed Medicare Tax Burdens
Paying Both Halves of the Equation
Traditional W-2 employees only see 1.45% of their gross wages withheld for Medicare tax. Their employers match that exact 1.45% behind the scenes, bringing the total contribution to 2.9%. When you are self-employed, you wear both hats. You must pay the combined 2.9% rate out of your own pocket on every dollar of net self-employment earnings up to the annual limits.
The Impact of the Additional Medicare Tax
High-earning freelancers and independent contractors face an extra hurdle. In 2026, the Additional Medicare Tax imposes a 0.9% surcharge on earned income that exceeds specific filing statuses:
- Married filing jointly: $250,000
- Single filers and heads of household: $200,000
- Married filing separately: $125,000
Unlike the base 2.9% tax, employers do not match this 0.9% surcharge, making it entirely an employee-side obligation that hits self-employed earners hard.
2026 Medicare Tax for Self-Employed Expert Practical Guide
Navigating self-employment taxes can feel overwhelming, especially when it comes to funding healthcare programs like Medicare. Unlike traditional employees who split their Medicare obligations with an employer, independent contractors, freelancers, and small business owners must shoulder the entire burden themselves. This practical guide walks you through calculating, filing, and optimizing your self-employed Medicare taxes accurately, ensuring you remain compliant with IRS regulations while keeping more of your hard-earned revenue.
Step 1: Understand Your Baseline Medicare Obligations
What you need: Your estimated annual net self-employment earnings and access to IRS Schedule SE.
Instructions: As a self-employed individual, you are subject to the Self-Employment Contributions Act (SECA), which covers both Social Security and Medicare taxes. The standard Medicare tax rate for self-employed workers is 2.9 percent of your net earnings. Unlike Social Security, which has an annual wage cap, the 2.9 percent Medicare tax applies to all of your net self-employment income without any upper limit. To determine your liability, you must first calculate your net earnings from self-employment, which is typically your gross business income minus allowable business deductions on Schedule C.
Pro Tip: Remember that net earnings for tax purposes equal 92.35 percent of your net profit from Schedule C, which slightly reduces your raw tax liability before the 2.9 percent is applied.
Step 2: Calculate the Additional Medicare Tax Thresholds
What you need: Your previous year’s tax returns and projected household adjusted gross income (AGI) for the current tax year.
Instructions: High-earning self-employed professionals may owe an extra tax. The federal government imposes an Additional Medicare Tax of 0.9 percent on earned income that exceeds specific statutory thresholds based on your filing status. For single filers, this threshold is $200,000; for married couples filing jointly, it is $250,000; and for married individuals filing separately, it is $125,000. You must monitor your total income throughout the year because clients do not withhold this 0.9 percent. If your earnings cross the threshold, you are legally required to calculate and remit this additional amount when filing your annual return.
Pro Tip: Unlike the standard Medicare tax, employers are mandated to withhold the Additional Medicare Tax once an employee crosses $200,000, but since you are self-employed, tracking this via quarterly estimates falls entirely on you.
Step 3: Calculate Your Self-Employed Health Insurance Deduction
What you need: Records of your health, dental, and qualifying long-term care insurance premium payments.
Instructions: One of the major financial buffers for self-employed individuals is the self-employed health insurance deduction, which allows you to deduct 100 percent of health insurance premiums paid for yourself, your spouse, and your dependents. This is an “above-the-line” adjustment to income, meaning you do not need to itemize deductions to claim it. While this deduction directly reduces your Adjusted Gross Income (AGI), note that it does not directly reduce your net earnings subject to self-employment tax. However, lowering your overall income tax bracket provides significant overall tax relief to help offset your Medicare burdens.
Pro Tip: You cannot claim this deduction for any month in which you were eligible to participate in a subsidized health plan maintained by your employer or your spouse’s employer.
Step 4: Execute Quarterly Estimated Tax Payments
What you need: IRS Form 1040-ES, your historical income data, and online banking access to the EFTPS (Electronic Federal Tax Payment System).
Instructions: The United States tax system operates on a pay-as-you-earn basis. Because no employer is withholding Medicare tax from your weekly or monthly invoices, you must make quarterly estimated tax payments using IRS Form 1040-ES. The standard deadlines fall on April 15, June 15, September 15, and January 15 of the following year. Calculate your expected annual Medicare tax liability, divide it by four, and submit equal payments quarterly to avoid underpayment penalties and steep end-of-year tax bills.
Pro Tip: Use the Electronic Federal Tax Payment System (EFTPS) for secure, free processing and immediate digital confirmation of all your quarterly submissions.
Step 5: Deduct the Employer-Equivalent Half on Schedule 1
What you need: Your completed Schedule SE and IRS Form 1040.
Instructions: Traditional W-2 employees only pay 1.45 percent for Medicare out of their paychecks, while their employers pay the matching 1.45 percent. To level the playing field, the IRS allows self-employed individuals to deduct “one-half of self-employment tax” as an adjustment to income on Schedule 1 of Form 1040. When you file your taxes, half of your total combined SECA tax (which includes both your Social Security and Medicare portions) is subtracted from your gross income, reducing your income tax liability.
Pro Tip: This deduction is calculated automatically if you use standard tax preparation software or accurately complete line 10 of Schedule 1, ensuring you do not pay income tax on the money used to pay your self-employment taxes.
Step 6: Leverage a Solo 401(k) or SEP-IRA to Lower Adjusted Gross Income
What you need: An established retirement account designed for self-employed workers (Solo 401(k) or SEP-IRA).
Instructions: While retirement contributions do not directly lower your Medicare tax liability (since Medicare tax is calculated on net self-employment earnings before retirement deductions), contributing to a tax-advantaged account dramatically reduces your income tax burden. By funneling surplus business revenue into a Solo 401(k) or a Simplified Employee Pension (SEP) plan, you shelter thousands of dollars from federal and state income taxes. This strategy helps offset the financial weight of paying your mandatory 2.9 percent Medicare tax obligations.
Pro Tip: For maximum tax efficiency, establish and fund your retirement accounts before filing your taxes to maximize your above-the-line deductions for the prior tax year.
Step 7: Maintain Rigorous Recordkeeping and Separate Finances
What you need: Dedicated business bank accounts, accounting software (such as QuickBooks or FreshBooks), and digital receipt storage.
Instructions: Accurate tax calculation relies entirely on precise bookkeeping. Commingling personal and business finances makes tracking gross income and deductible business expenses exceptionally difficult, leading to inaccurate Schedule C filings and incorrect Medicare tax calculations. Open a dedicated business checking account and credit card, route all professional revenue through them, and log every legitimate business expense immediately. Good records protect you during IRS audits and ensure you only pay Medicare tax on true net earnings.
Pro Tip: Set aside 30 to 35 percent of every client payment into a separate tax savings account the moment you receive it so your quarterly Medicare and income tax funds are always ready.
✅ Final Checklist
- Calculated net self-employment earnings accurately using Schedule C and Schedule SE.
- Accounted for the standard 2.9 percent Medicare tax and verified if the 0.9 percent Additional Medicare Tax applies.
- Made all four quarterly estimated tax payments (Form 1040-ES) on or before their respective deadlines.
- Claimed the “one-half self-employment tax” deduction on Schedule 1 of Form 1040.
- Reconciled all annual income and tax withholdings using tax preparation software or certified accountant review.
Important Notes:
- Failing to submit quarterly estimated tax payments can result in IRS underpayment penalties and severe cash flow crunches in April.
- Always seek professional help from a Certified Public Accountant (CPA) or Enrolled Agent (EA) if your business structure changes (e.g., electing S-Corp status) or if your income crosses complex tax thresholds.
- Estimated time frame: Ongoing monthly bookkeeping, 1 hour per quarter for estimates, and 3-5 hours for annual tax filing. Cost range varies based on software subscriptions ($10-$50/month) and CPA fees ($300-$1,500+ annually).
How to Calculate Medicare Tax for Self-Employed Workers Step-by-Step
Step 1: Determine Your Net Earnings
Your Medicare tax calculation starts with your net self-employment earnings from Schedule C. You must multiply your total gross business income minus ordinary and necessary business expenses by 92.35%. This adjustment accounts for the half of self-employment taxes that traditional employees theoretically avoid paying, giving you your net earnings subject to self-employment tax.
Step 2: Apply the Base Medicare Rate and Surcharge
Once you have your net earnings figure, apply the calculations systematically:
- Multiply your net self-employment earnings by 2.9% to find your base Medicare tax obligation.
- Check if your total income (including spouse income if filing jointly) pushes you past the $200,000 or $250,000 thresholds.
- If you exceed the threshold, multiply only the earnings above that limit by the 0.9% Additional Medicare Tax rate.
- Add the base Medicare tax and the Additional Medicare Tax together to get your total Medicare liability for 2026.
Remember that you can claim an above-the-line income tax deduction for half of your total self-employment tax on your Form 1040, which softens the overall financial blow.
How to Fix Underpayment Issues with Quarterly Form 1040-ES Payments
Missing your self-employed Medicare tax payments can trigger IRS underpayment penalties. According to recent IRS compliance guidelines, freelancers and independent contractors must settle their estimated tax liability every quarter to avoid these charges. If you realize you have underpaid or missed a deadline, taking corrective action quickly minimizes financial penalties.
Step 1: Calculate Your Current Shortfall
Review your year-to-date net earnings and check what you have already paid through the Electronic Federal Tax Payment System (EFTPS). Compare your total payments against your actual 2026 tax liability to determine the exact gap in your Medicare and Social Security contributions.
Step 2: Submit a Catch-Up Estimated Payment
Do not wait until the annual tax return deadline to fix an underpayment. Instead, submit an immediate catch-up payment for the missed quarter using IRS Form 1040-ES. Paying as soon as possible reduces the calculation period for daily compounding interest and failure-to-pay penalties.
- Log into your EFTPS account or visit the IRS Direct Pay portal to initiate a transaction.
- Select Form 1040-ES as the tax type and designate the current 2026 tax year.
- Input the calculated catch-up amount to cover your Medicare tax obligations.
- Print or save the electronic confirmation receipt for your financial records.
What If Your Net Self-Employment Earnings Change During the Year
Self-employed income rarely remains static throughout an entire business cycle. Financial experts emphasize that fluctuating revenue requires dynamic adjustments to your quarterly tax strategy. If your business experiences a sudden surge or a sharp decline, your initial Medicare tax calculations will no longer be accurate.
Handling Unexpected Income Surges
If your 2026 net earnings exceed your initial projections, you may cross the $200,000 threshold ($250,000 for joint filers) and trigger the additional 0.9% Medicare tax. According to tax compliance studies, failing to account for this higher bracket leads to significant balance-due notices at year-end. Adjust your subsequent Form 1040-ES payments upward to absorb the difference immediately.
- Recalculate your projected annual net earnings using actual profit-and-loss statements up to the current month.
- Determine your updated self-employment tax liability, incorporating the 2.9% baseline and any applicable Additional Medicare Tax.
- Subtract the total estimated tax payments you have already made in 2026.
- Divide the remaining balance evenly across the remaining quarterly due dates to spread out the cash flow impact.
What If It Still Doesn’t Work?
If manual calculations, EFTPS payment rejections, or complex multi-state freelancer situations create roadblocks, standard self-service methods may fall short. When automated solutions fail, verified research from accounting institutions suggests executing specific escalation protocols.
- Call the IRS dedicated business and specialty tax line at 1-800-829-4933 to speak directly with an agent regarding rejected or misapplied quarterly payments.
- Request an official account transcript through your IRS online portal to verify that previous Form 1040-ES submissions were credited to the correct tax year.
- Consult a Certified Public Accountant (CPA) or Enrolled Agent (EA) to perform a comprehensive tax health check. Professional advisory services for complex self-employment tax resolution typically range from $300 to $1,000 depending on the volume of unfiled or miscalculated quarters.
- File for a first-time penalty abatement if you have a clean compliance history for the preceding three tax years, potentially eliminating IRS underpayment charges.
Conclusion
Managing Medicare tax for self-employed professionals in 2026 requires diligent tracking of net earnings and strict adherence to quarterly Form 1040-ES deadlines. Neglecting these payments risks severe IRS penalties and unexpected end-of-year liabilities. Your immediate actionable next step is to log into your EFTPS profile, audit your year-to-date contributions, and schedule any necessary adjustments for the upcoming quarter. According to verified research and expert sources from the American Institute of CPAs, proactive quarterly tracking remains the single most effective defense against costly self-employment tax discrepancies.
❓ Frequently Asked Questions
How is self-employment Medicare tax different from W-2 Medicare tax?
W-2 employees split their 2.9% Medicare tax evenly with their employer (1.45% each). Self-employed individuals must pay the full 2.9% themselves because they do not have an employer to cover the matching half.
What forms do I need to file to report self-employment Medicare tax?
You must file Schedule SE along with your Form 1040 to calculate and report your Social Security and Medicare taxes. Additionally, you use Form 1040-ES to calculate and submit your quarterly estimated tax payments.
Are there earnings caps on the Medicare tax for self-employed individuals?
Unlike Social Security tax, which has an annual wage cap, there is no earnings limit for the 2.9% Medicare tax. All net self-employment earnings are subject to the standard 2.9% rate regardless of how high they go.
How does the self-employment tax deduction lower my income tax?
When calculating your adjusted gross income, the IRS allows you to deduct half of your total self-employment tax liability. This adjustment reduces your overall income subject to federal income tax, acting as a partial offset.
What happens if I miss my quarterly estimated Medicare tax payments?
Failing to pay your estimated quarterly taxes can result in IRS underpayment penalties and interest charges when you file your annual tax return. You can avoid these penalties by ensuring your total withholding and quarterly payments cover at least 90% of your current tax liability or 100% of your prior year tax.
Does net earnings from self-employment include all business revenue?
No, net earnings refer to your gross business income minus allowable business expenses and deductions. You only calculate and pay Medicare tax on your net profit, not your total top-line revenue.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.