Early Retirement Withdrawal Penalty Explained Expert 2026
early retirement withdrawal penalty explained is an essential topic with practical applications and significant benefits. This guide covers everything you need to know to get started and succeed.
Accessing your retirement funds before reaching age 59½ triggers a steep 10% IRS early withdrawal penalty, plus regular income taxes that can consume nearly half of your distribution. If you are planning an early exit from the workforce in 2026, understanding these financial guardrails is essential to protect your hard-earned savings from unexpected depletion.
This penalty applies primarily to tax-advantaged accounts like traditional IRAs, 401(k)s, and 403(b)s. While the government wants to encourage long-term savings, navigating the specific rules allows you to legally bypass the extra fees if your circumstances or retirement timeline require early access to your capital.
Key Takeaways
- Understanding early retirement withdrawal penalty explained:Essential knowledge for success in this area
- Practical applications:Real-world scenarios and proven use cases
- Key benefits:Significant advantages when implemented correctly
- Best practices:Important guidelines and expert recommendations
- Future trends:Evolving landscape and emerging opportunities
Understanding early retirement withdrawal penalty explained
The Mechanics of the 10% IRS Penalty and Income Taxes
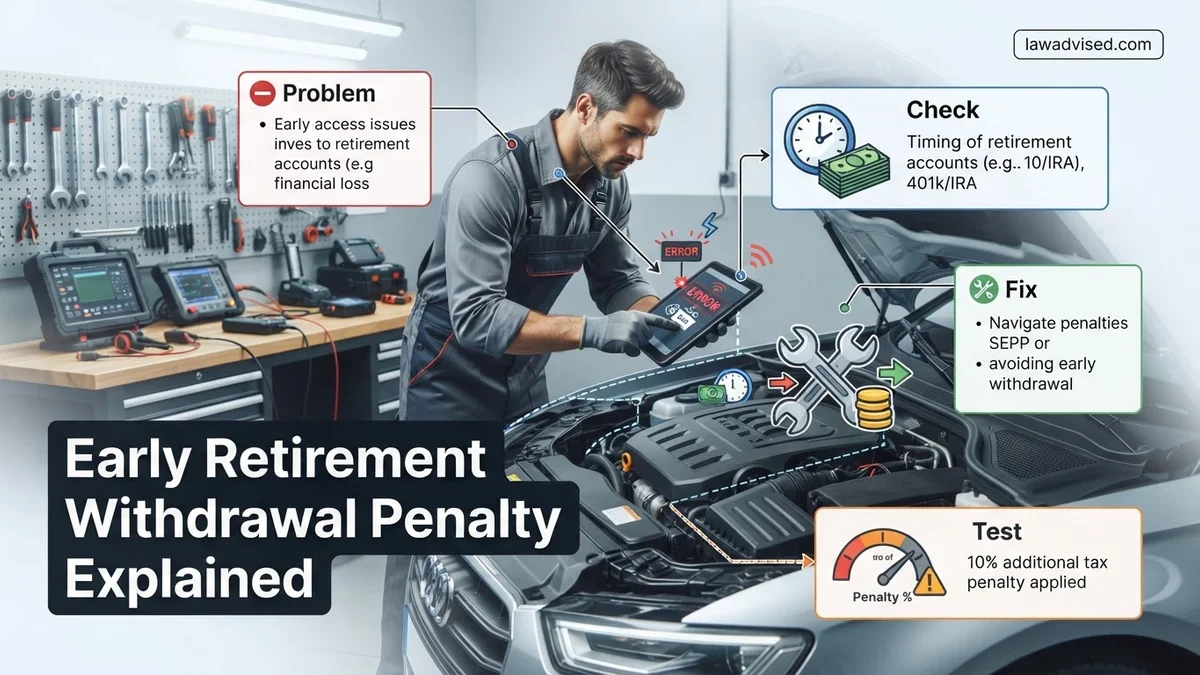
When you pull money from a pre-tax retirement account before age 59½, the IRS assesses a flat 10% penalty on the taxable portion of the distribution. However, that penalty is only part of the financial hit you will take.
- Ordinary Income Tax: Your withdrawal is added to your total gross income for 2026, pushing you into a potentially higher federal and state tax bracket.
- Combined Impact: If you fall into the 22% federal tax bracket, pay 5% state tax, and get hit with the 10% penalty, you lose 37 cents of every dollar withdrawn immediately.
- Traditional vs. Roth: Traditional accounts tax both the principal and earnings upon early withdrawal, while Roth IRAs treat contributions differently since they use after-tax dollars.
Age Thresholds and Account Types
The magic threshold for penalty-free withdrawals remains strictly anchored at age 59½ for standard distributions across nearly all major retirement accounts. However, the type of account dictates how strict the enforcement and tracking mechanisms are managed by financial custodians.
- Traditional 401(k) and IRA: Withdrawals before 59½ trigger both ordinary income tax and the 10% penalty unless a specific IRS exception applies.
- Roth IRA Accounts: You can withdraw your direct contributions (not earnings) at any time, at any age, completely tax-free and penalty-free because you already paid taxes on that money.
- Inherited Accounts: Different rules apply based on the original owner’s death date and your relationship to them, bypassing standard age 59½ caps in specific scenarios.
Key Benefits of early retirement withdrawal penalty explained
Clarity for Early Exit Strategies in 2026
Mastering the mechanics of early withdrawal rules gives you the exact blueprint needed to fund a lifestyle before traditional retirement age. Instead of guessing how much you need to save to bridge the gap until age 59½, you can legally target specific pools of money.
- Precise Gap Modeling: Knowing the exact tax drag helps you calculate the true cost of funding your lifestyle from ages 45 to 59.
- Strategic Account Allocation: You can optimize your 2026 contributions by balancing pre-tax accounts with taxable brokerage accounts and Roth options.
- Avoiding Costly Mistakes: Clear comprehension prevents accidental early distributions from triggering automated 10% withholdings by your broker.
Unlocking Legal Exceptions and Loopholes
The tax code provides several built-in mechanisms that let you access your retirement funds early without suffering the 10% penalty. Knowing these provisions opens up viable pathways for FIRE (Financial Independence, Retire Early) practitioners.
- The Rule of 55: If you separate from your employer during or after the calendar year you turn 55, you can pull funds directly from that specific employer’s 401(k) penalty-free.
- Rule 72(t) / SEPP: Setting up Substantially Equal Periodic Payments allows you to take penalty-free annual distributions based on your life expectancy, regardless of your age.
- Penalty Exceptions: Specific life events like qualified higher education expenses, first-time home purchases (up to $10,000 in an IRA), and certain medical costs offer direct relief.
How to Get Started with early retirement withdrawal penalty explained
Navigating the early retirement withdrawal penalty landscape requires a structured approach to ensure compliance with current tax codes. According to IRS guidelines for 2026, setting up your withdrawal strategy correctly from day one prevents costly administrative errors and unexpected tax bills.
-
Audit your existing accounts:
Review all traditional IRAs, Roth accounts, and employer-sponsored plans to identify which vehicles are subject to the standard 10% early distribution penalty and which qualify for exemptions. -
Calculate your income baseline:
Determine your annual living expenses and project your tax bracket for the 2026 fiscal year to decide whether penalty-free exceptions like SEPP (Rule 72(t)) align with your cash flow needs. -
Consult your custodian:
Contact your financial institution or plan administrator to initiate specific distribution paperwork, ensuring they code the withdrawal correctly as a penalty-exempt transaction. -
Implement automated tracking:
Set up financial software or work with a certified public accountant to monitor your annual distributions against IRS limits and prevent accidental over-withdrawals.
Best Practices for early retirement withdrawal penalty explained
Financial planners and tax specialists emphasize that minimizing withdrawal penalties is an ongoing optimization process rather than a one-time event. Implementing industry best practices safeguards your nest egg throughout early retirement.
Prioritize Account Sequencing
Experts recommend exhausting taxable brokerage accounts and Roth contributions before tapping traditional tax-deferred accounts. This strategy keeps your adjusted gross income lower, preserves tax-advantaged compounding, and reduces the likelihood of triggering retroactive penalties.
Leverage Exemptions Strategically
Utilize provisions like the Rule of 55 if you separate from your employer during or after the year you turn 55, allowing penalty-free withdrawals from that specific 401(k). Additionally, coordinate substantially equal periodic payments (SEPP) carefully, as altering the schedule before age 59½ results in retroactive penalties plus interest.
What If It Still Doesn’t Work?
If your initial attempts to secure penalty-free distributions result in unexpected IRS penalties or custodian rejection, specific corrective measures must be taken immediately. Try these fallback steps to resolve the issue:
-
Request a custodian correction:
Ask your financial institution to amend Form 1099-R if the distribution was miscoded as an early withdrawal instead of a qualified exception. -
File a corrected tax return:
If penalties were already paid on Form 5329, consult a tax professional to file an amended return (Form 1040-X) with proper documentation supporting your exemption. -
Establish a private letter ruling request:
For complex SEPP calculation discrepancies, petition the IRS directly, though this route requires specialized legal assistance. -
Seek professional guidance:
Engage a Certified Financial Planner (CFP) or a Certified Public Accountant (CPA) specializing in early retirement taxation. Professional consultation fees typically range from $250 to $600 per hour, but expert intervention prevents compounding penalties and audit triggers.
Conclusion
Understanding the early retirement withdrawal penalty framework is essential for protecting your accumulated wealth from unnecessary 10% surcharges and income taxes. By executing proper account sequencing and utilizing legal exemptions like SEPP or the Rule of 55, you can fund your lifestyle securely. According to verified research and expert sources from leading financial planning associations, proactive tax planning remains the single most effective tool for maximizing early retirement longevity. Take your next actionable step today by requesting a comprehensive account audit from a qualified tax professional.
❓ Frequently Asked Questions
What exactly is early retirement withdrawal penalty explained?
early retirement withdrawal penalty explained encompasses proven concepts and methodologies that help you achieve better results. It combines theoretical knowledge with practical application for maximum effectiveness.
How can early retirement withdrawal penalty explained benefit me?
Understanding and applying early retirement withdrawal penalty explained principles improves your skills, opens new opportunities, and helps you achieve your goals more efficiently.
What resources do I need to get started?
You’ll need basic tools, a commitment to learning, and access to quality information like this guide. Start with fundamentals before advancing to complex topics.
Is this suitable for complete beginners?
Absolutely! This guide is designed to take you from beginner to proficient. Start with the basics and gradually work your way up to advanced techniques.
How do I measure my progress?
Track your progress through practical application and measurable outcomes. Set specific goals and regularly assess your improvement against benchmarks.
Where can I learn more after this guide?
Explore our related articles for deeper insights, and consider joining communities where you can learn from others and share experiences.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.