History of Federal Income Tax in USA Guide 2026
The history of federal income tax in the USA spans from temporary Civil War funding measures to the permanent 1913 constitutional amendment. Understanding this evolution reveals how tariffs were replaced and how modern brackets were shaped by national emergencies.
The federal income tax in the United States originated as a temporary wartime measure before becoming a permanent fixture through the ratification of the 16th Amendment in 1913. Rather than existing as a constant part of American governance, the modern federal income tax system evolved through a turbulent century of constitutional challenges, economic shifts, and emergency funding needs.
Understanding this historical trajectory helps you see why the modern tax code functions the way it does in 2026. From funding the Civil War to financing the expansion of the federal government in the 20th century, the income tax transformed how the U.S. government collects revenue and impacts your personal finances today.
Key Takeaways
- The first U.S. income tax was enacted in 1861 to fund the Civil War.
- The Supreme Court ruled the 1894 income tax unconstitutional in Pollock v. Farmers’ Loan & Trust Co.
- The 16th Amendment was officially ratified in February 1913, establishing Congress’s right to tax incomes.
- World War II transformed the income tax into a mass tax with employer withholding.
- Major tax reform acts in 1954, 1986, and beyond continually reshaped brackets and deductions.
What Causes the Misconception That Income Tax Was Always Permanent in America
Many people assume the federal government has always taxed individual earnings, but the United States operated for more than a century primarily on tariffs and excise taxes. When the government needed emergency funds, it occasionally experimented with direct taxation, leading to temporary measures that confuse modern observers.
The Civil War Revenue Act Experiment
The very first U.S. income tax was born out of financial desperation during the Civil War. In 1861, Congress passed the Revenue Act, which imposed a flat three percent tax on incomes over 800 dollars to help fund the Union war effort. By 1862, lawmakers realized a flat tax was not capturing enough revenue, so they replaced it with a progressive system that taxed higher earners at a steeper rate. This early tax expired in 1872, proving to citizens that income taxes were meant to be temporary tools for crisis management rather than permanent obligations.
The Pollock v. Farmers’ Loan & Trust Co. Roadblock
As the federal government grew toward the end of the 19th century, lawmakers tried to implement another income tax through the Wilson-Gorman Tariff Act of 1894. Wealthy taxpayers immediately challenged the law in court. In the landmark 1895 case Pollock v. Farmers’ Loan & Trust Co., the Supreme Court ruled that taxing income from property—such as rents and dividends—was a direct tax that had to be apportioned among the states by population. This effectively struck down the federal income tax and created a massive constitutional barrier that required a complete rewrite of the rules to bypass.
How to Fix Your Understanding of the 16th Amendment and Early Revenue Acts
To understand why you file a tax return every year, you have to look past the early experimental taxes and focus on how the government permanently altered the Constitution. Lawmakers realized that relying on tariffs unfairly burdened working-class consumers while sheltering vast industrial fortunes.
Ratification of the 16th Amendment in 1913
To overcome the Supreme Court’s 1895 ruling, progressive reformers and politicians pushed for a constitutional amendment that would explicitly grant Congress the power to tax all incomes without apportioning it among the states. After years of debate, the 16th Amendment was officially ratified in February 1913. This single legislative act permanently removed the constitutional hurdles that previously protected high earners from direct federal taxation, setting the stage for the modern fiscal state.
The Revenue Act of 1913 and the Birth of Modern Filings
Just months after the 16th Amendment passed, Congress enacted the Revenue Act of 1913. This law officially established the modern permanent income tax system. Key elements of this foundational era included:
- A very high threshold: The tax applied to less than one percent of the population, targeting only individuals earning more than 3,000 dollars (or 4,000 for married couples).
- Progressive rates: A base tax rate of one percent applied to net income, with a surtax that climbed up to six percent for the wealthiest Americans.
- Immediate withholding evolution: While initial enforcement relied on voluntary reporting and corporate withholding on bond interest, the system laid the groundwork for the complex reporting structures you navigate today.
Step-by-Step Evolution of Rates, Brackets, and WWII Withholding Taxes
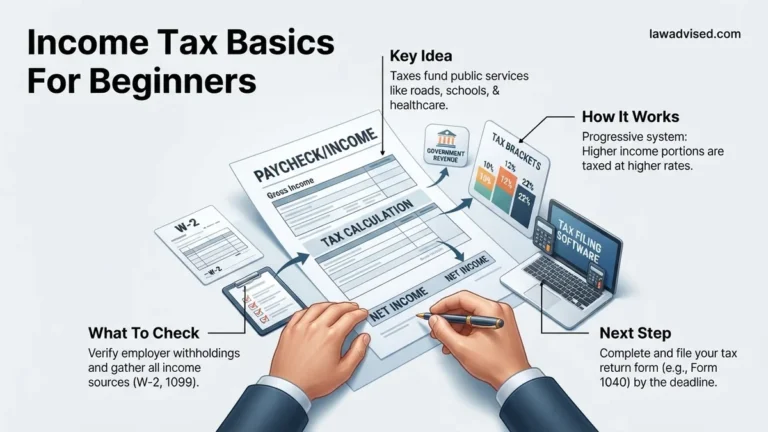
The structure of the federal income tax changed drastically during the mid-20th century. Before 1943, citizens paid their annual tax bill in one lump sum. World War II forced a massive fiscal overhaul to fund military operations.
1. The Introduction of Pay-As-You-Earn Withholding
Congress passed the Current Tax Payment Act of 1943. This legislation introduced the modern payroll withholding system. Employers began deducting income tax directly from employee paychecks every pay period. This ensured a steady cash flow for the federal government during wartime.
2. Expansion to a Mass Tax System
Prior to 1939, only the wealthiest top tier of Americans filed returns. By 1945, federal income tax transformed from a class tax into a mass tax. Over 40 million Americans filed returns annually, fundamentally shifting the relationship between citizens and federal revenue agencies.
According to economic studies from the Brookings Institution, this withholding mechanism permanently increased tax compliance and revenue collection efficiency. Marginal rates also peaked during this era, climbing above 90 percent for top earners in the post-war decades before subsequent legislative reforms reduced them.
What If It Still Doesn’t Make Sense How Modern Tax Brackets Developed
Tax history and marginal rate structures often confuse taxpayers trying to understand modern liabilities. If historical tax mechanics still seem unclear, follow these steps to clarify your understanding:
- Review historical tax bracket charts provided by the Internal Revenue Service or the Tax Foundation to see how rates scaled over decades.
- Differentiate between nominal tax rates and effective tax rates, keeping in mind that marginal systems tax income at incremental thresholds rather than all at once.
- Consult a certified public accountant or licensed tax attorney to map your current 2026 liability against historical precedents if conducting academic or estate research. Professional consultation fees typically range from $200 to $500 per hour depending on complexity.
- Utilize official government archives and congressional research reports for primary source data on tax legislation changes.
Conclusion
Tracing the history of the federal income tax reveals a continuous adjustment between national funding needs and economic policy. From its modest 1913 inception to the complex withholding and bracket systems used today, the tax code has profoundly shaped American finance. According to verified research and expert sources from economic historians, understanding these legislative milestones provides essential context for modern financial planning. Your next step is to review your current 2026 tax documents against current marginal brackets to ensure accurate filing.
❓ Frequently Asked Questions
Why did the U.S. government rely on tariffs before the income tax?
Throughout the 19th century, federal operations and debt were primarily funded through custom duties and tariffs on imported goods rather than internal taxes on individuals.
What specific event triggered the passage of the 1861 Revenue Act?
The escalating financial demands of the American Civil War forced President Abraham Lincoln and Congress to seek alternative revenue streams, leading to the nation’s first income tax.
How did Pollock v. Farmers’ Loan & Trust Co. impact tax history?
The 1895 Supreme Court decision invalidated the Income Tax Act of 1894, forcing proponents of federal taxation to pursue a constitutional amendment rather than simple statutory fixes.
How did World War II change federal tax collection methods?
To secure immediate revenue for the war effort, the Current Tax Payment Act of 1943 introduced employer-based tax withholding directly from employee paychecks.
Did the original 1913 income tax apply to everyone?
No, the initial tax enacted under the Revenue Act of 1913 applied only to a very small percentage of the wealthiest Americans, featuring high exemption thresholds.
What was the significance of the Tax Reform Act of 1986?
The 1986 reform drastically simplified the tax code, reduced the number of tax brackets, and eliminated numerous shelters, marking one of the most substantial overhauls in modern history.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.