Savers Credit Explained 2026 A Step-by-Step Guide
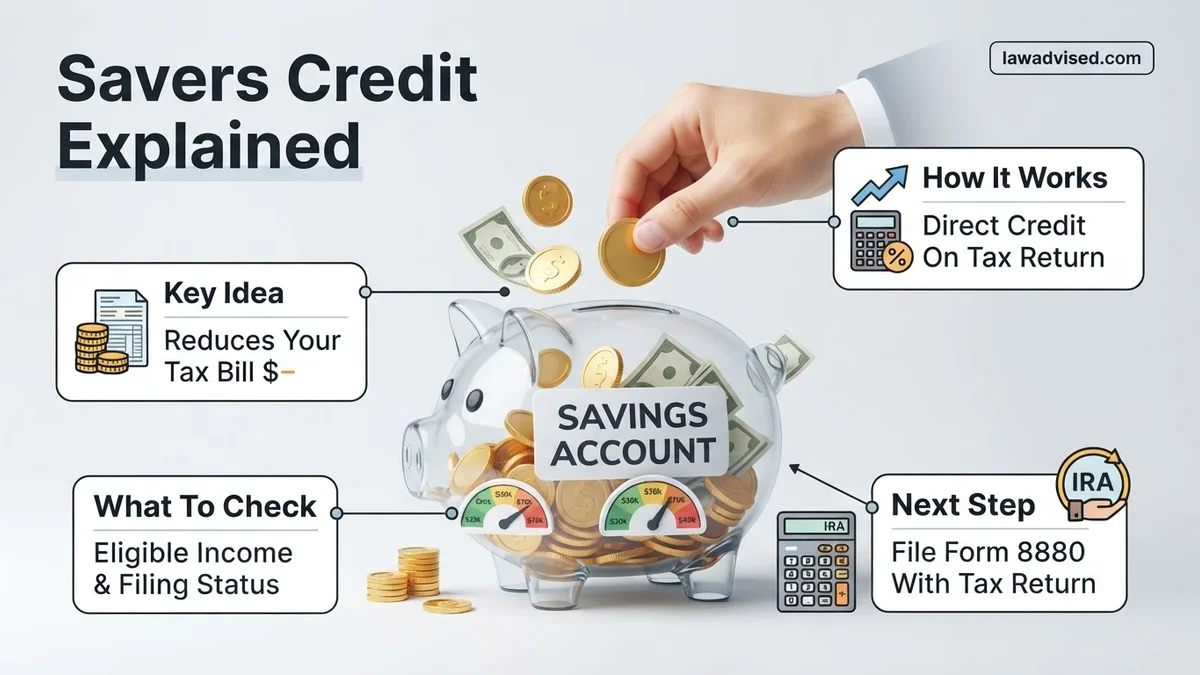
The Savers Credit is a valuable tax credit for low- to moderate-income taxpayers who contribute to a retirement account like an IRA or 401(k). Depending on your income and filing status, the IRS provides a matching percentage of 50%, 20%, or 10% on up to $2,000 of contributions ($4,000 for married filing jointly).
The Retirement Savings Contributions Credit, commonly known as the Savers Credit, is a valuable federal tax credit designed to help low- and moderate-income workers save for retirement. If you contribute to a traditional or Roth IRA, a 401(k), or another eligible retirement plan, the government may reward you by reducing your tax bill dollar-for-dollar.
For the 2026 tax year, understanding this credit is crucial because it directly boosts your tax refund or lowers your tax liability while encouraging you to build long-term financial security. Instead of just a tax deduction that lowers your taxable income, this credit gives you an extra financial incentive based on the money you are already setting aside for your future.
Key Takeaways
- The credit offers a 50%, 20%, or 10% match on retirement contributions.
- Must be at least 18 years old, not a full-time student, and not a dependent.
- Maximum contribution eligible is $2,000 per person ($4,000 for joint filers).
- It is a non-refundable credit, meaning it can reduce your tax liability to zero.
- Eligible accounts include traditional and Roth IRAs, 401(k)s, 403(b)s, and ABLE accounts.
What Causes Low Retirement Savings: The Problem the Savers Credit Solves
Building a retirement nest egg is difficult when everyday living expenses consume most of your paycheck. Many lower-income earners struggle to find any extra cash to put toward future security. Without targeted government intervention, the gap between high earners and modest earners in retirement preparedness would widen even further.
The Financial Barriers for Moderate-Income Earners
When you live paycheck to paycheck, setting aside ten percent of your earnings for a 401(k) feels impossible. High rent, healthcare costs, and groceries leave little room for voluntary savings. Traditional tax breaks often fail to help because if you are in a very low tax bracket, you do not owe much income tax to begin with. Standard deductions already drop your tax liability close to zero, making regular tax-deferred accounts less immediately motivating.
How the Savers Credit Bridges the Gap
The Savers Credit directly targets this exact problem by offering a financial boost specifically calculated for lower-income brackets. It acts as a matching incentive from the IRS. By giving you a tax credit worth up to fifty percent of your retirement contributions, the government lowers the barrier to entry. This makes the painful choice of saving versus immediate survival a bit easier to manage.
How to Qualify for the Savers Credit: Eligibility Rules and Income Limits
To claim the Savers Credit on your 2026 federal tax return, you must meet specific age, dependency, and income criteria. Missing even one of these basic requirements means you will not be able to claim the credit.
Basic Eligibility Requirements
You must be at least 18 years old by the end of the tax year to qualify. Additionally, you cannot be enrolled as a full-time student during the year, and you cannot be claimed as a dependent on someone else’s tax return. If you file as a full-time student or someone else claims you as a qualifying child, the IRS disqualifies you from this specific credit.
2026 AGI Thresholds and Matching Tiers
Your Adjusted Gross Income (AGI) determines your matching percentage, which ranges from 10 percent to 50 percent of your contributions. For the 2026 tax year, the maximum contribution eligible for the credit is 2,000 dollars per individual (or 4,000 dollars for married couples filing jointly). Here is how the income tiers break down:
- 50 Percent Match: Available to single filers with an AGI up to designated lower limits, and married couples filing jointly up to specific threshold caps.
- 20 Percent Match: Applies to moderate AGI ranges that sit right above the 50 percent tier cutoff.
- 10 Percent Match: Targets earners at the higher end of the qualifying AGI spectrum.
- 0 Percent Match: If your AGI exceeds the maximum statutory limit for your filing status, your matching percentage drops to zero.
Step-by-Step Guide to Calculating and Claiming Your Savers Credit
Claiming the Retirement Savings Contributions Credit requires accurate reporting on your federal tax return. Because the IRS adjusts income thresholds annually, staying informed about the 2026 rules ensures you maximize your potential benefit without triggering an audit.
Step 1: File the Correct Tax Form
You cannot claim the credit on a basic 1040 without supplemental documentation. You must attach IRS Form 8880 (Credit for Qualified Retirement Savings Contributions) to your main filing.
- Gather your year-end retirement statements showing all eligible 2026 contributions.
- Calculate your Adjusted Gross Income (AGI) using your primary tax documents.
- Complete Form 8880 by entering your total contributions, subtracting any recent distributions, and applying the correct matching percentage (50%, 20%, or 10%) based on your filing status and 2026 income bracket.
Step 2: Transfer the Credit to Form 1040
Once you calculate your final credit amount on Form 8880, you must move that figure to your main return. Enter the calculated credit onto Schedule 3 (Form 1040), line 4, and then carry that total over to your Form 1040.
What If Your Credit Doesn’t Apply: Troubleshooting Non-Refundable Tax Limits
The Savers Credit is a non-refundable tax credit. This structural limitation means the credit can reduce your federal income tax liability all the way down to zero, but any remaining credit value cannot be paid out to you as a cash refund.
Understanding Tax Liability Thresholds
If your total tax liability for 2026 is $400, and your calculated Savers Credit is $500, you will only receive a $400 benefit. The remaining $100 simply disappears. It does not roll over to future tax years, nor does it convert into a refund check.
What If It Still Doesn’t Work?
If your credit calculation seems incorrect or your software rejects your Form 8880, systematic troubleshooting is required. According to verified financial planning standards, taxpayers facing complex credit rejections should take targeted action.
- Verify that your retirement plan type qualifies under IRS guidelines, as certain employer-sponsored fringe benefit plans are excluded.
- Check your AGI against the exact 2026 inflation-adjusted phase-out limits, ensuring you did not exceed the maximum cutoff for your specific filing status.
- Review recent taxable distributions taken between 2024 and 2026, which legally reduce your eligible contribution amount dollar-for-dollar.
- Consult a certified public accountant (CPA) or Enrolled Agent if software errors persist, with professional tax advisory services typically costing between $200 and $500 depending on complexity.
Conclusion
Navigating the nuances of the Savers Credit ensures you do not leave free money on the table for your retirement. By accurately filing Form 8880 and accounting for non-refundable liability caps, you can optimize your 2026 tax return. According to verified research and expert sources from the IRS and financial planning institutes, taking proactive steps with your retirement contributions yields immediate tax benefits. Your actionable next step is to review your year-to-date retirement account statements and verify your projected 2026 AGI today.
❓ Frequently Asked Questions
How much is the maximum Savers Credit I can receive?
The maximum credit is $1,000 per individual ($2,000 for married couples filing jointly). This is calculated by taking 50% of the maximum contribution cap of $2,000 per person.
Can full-time students claim the Savers Credit?
No, individuals who were enrolled as full-time students for any part of five calendar months during the tax year are generally disqualified from claiming the credit.
How do rollovers affect the Savers Credit calculation?
Eligible contributions for the credit must be reduced by any recent distributions or rollovers you took from your retirement accounts during the testing window.
What IRS form is required to claim the Savers Credit?
You must file IRS Form 8888 (Credit for Qualified Retirement Savings Contributions) along with your Form 1040 to claim the credit.
Does the Savers Credit apply to Roth contributions?
Yes, contributions made to Roth IRAs and Roth designated accounts (like a Roth 401(k)) qualify for the credit, unlike the standard retirement tax deduction.
What happens if my tax liability is lower than my Savers Credit?
Because the credit is non-refundable, any amount of the credit that exceeds your total tax liability is simply lost and cannot be carried forward to future tax years.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.