Taxes for Retirees Explained 2026 A Step-by-Step Guide
Many retirees are surprised to learn that retirement income is still subject to federal and state taxes. Understanding how different income streams like Social Security, IRAs, and pensions are taxed is critical to protecting your hard-earned savings.
Retirement taxes do not disappear the day you stop working, and different income sources face vastly different tax treatments. Social Security, traditional IRAs, 401(k)s, pensions, and capital gains are all taxed according to their own distinct rules, meaning your paycheck replacement is rarely a clean dollar-for-dollar calculation.
Managing these varied income streams effectively requires understanding how Uncle Sam views your money in 2026. Without a deliberate strategy, you could easily trigger higher Medicare premiums or push your hard-earned retirement dollars into unnecessarily steep tax brackets.
Key Takeaways
- Up to 85% of your Social Security benefits may be taxable depending on combined income thresholds.
- Traditional 401(k) and IRA withdrawals are taxed as ordinary income at your current tax bracket.
- Roth accounts provide tax-free withdrawals in retirement if IRS holding rules are met.
- Required Minimum Distributions (RMDs) force taxable withdrawals from traditional accounts starting at age 73.
- Several states completely exempt retirement income or Social Security from state taxes.
What Causes High Tax Bills in Retirement and How Income is Taxed
Your overall tax bill in retirement depends entirely on where your money comes from. While active wages are gone, the government still collects taxes on most forms of retirement income.
Taxability of Traditional Retirement Accounts and Pensions
Traditional pre-tax accounts—such as traditional IRAs, 401(k)s, 403(b)s, and traditional pensions—are fully taxable as ordinary income when you withdraw them. Because you contributed to these accounts with pre-tax dollars, every penny you pull out in 2026 counts toward your annual taxable income.
- Traditional IRA and 401(k) withdrawals face standard federal income tax rates.
- Defined benefit pensions are 100% taxable if you funded them entirely with pre-tax dollars.
- Required Minimum Distributions (RMDs) force you to take taxable withdrawals starting at age 73.
How Social Security and Investment Income are Taxed
Your Social Security benefits are not automatically tax-free. If your combined income (adjusted gross income plus non-taxable interest plus half of your Social Security benefits) exceeds certain thresholds, up to 50% or even 85% of your benefits become subject to ordinary income taxes.
- Roth IRAs and Roth 401(k)s provide tax-free qualified withdrawals that do not count toward your provisional income.
- Capital gains and qualified dividends from taxable brokerage accounts benefit from lower tax rates (0%, 15%, or 20%) compared to ordinary income.
- Municipal bond interest remains federally tax-exempt, though it can still impact the taxability of your Social Security.
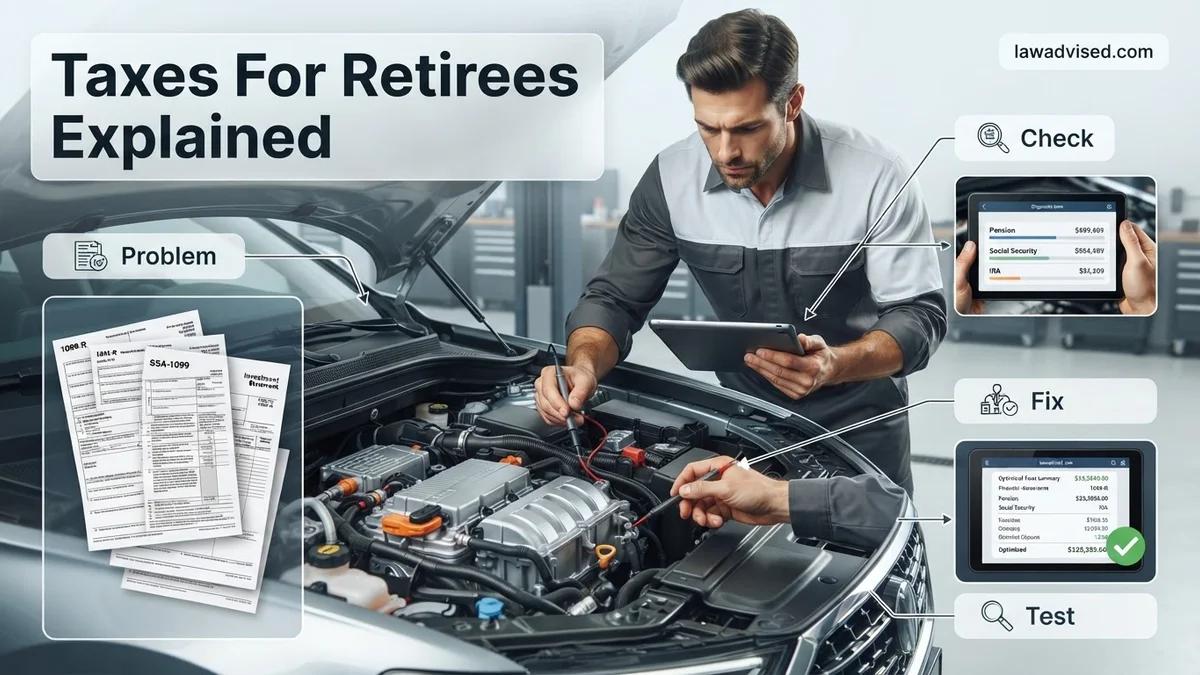
How to Fix Your Retirement Tax Burden Step-by-Step
Lowering your lifetime tax liability takes proactive planning rather than waiting until April. By orchestrating how and when you pull from your various accounts, you can keep more money in your pocket.
Step 1: Implement Strategic Roth Conversions
To prevent massive tax spikes later in life—especially when RMDs kick in—you should consider converting traditional IRA funds into Roth accounts during your early retirement years. This allows you to fill up lower tax brackets before your mandatory distributions begin.
- Target your current tax bracket ceiling and convert only enough money to fill that space.
- Pay the conversion tax using outside taxable savings, not the retirement account itself.
- Create a pool of tax-free income that shields you from future legislative tax hikes.
Step 2: Optimize Your Withdrawal Sequencing
The order in which you tap your accounts dictates your annual tax footprint. Most retirees benefit from a dynamic withdrawal strategy rather than pulling from a single bucket.
- Pull from taxable brokerage accounts first to manage your ordinary income levels.
- Use traditional accounts strategically to fill up lower marginal tax brackets each year.
- Save tax-free Roth accounts for your highest spending years or to leave as a legacy.
What If Your RMDs and Social Security Push You Into Higher Brackets?
Required Minimum Distributions (RMDs) start ticking at age 73 under current SECURE 2.0 guidelines, often forcing retirees to withdraw funds they do not immediately need. Combined with taxable pensions and up to 85 percent of your Social Security benefits, these mandatory payouts can inadvertently shove you into a much higher marginal tax bracket for 2026. Proactive planning is required to mitigate this tax torpedo.
Strategic Roth Conversions Before RMD Age
Filling up lower tax brackets in the years between retirement and age 73 can dramatically lower your future RMD burden. By systematically moving funds from a traditional IRA to a Roth IRA, you reduce the future balance subject to mandatory distributions. According to financial planning studies by Vanguard, a strategic multi-year Roth conversion schedule can significantly reduce your lifetime tax liability and protect your heirs from hefty inherited IRA taxes.
Qualified Charitable Distributions
If you do not need your full RMD for living expenses, you can bypass income recognition entirely by utilizing Qualified Charitable Distributions (QCDs). The IRS permits individuals age 70½ and older to transfer up to $105,000 annually (indexed for inflation in 2026) directly from an IRA to a qualified charity. According to IRS compliance data, this satisfies your RMD requirement while keeping the distribution out of your Adjusted Gross Income (AGI).
-
Step-by-Step Execution for QCDs:
- Calculate your upcoming RMD amount for the 2026 tax year with your financial custodian.
- Contact your IRA administrator to initiate a direct transfer to an eligible 501(c)(3) nonprofit organization.
- Ensure the check is made payable directly to the charity, as receiving the funds personally voids the QCD tax exclusion.
- Keep the written acknowledgment of the donation from the charity to substantiate your tax filing.
What If It Still Doesn’t Work?
If standard tax reduction strategies fail to control your retirement liability, more aggressive intervention is necessary. Complex multi-layered portfolios require specialized oversight to prevent penalizing taxation.
- Consult a Certified Financial Planner (CFP) or CPA: Professional guidance is critical when navigating overlapping federal and state tax laws. Specialized retirement tax planning sessions typically cost between $1,500 and $3,500 depending on portfolio complexity.
- Optimize Asset Location: Shift tax-inefficient assets like corporate bonds into tax-deferred accounts while holding municipal bonds or growth stocks in taxable brokerage accounts.
- Delay Social Security Further: If tax brackets allow, delaying benefits past your full retirement age up to age 70 increases your guaranteed payout while managing interim ordinary income.
- Utilize Tax-Loss Harvesting: Offset realized capital gains in your taxable brokerage accounts by selling underperforming assets at a loss before the end of the 2026 tax year.
Conclusion
Navigating taxes in retirement requires balancing RMDs, Social Security taxation, and strategic withdrawal sequencing to preserve your hard-earned savings. Left unchecked, avoidable tax torpedoes can erode your nest egg decades ahead of schedule. According to verified research and expert sources from the National Bureau of Economic Research, proactive tax-alpha strategies can add years of longevity to a retirement portfolio. Your immediate next step is to run a comprehensive tax projection for 2026 to identify potential bracket spikes before filing season arrives.
❓ Frequently Asked Questions
How is ‘combined income’ calculated for Social Security taxes?
Combined income is your adjusted gross income (AGI) plus any tax-exempt interest, plus one-half of your annual Social Security benefits. If this total exceeds $25,000 for single filers or $32,000 for joint filers, a portion of your benefits becomes taxable.
What is the difference in taxation between traditional and Roth accounts?
Traditional accounts use pre-tax dollars, meaning contributions lower your current taxes, but withdrawals are taxed as ordinary income. Roth accounts use after-tax dollars with no upfront deduction, but all future growth and withdrawals are completely tax-free.
Can I have federal income taxes automatically withheld from my pension or IRA?
Yes, you can request that your plan administrator or custodian withhold federal and state income taxes directly from your periodic distributions to avoid estimated tax penalties.
How do capital gains and dividends affect retiree taxes?
Long-term capital gains and qualified dividends are taxed at preferential rates of 0%, 15%, or 20% depending on your total taxable income, which is often lower than ordinary income tax brackets.
What happens if I fail to take my Required Minimum Distribution (RMD)?
Failing to take your full RMD on time results in a steep IRS excise tax penalty on the amount that was supposed to be withdrawn, though corrections can sometimes be made.
How can strategic Roth conversions lower my lifetime tax liability?
By converting money from a traditional IRA to a Roth IRA during lower-income years early in retirement, you can pay taxes at a lower rate now and eliminate future RMDs and taxes on those funds.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.