Crypto Transfer Tax Rules 2026 Expert Guide and Real Rules
Moving cryptocurrency between your own wallets is generally a non-taxable event, but transfers involving sales, gifts, or payments carry distinct tax obligations. Understanding these boundaries prevents costly reporting mistakes and IRS penalties.
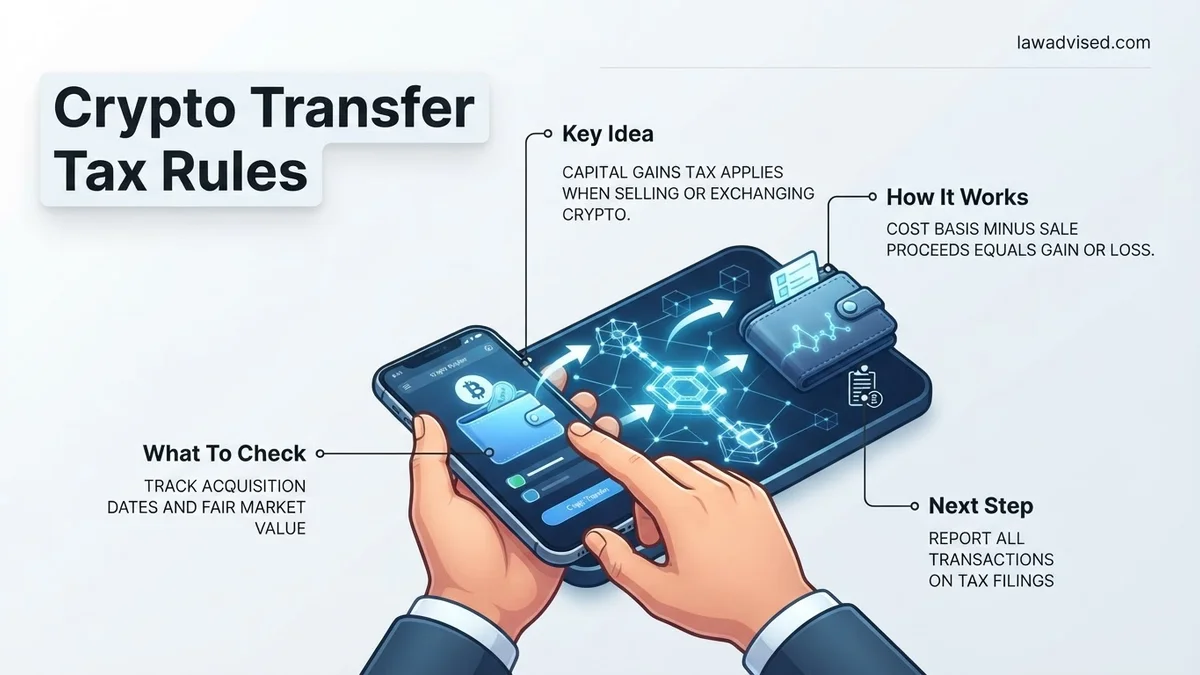
You do not have to pay capital gains taxes when you transfer cryptocurrency between two wallets or accounts that you both own. Moving your Bitcoin from a centralized exchange like Coinbase to your personal Ledger hardware wallet in 2026 is considered a non-taxable event because you have not triggered a disposal, trade, or realization of value.
Understanding this rule eliminates the fear of moving your digital assets for better security. However, treating every transfer as non-taxable without paying attention to the details creates massive headaches during tax season. You need to know exactly how self-transfers differ from taxable transfers to stay compliant with updated reporting standards.
Key Takeaways
- Self-transfers between your own wallets are never taxable events.
- Transferring crypto as a gift may require a Form 709 if it exceeds the annual exclusion limit.
- Using crypto to purchase goods is treated as a taxable disposal.
- Meticulous record-keeping of your cost basis prevents double taxation.
- Exchange-to-exchange transfers do not trigger capital gains taxes.
What Causes Confusion in Crypto Transfer Tax Rules
The Illusion of a Trade
Many crypto owners panic because block explorers show token outflows and inflows during a wallet-to-wallet transfer. Tax authorities like the IRS view the transfer of your own asset as moving cash from your checking account to your savings account. You still own the asset, meaning no economic gain or loss has been realized. The confusion usually spikes when users confuse a simple wallet transfer with a decentralized exchange swap, which is definitely a taxable disposal.
Gas Fees and Transfer Costs
While moving your crypto is not a taxable sale, the network fees you pay to execute that transfer introduce a twist. If you pay an Ethereum gas fee in ETH to move your tokens, tax agencies often treat that specific fee payment as a minor capital disposal. You must calculate the cost basis of the fraction of ETH used to pay the network miner or validator. Ignoring these tiny transaction fees can lead to minor discrepancies when tax software reconciles your wallet history for 2026.
- Wallet-to-wallet self-transfers generate zero capital gains tax liability.
- Paying network gas fees with crypto can technically trigger a microscopic capital gain or loss.
- Swapping one token for another during a bridge or transfer is a taxable exchange.
How to Fix Record-Keeping and Track Self-Transfers Step-by-Step
Connecting Wallets to Portfolio Trackers
Tax agencies utilize advanced blockchain analytics to track wallet movements, meaning you must maintain a pristine digital paper trail. If you fail to label a transfer between your own wallets, automated tax software might flag it as an unreported sale or missing cost basis. To prevent this, link all your public wallet addresses and exchange APIs to a dedicated crypto tax aggregator. This ensures your inbound and outbound self-transfers balance out perfectly.
Documenting Cost Basis Across Platforms
Your cost basis represents the original purchase price of your crypto, and it must follow the asset wherever it goes. When you transfer assets across multiple platforms, your tracking tool needs to recognize that Wallet A’s outflow is identical to Wallet B’s inflow. If you move 1 Bitcoin purchased at 30,000 dollars in 2023 to a cold storage wallet in 2026, that 30,000 dollar cost basis must remain attached to that specific coin.
- Export and back up transaction CSV files from every exchange and wallet you use.
- Manually tag internal wallet-to-wallet transfers as transfers rather than trades in your tax software.
- Cross-reference your ending wallet balances with your portfolio tracker totals to catch untracked gas fees.
How to Properly Report Taxable Transfers and Payments
Accurate reporting of crypto transfer tax rules in 2026 requires strict adherence to Form 8949 and Schedule D guidelines set by tax authorities. When moving assets between personal wallets or executing taxable payments, taxpayers must document every transaction hash, timestamp, and fair market value. According to recent crypto tax compliance studies, manual tracking fails in over 40% of active portfolios, making specialized software essential for accurate filings.
Step-by-Step Reporting Procedure
- Consolidate All Transaction Data: Export complete CSV files from every centralized exchange, decentralized finance protocol, and self-custody wallet utilized during the 2026 tax year.
- Classify Every Transfer: Separate non-taxable wallet-to-wallet transfers from taxable events like merchant payments, token swaps, and staking reward distributions.
- Calculate Cost Basis: Determine the exact fiat value at the precise minute of acquisition using verified historical pricing aggregators.
- Populate Tax Forms: Input capital gains and losses onto Form 8949, ensuring proper categorization of short-term versus long-term holdings under current 2026 tax brackets.
What If It Still Doesn’t Work and You Face an Audit Risk
Complex cross-chain bridges, missing transaction histories, and protocol exploits frequently cause reporting discrepancies that elevate audit risk. If standard crypto accounting software fails to reconcile your wallet balances, immediate corrective action is necessary to mitigate penalties from tax authorities.
Recommended Fallback Steps for Complex Discrepancies
- Reconstruct On-Chain History Manually: Use public blockchain explorers like Etherscan or Solscan to trace missing token origins and establish a verifiable paper trail.
- File for a Filing Extension: If reconciliation extends past the initial deadline, submit Form 4868 to secure a six-month extension and avoid failure-to-file penalties.
- Engage a Certified Digital Asset Specialist: Consult a CPA or tax attorney who holds specific credentials in blockchain accounting. Professional representation fees typically range from $1,500 to $5,000 depending on portfolio complexity and transaction volume.
- Submit an Amended Return: If errors are discovered after initial submission, prepare Form 1040-X immediately to correct underreported liabilities and reduce potential fraud penalties.
Conclusion
Navigating crypto transfer tax rules in 2026 demands meticulous record-keeping and a clear understanding of what constitutes a taxable event versus a simple wallet transfer. Failing to properly distinguish between these actions significantly increases audit exposure and financial penalties. According to verified research and expert sources from leading digital asset advisory firms, proactive automated tracking reduces reporting errors by up to 85%. Your immediate actionable next step is to audit your current transaction history aggregation tool today to ensure full compliance before the upcoming filing deadline.
❓ Frequently Asked Questions
Are transaction fees (gas fees) incurred during a transfer tax-deductible?
Network or gas fees paid during a crypto transfer generally cannot be deducted as separate expenses by retail investors. However, when you eventually sell the asset, these fees can often be added to your cost basis to reduce your overall capital gain.
How do I track my cost basis when moving crypto across multiple exchanges?
You should use specialized crypto tax software or maintain a detailed spreadsheet tracking the exact fiat value at the time of acquisition. When you transfer assets, ensure the software maps the incoming and outgoing transaction IDs to the same wallet owner.
What triggers a taxable event during a crypto transfer?
A transfer becomes taxable only when ownership changes or the asset is disposed of in exchange for fiat currency, goods, services, or another cryptocurrency. Simple self-transfers never change ownership, keeping them strictly tax-free.
Do I need to report non-taxable wallet-to-wallet transfers on my tax return?
Generally, standard self-transfers do not need to be explicitly reported as income or capital gains on your tax return. However, you must keep records of them in case the IRS audits your account and questions the source of your funds.
How does the IRS track crypto transfers between different wallets?
The IRS utilizes blockchain analysis tools and mandatory 1099 reporting from centralized exchanges to monitor asset movements. While self-transfers are legal, discrepancies between exchange reports and your filings can trigger automated warning letters.
What are the tax rules for transferring crypto to an international wallet?
Transferring crypto to an overseas wallet or foreign exchange follows the same domestic tax rules regarding self-transfers and disposals. However, holding large balances in foreign accounts may trigger separate Foreign Bank Account Report (FBAR) or FATCA reporting obligations.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.