Rental Property Tax Deductions Expert 2026 Guide
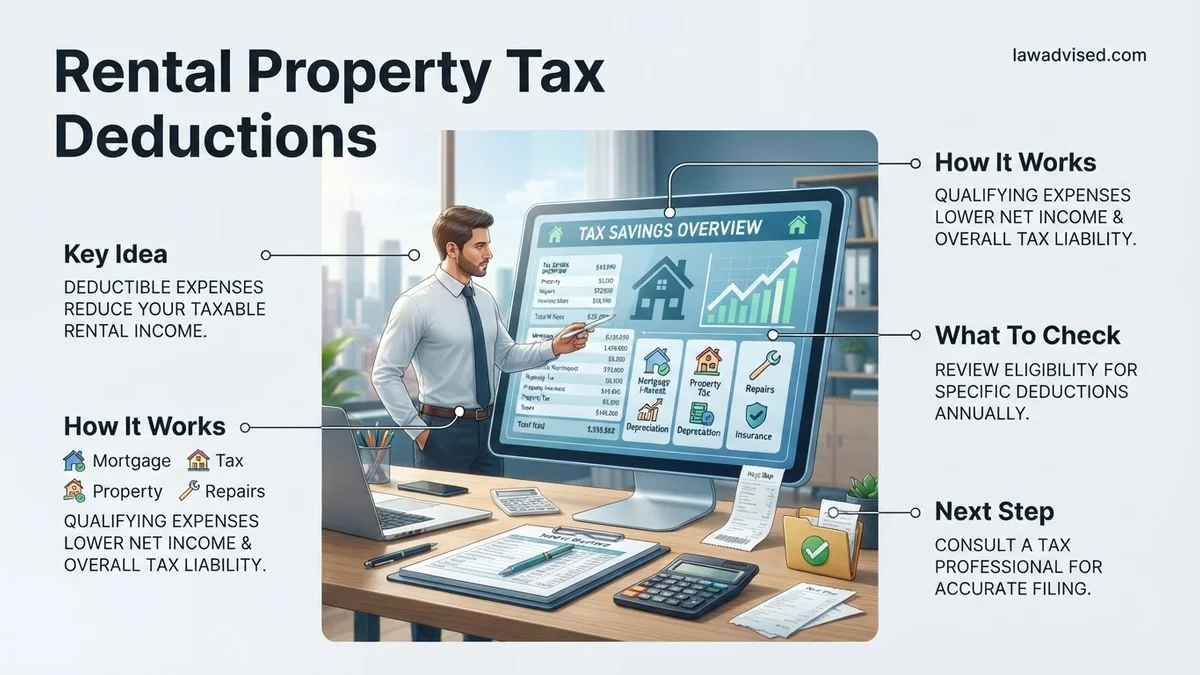
Lower your taxable rental income by leveraging legal deductions like mortgage interest, property taxes, and depreciation. Properly identifying these expenses is essential for maximizing your annual real estate investment profits.
As a rental property owner, your biggest weapon against high tax bills is a comprehensive understanding of IRS write-offs. You can legally deduct almost every ordinary and necessary expense incurred to manage, maintain, and operate your rental real estate. By taking full advantage of these deductions, you drastically lower your net taxable rental income, keeping more cash in your pocket.
Navigating the complex landscape of 2026 federal tax rules requires strict attention to detail. Missing out on common write-offs like mortgage interest, depreciation, and localized maintenance costs means leaving thousands of dollars on the table. The following breakdown covers the essential itemized deductions you need to claim this tax season and how to properly categorize them.
Key Takeaways
- Deduct mortgage interest and property taxes to significantly lower your annual tax liability.
- Distinguish between immediate repairs and capital improvements that require multi-year depreciation.
- Write off ordinary and necessary operational expenses like insurance, utilities, and advertising.
- Utilize IRS safe harbor rules to instantly deduct minor renovation and maintenance costs.
- File accurate Schedule E forms and maintain meticulous expense records to withstand audits.
What Causes High Taxable Rental Income and Missed Deductions
Many landlords face unexpectedly high tax bills because they fail to track expenses properly or misunderstand IRS guidelines. When you mix personal and business finances, or lump complex maintenance costs into vague categories, you invite audits and miss out on valuable deductions.
Common Tracking Failures That Cost Landlords Money
- Failing to separate routine repairs from capital improvements, leading to disallowances.
- Losing track of local travel mileage for property inspections and tenant meetings.
- Forgetting to deduct prepaid expenses like hazard insurance or annual software subscriptions.
- Overlooking utility payments that you cover on behalf of the tenant.
The Danger of Commingling Personal and Rental Expenses
Running your rental property finances through your personal checking account creates a paperwork nightmare. If the IRS audits your 2026 return, you must prove every single expense directly relates to the rental business. Keep dedicated business accounts to ensure every dollar spent on mortgage interest, repairs, or property management is easily traceable and fully deductible.
How to Fix Your Write-Off Strategy with Step-by-Step Deductions
Fixing your tax strategy means actively itemizing every eligible expense category allowed under current federal tax codes. The most reliable way to slash your taxable rental income is to systematically log the top deductions every single month.
Top Deductible Operating Expenses
- Mortgage Interest: The interest portion of your monthly mortgage payment is fully deductible, representing the largest write-off for most leveraged landlords.
- Property Taxes: State and local property taxes assessed on your rental real estate reduce your taxable income dollar-for-dollar.
- Insurance Premiums: Landlord liability policies, hazard insurance, and flood insurance premiums are 100% deductible business expenses.
- Professional Fees: Legal fees, accountant fees, tax preparation software, and eviction costs related to the property qualify as deductions.
Mastering Travel and Auto Write-Offs
Driving to your rental property for inspections, maintenance oversight, or tenant showings generates deductible travel expenses. For the 2026 tax year, you can track your exact business mileage and multiply it by the IRS standard mileage rate, or deduct actual vehicle expenses like gas, oil, and depreciation based on business-use percentage. Always maintain a contemporaneous mileage log detailing the date, miles driven, and business purpose of each trip.
How to Correctly Separate Routine Repairs from Capital Improvements
Navigating rental property tax deductions in 2026 requires strict adherence to IRS capitalization rules. Misclassifying an expense can trigger an audit or delay your tax refunds.
Understanding Routine Repairs
Routine repairs keep your property in normal, efficient operating condition without adding significant value. You can deduct these expenses fully in the year you pay for them. According to IRS guidelines, fixing a broken window, painting a wall, or repairing a leaky faucet are immediate deductions.
Identifying Capital Improvements
Capital improvements prolong the property’s life, adapt it to new uses, or increase its overall value. You cannot deduct these costs all at once. Instead, you must depreciate them over several years using IRS depreciation schedules.
- Assess structural changes: Adding a roof, installing a brand-new HVAC system, or building an extension are capital improvements.
- Check financial thresholds: Utilize the De Minimis Safe Harbor election to immediately deduct items up to $2,500 per invoice.
- Review betterment standards: Ask whether the work fixes a pre-existing defect from before you purchased the property. If yes, it is likely an improvement.
What If Passive Loss Limits Apply?
Many real estate investors face a frustrating hurdle when their deductions exceed their rental income. The IRS classifies rental real estate activities as passive, meaning strict loss limitation rules often apply under current 2026 tax codes.
- Verify the $25,000 active participation allowance: If your modified adjusted gross income falls below $100,000, you can deduct up to $25,000 of passive losses against your active income.
- Check phase-out thresholds: This special allowance phases out completely when your income reaches $150,000.
- Qualify as a Real Estate Professional: Spend more than 750 hours and over half of your working time in real estate trades to bypass passive loss limits entirely.
- Carry forward unused losses: Unallowed losses do not disappear; you can carry them forward indefinitely to offset future rental income or gains upon the property’s sale.
- Consult a certified public accountant: Complex multi-property portfolios often require professional tax representation. Certified tax professionals typically charge between $300 and $600 per hour for specialized real estate advisory services.
Conclusion
Maximizing your rental property tax deductions requires meticulous record-keeping and a clear understanding of the IRS distinction between repairs and capital improvements. Failing to properly categorize expenses or ignoring passive loss limitations can cost landlords thousands of dollars annually. According to verified research and expert financial sources, proactive tax planning remains the most effective tool for increasing net operating income. Your immediate next step is to audit your year-to-date receipts and separate all capital expenditures from routine maintenance items before handing your files over to a qualified tax professional.
❓ Frequently Asked Questions
How does residential rental property depreciation work for tax purposes?
Residential rental buildings can be depreciated over a recovery period of 27.5 years using the Modified Accelerated Cost Recovery System (MACRS). Land value cannot be depreciated, so you must separate the building value from the land value on your purchase settlement statement.
What is the exact difference between a repair and a capital improvement?
A repair keeps your property in normal, efficient operating condition without adding significant value or extending its life, making it fully deductible in the current year. An improvement adds value, prolongs the property’s life, or adapts it to a new use, requiring it to be depreciated over multiple years.
How do passive activity loss rules impact my rental deductions?
If your modified adjusted gross income is under $100,000, you can generally deduct up to $25,000 of passive rental losses against active income if you actively participate. High earners exceeding $150,000 may have their losses suspended and carried forward unless they qualify as real estate professionals.
What are IRS safe harbor rules for small taxpayers regarding repairs?
The De Minimis Safe Harbor allows landlords to deduct items costing up to $2,500 per invoice or item without tracking them as capital assets. Additionally, the Safe Harbor for Small Taxpayers lets buildings with unadjusted bases under $1 million deduct routine maintenance up to lesser dollar thresholds.
Are homeowners association (HOA) fees tax deductible for landlords?
Yes, monthly HOA dues, condo fees, and special assessments paid to maintain common areas or property management are fully deductible rental expenses for the tax year they are paid.
How long should I keep receipts and records of my rental deductions?
You should retain all receipts, invoices, bank statements, and tax documents for at least three to seven years after filing the tax return to protect yourself in the event of an IRS audit.

Ismail Hossain is the founder of Law Advised. He is an Divorce, Separation, marriage lawyer. Follow him.